PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120285

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120285
Automotive Infotainment Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the automotive infotainment systems market size is estimated at USD 28.51 billion in 2026, and is expected to reach USD 38.35 billion by 2031, at a CAGR of 6.11% during the forecast period (2026-2031).
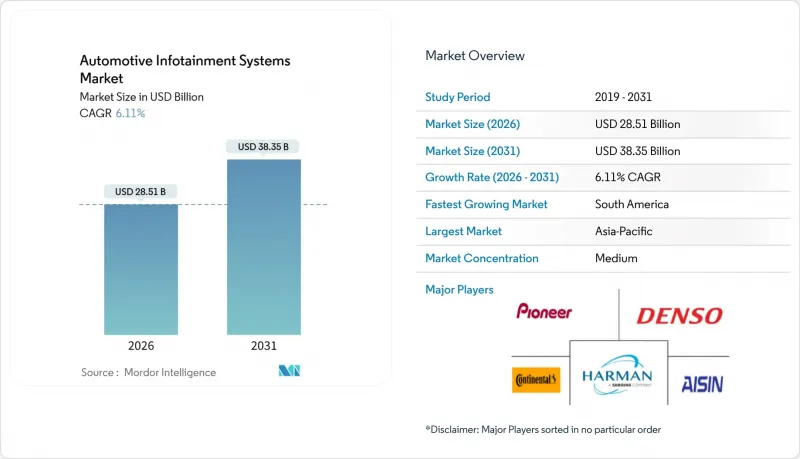
This report is Segmented by Installation Type (In-Dash Infotainment and Rear-Seat Infotainment), Vehicle Type (Passenger Cars and More), Component (Display / Touch-Screen Module and More), Propulsion (ICE Vehicles and More), Connectivity Generation, Operating System, Sales Channel, and Geography. Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Automotive Infotainment Systems Market Trends and Insights
Consumer Demand for Connected Services and 5G Roll-out
Two-fifths of global car owners would consider switching brands for a better infotainment user experience, rising to nearly half in Germany. AT&T began delivering 5G connectivity to Toyota and Lexus vehicles in 2025, enabling real-time rerouting, cloud voice assistants, and low-latency V2X messaging . Network slicing reserves bandwidth for safety traffic while simultaneously streaming 4K video to rear seats, a capability 4G LTE struggles to match. General Motors embedded Apple Music natively across 2025 and 2026 models, offering eight years of free streaming to encourage brand loyalty.
Shift Toward Software-Defined Vehicles and Digital Cockpits
Through over-the-air delivery, software-defined architectures have significantly reduced the feature lag, enabling much faster updates. Toyota's upcoming RAV4, leveraging the Arene platform, is set for continuous updates. Meanwhile, BMW's Operating System X will make its debut on the Neue Klasse in the near future, allowing the automaker to maintain control over data and its monetization. As OEMs increasingly take charge of developing the user-interface layer, Tier-1 suppliers are shifting their focus towards middleware services. Industry projections indicate that automotive software revenue will experience substantial growth in the coming years, with infotainment, connectivity, and security taking a significant share. Suppliers lacking the ability to scale their software talent face the risk of displacement, especially as hardware edges closer to commoditization.
Cost Sensitivity in Entry-Level Models
Price-conscious buyers in emerging markets often forgo touchscreens and connectivity to hit sub-USD 15,000 price points. In India, base trims of the Maruti Suzuki Alto ship with analog clusters, limiting the installed base for premium head units. Chinese entrants intensify price pressure, forcing incumbents to absorb infotainment costs or risk share erosion. Aftermarket Android head units priced at USD 150-300 offer partial remedies but lack deep vehicle integration. The delay in connected adoption restrains network effects vital for app-store ecosystems.
Other drivers and restraints analyzed in the detailed report include:
- Integration of ADAS-Centric HMI Into Infotainment Head Units
- Mandatory eCall and Data-Logging Regulations in Emerging Markets
- Cybersecurity and Liability Risks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The automotive infotainment systems market registered a 73.27% dominance for in-dash units in 2025, yet rear-seat installations are projected to post a 6.13% CAGR through 2031. Luxury OEMs deploy 8K screens and cloud gaming to transform back seats into living spaces and justify up-market pricing. BMW's 31.3-inch Theatre Screen and Mercedes-Benz's dual-screen MBUX rear system illustrate the move toward immersive entertainment that operates only when parked or in autonomous mode. Suppliers focus on modular architectures that share GPUs and memory between front and rear zones to curb duplication of costly silicon.
A second trend is regulatory. UNECE dictates that driver-facing displays show mandatory safety visuals, cementing in-dash primacy, while rear-seat content remains discretionary. Rear-seat setups command higher per-unit revenue-USD 3,000-5,000 in flagship models-creating a profitable niche even though overall volumes trail front displays. Streaming providers align with this niche; Xbox Cloud Gaming leveraged LG partnerships in 2025 to reach vehicle cabins without onboard consoles, supporting the growth trajectory of the automotive infotainment systems market.
Passenger cars accounted for 81.31% of the automotive infotainment systems market size in 2025, reinforcing their mass-market status. Light commercial vehicles are forecast to clock a 6.18% CAGR as logistics firms prioritize telematics, electronic logging, and driver coaching. Indian start-up Euler Motors has equipped its electric delivery vans with a 10-inch Chimera head unit that integrates geofencing and predictive maintenance dashboards, signaling a shift in LCV infotainment from entertainment to mission-critical fleet software.
The commercial segment experiences ruggedization challenges. Fleets demand MIL-STD-810-rated hardware to withstand vibration and dust, which adds minimal cost to components. Yet subscription attach rates are higher; fleet operators willingly pay USD 30-50 per month for connected services that shave fuel use and insurance premiums. OEMs that harmonize passenger-car user-interface learnings with fleet durability stand to gain incremental revenue and strengthen the automotive infotainment systems market.
Head units and domain controllers contributed 43.43% to 2025 revenue, but operating-system software and apps are projected to increase at a 6.27% CAGR through 2031. BMW's in-house Operating System X, built on the Android Open Source Project, illustrates the strategic shift from hardware to recurring licenses. Larger, higher-resolution screens still generate hardware upsell-Volvo's 2026 XC60 display boosts pixel density by one-fifth-yet software dominates incremental margin.
Hardware commoditization spurs tier-1 suppliers to invest in middleware. Elektrobit, BlackBerry QNX, and Wind River monetize hypervisors and secure communication stacks that sit atop SoCs from Qualcomm or NXP. As the automotive infotainment systems market transitions toward software-defined value, suppliers lacking deep code portfolios could face margin compression or displacement.
Complete Report Scope:
- By Installation Type
- In-dash Infotainment
- Rear-seat Infotainment
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- By Component
- Display / Touch-screen Module
- Head Unit / Domain Controller
- Operating-System Software & Apps
- Connectivity ICs & Antenna Modules
- By Propulsion Type
- Internal-Combustion Engine Vehicles
- Battery Electric Vehicles
- Hybrid Electric Vehicles
- By Connectivity Generation
- 4G LTE
- 5G
- Legacy 2G/3G
- By Operating System
- Linux-Based (AAOS, AGL, etc.)
- QNX
- Android Automotive OS
- Others (Proprietary, RTOS)
- By Sales Channel
- OEM-Installed
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Turkey
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia Pacific held 38.77% of the automotive infotainment systems market in 2025, driven by China's substantial production of new-energy vehicles and India's swift embrace of connected cars. In early 2025, Japan rolled out a considerable number of passenger vehicles featuring Toyota's Arene multimedia, while South Korea's Hyundai Mobis showcased holographic head-up displays, highlighting the region's integrated automotive ecosystem. While TSMC and Samsung dominate the semiconductor supply, tensions surrounding Taiwan present potential disruptions. Meanwhile, Southeast Asian nations like Vietnam, though currently modest players, are becoming increasingly receptive to Chinese OEMs offering competitive, feature-rich infotainment systems.
South America is projected to register the fastest growth at a 6.17% CAGR through 2031 as Brazil's 2024 eCall requirement forces cellular connectivity into every new vehicle. In 2025, Argentina's vehicle registrations grapple with aggressive Chinese brands, leveraging advanced infotainment features to challenge established players. Despite hurdles like regional payment fragmentation and currency fluctuations, savvy OEMs can turn connectivity into a steady revenue stream by localizing content, billing, and cloud services.
Europe and North America, while established, remain vibrant. European nations, led by Germany, the UK, and France, are at the forefront of deploying software-defined cockpits, spurred by the General Safety Regulation II's push for ADAS visualization. The U.S. is capitalizing on the 5G rollout and a burgeoning electric vehicle market-evident from the growing EV sales in 2024-integrating features like streaming infotainment for enhanced customer loyalty. Canada is closely following U.S. trends, while the Middle East and Africa see growth concentrated in the UAE and Saudi Arabia. Notably, Turkey and South Africa are gearing up for eCall regulations, promising to amplify connectivity benefits throughout the region.
- Harman International Industries Inc.
- Robert Bosch GmbH
- Continental AG
- Denso Corporation
- Visteon Corporation
- Panasonic Corporation
- Aptiv plc
- Mitsubishi Electric Corporation
- Alpine Electronics Inc.
- JVCKenwood Corporation
- Pioneer Corporation
- Faurecia SE (Clarion Electronics)
- Qualcomm Technologies Inc.
- Nvidia Corporation
- NXP Semiconductors N.V.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Consumer Demand for Connected Services & 5G Roll-out
- 4.2.2 Shift toward Software-Defined Vehicles & Digital Cockpits
- 4.2.3 Integration of ADAS-Centric HMI into Infotainment Head Units
- 4.2.4 Mandatory eCall & Data-Logging Regulations in Emerging Markets
- 4.2.5 Cloud-Native Updates Enabling Feature-on-Demand
- 4.2.6 In-Car E-commerce / App-Store Monetisation
- 4.3 Market Restraints
- 4.3.1 Cost Sensitivity in Entry-Level Models
- 4.3.2 Cyber-security & Liability Risks
- 4.3.3 Automotive SoC Supply-Chain Volatility
- 4.3.4 Right-to-Repair & Data-Ownership Legislation
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Installation Type
- 5.1.1 In-dash Infotainment
- 5.1.2 Rear-seat Infotainment
- 5.2 By Vehicle Type
- 5.2.1 Passenger Cars
- 5.2.2 Light Commercial Vehicles
- 5.2.3 Medium and Heavy Commercial Vehicles
- 5.3 By Component
- 5.3.1 Display / Touch-screen Module
- 5.3.2 Head Unit / Domain Controller
- 5.3.3 Operating-System Software & Apps
- 5.3.4 Connectivity ICs & Antenna Modules
- 5.4 By Propulsion Type
- 5.4.1 Internal-Combustion Engine Vehicles
- 5.4.2 Battery Electric Vehicles
- 5.4.3 Hybrid Electric Vehicles
- 5.5 By Connectivity Generation
- 5.5.1 4G LTE
- 5.5.2 5G
- 5.5.3 Legacy 2G/3G
- 5.6 By Operating System
- 5.6.1 Linux-Based (AAOS, AGL, etc.)
- 5.6.2 QNX
- 5.6.3 Android Automotive OS
- 5.6.4 Others (Proprietary, RTOS)
- 5.7 By Sales Channel
- 5.7.1 OEM-Installed
- 5.7.2 Aftermarket
- 5.8 By Geography
- 5.8.1 North America
- 5.8.1.1 United States
- 5.8.1.2 Canada
- 5.8.1.3 Rest of North America
- 5.8.2 South America
- 5.8.2.1 Brazil
- 5.8.2.2 Argentina
- 5.8.2.3 Rest of South America
- 5.8.3 Europe
- 5.8.3.1 Germany
- 5.8.3.2 United Kingdom
- 5.8.3.3 France
- 5.8.3.4 Italy
- 5.8.3.5 Spain
- 5.8.3.6 Rest of Europe
- 5.8.4 Asia Pacific
- 5.8.4.1 China
- 5.8.4.2 India
- 5.8.4.3 Japan
- 5.8.4.4 South Korea
- 5.8.4.5 Rest of Asia Pacific
- 5.8.5 Middle East and Africa
- 5.8.5.1 United Arab Emirates
- 5.8.5.2 Saudi Arabia
- 5.8.5.3 South Africa
- 5.8.5.4 Turkey
- 5.8.5.5 Rest of Middle East and Africa
- 5.8.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Harman International Industries Inc.
- 6.4.2 Robert Bosch GmbH
- 6.4.3 Continental AG
- 6.4.4 Denso Corporation
- 6.4.5 Visteon Corporation
- 6.4.6 Panasonic Corporation
- 6.4.7 Aptiv plc
- 6.4.8 Mitsubishi Electric Corporation
- 6.4.9 Alpine Electronics Inc.
- 6.4.10 JVCKenwood Corporation
- 6.4.11 Pioneer Corporation
- 6.4.12 Faurecia SE (Clarion Electronics)
- 6.4.13 Qualcomm Technologies Inc.
- 6.4.14 Nvidia Corporation
- 6.4.15 NXP Semiconductors N.V.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

