PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120476

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120476
MEA Plastic Bottles And Containers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Middle East and Africa plastic bottles and containers market size is expected to grow from 1.84 million tonnes in 2025 to 1.9 million tonnes in 2026 and is forecast to reach 2.19 million tonnes by 2031 at 2.99% CAGR over 2026-2031.
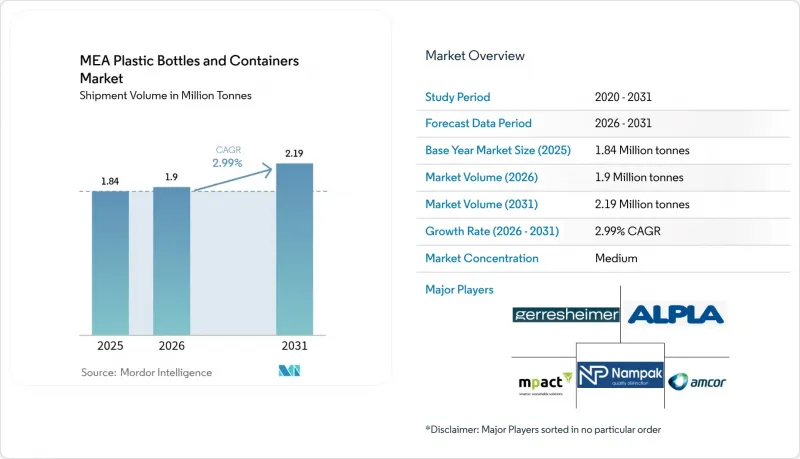
This report is Segmented by Material (PET, HDPE, PP, and More), Packaging Type (Bottles, Jars and Canisters, and More), End-User Industry (Beverages, Food, and More), Manufacturing Technology (Extrusion Blow Moulding, Injection Stretch Blow Moulding, and More). The Market Forecasts are Provided in Terms of Volume (Tonnes).
MEA Plastic Bottles And Containers Market Trends and Insights
Increasing Adoption of Lightweight PET Bottles
Lightweight PET formats appeal to converters seeking margin protection as paraxylene price swings keep resin costs volatile. Saudi regulators endorse PET for sensitive applications because of its chemical inertness, encouraging similar standards across the rest of the GCC. Modern stretch-blow molding machines in UAE plants achieve even wall thickness and consistently hit sub-20-gram targets for 500-milliliter water bottles, cutting freight costs on long cross-desert hauls. Design refinements translate into fewer pallets per million units shipped, directly lowering scope 3 emissions. Carbonated soft-drink lines spearhead adoption because high line speeds amplify each gram saved, while smaller dairy producers in Levant markets move more cautiously due to cap-application torque constraints. Continued equipment upgrades suggest a medium-term payoff as brand owners integrate downstream refill programs that lean on robust bottle integrity over multiple life cycles.
Surge in Packaged-Water and Soft-Drink Demand Across GCC
Per-capita water consumption in the Gulf often exceeds 500 liters daily, a figure linked to triple-digit heat indices and desalinated supply ubiquity. UAE retailers report double-digit unit sales growth of 200-milliliter PET bottles catering to tourist demand during peak travel months. Soft-drink bottlers capitalize on year-round refrigeration penetration, positioning single-serve carbonated drinks at service-station forecourts frequented by long-haul drivers moving between economic zones. Despite network upgrades that cut non-revenue water losses to 4.6%, many consumers still favor branded bottles because of taste consistency and mineral add-backs. Harmonized Gulf standards for food-contact plastics reduce border checks, enabling pan-GCC supply chains that leverage shared production hubs in Jebel Ali and Dammam.
Intensifying Anti-Plastic Legislation and Consumer Backlash
UAE will enact a comprehensive single-use plastic ban in 2026, forcing restaurants to pivot toward fiber-based cups and aluminum cans. Oman and Ethiopia have similar measures scheduled for 2025, compressing the compliance horizon for import-heavy SMEs. Surveys show 92% of UAE shoppers are prepared to pay more for eco-friendly packaging, up four points from 2023, intensifying brand-reputation risks for laggards. Regional fast-food chains fast-track pilot programs with molded-pulp cold-drink cups in anticipation of rule extensions. Distributors managing multi-country portfolios struggle with differing phase-out calendars, complicating inventory management and costing models.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Push for Food-Grade rPET in Saudi Arabia and UAE
- Solar-Desalination Boom Driving Bulk-Water Container Uptake
- Volatile Crude-Linked Resin Pricing
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PET accounts for 50.90% of the Middle East and Africa plastic bottles and containers market share in 2025, underscoring its compatibility with beverage carbonation pressures and desert-climate temperature swings. The polymer's clarity and cost efficiency keep it the default for branded water, soft drinks, and many edible-oil formats. Bioplastics, though just a niche, are forecast to grow at 4.78% as pharmaceutical buyers respond to both patient-safety and carbon-footprint metrics. UPM's wood-based bottle project with Bormioli Pharma shows potential for drop-in solutions requiring only minor line adjustments.
The Middle East and Africa plastic bottles and containers market benefits from HDPE's chemical resilience, making it indispensable for jerrycans transporting lubricants and cleaning fluids. LDPE retains relevance for squeeze bottles found in condiment aisles, while polypropylene's thermal resistance suits autoclave-sterilized ampoules. Specialty resins such as PEN serve ultra-high-barrier medical nutrition products. As recycling streams mature, converters will likely blend rPET with virgin to meet mandatory content thresholds while retaining mechanical strength, protecting brand owners from feedstock price shocks.
Bottles captured 48.12% of adoption in 2025, illustrating the format's universality across consumer beverages, cooking oils, and personal-care refills. Their straightforward geometry aligns with high-speed filling lines, allowing operators to pivot SKUs without extensive tooling revisions. Ampoules and vials, by contrast, are poised for a 4.62% CAGR as governments court pharmaceutical contract manufacturing through tax holidays and export incentives. Gerresheimer's expanded vial lines in Italy will funnel capacity into emerging Gulf injectable-drug hubs, reinforcing supply reliability.
The Middle East and Africa plastic bottles and containers market finds growth levers in jars for premium skin-care creams and in canisters for powdered nutrition. Jerrycans keep a foothold in rural fertilizer distribution, where gravitational dispensing is favored over pumps. Custom dropper and spray formats, though low in tonnage, command notable margins due to child-resistance requirements and tamper-evident features.
Complete Report Scope:
- By Material
- Polyethylene Terephthalate (PET)
- High-Density Polyethylene (HDPE)
- Polypropylene (PP)
- Low-Density Polyethylene (LDPE)
- Bioplastics
- Other Plastics
- By Packaging Type
- Bottles
- Jars and Canisters
- Jerrycans
- Ampoules and Vials
- Other Packaging Types
- By End-user Industry
- Beverages
- Non-Alcoholic Beverages
- Bottled Water
- Carbonated Soft Drinks
- Dairy and Functional Drinks
- Other Non-Alcoholic Beverages
- Alcoholic Beverages
- Non-Alcoholic Beverages
- Food
- Pharmaceuticals
- Cosmetics and Personal Care
- Industrial Chemicals
- Other End-user Industries
- Beverages
- By Manufacturing Technology
- Extrusion Blow Moulding
- Injection Stretch Blow Moulding
- Injection Blow Moulding
- Compression Blow Moulding
- Other Manufacturing Technologies
- By Geography
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Kenya
- Rest of Africa
- Middle East
List of Companies Covered in this Report:
- Amcor plc
- ALPLA Werke Alwin Lehner GmbH & Co KG
- Nampak Ltd
- Gerresheimer AG
- Mpact Ltd
- Plastipak Holdings, Inc.
- Silgan Holdings Inc.
- SABIC - Saudi Basic Industries Corporation
- Indorama Ventures Public Co. Ltd.
- Graham Packaging Company, L.P.
- Resilux NV
- Alpha Packaging Inc.
- Packnet SA
- Emirates Plastic Industries Factory LLC
- Takween Advanced Industries Co.
- Al Amana Plastic LLC
- Huhtamaki Oyj
- Sonoco Products Company
- Origin Materials, Inc.
- Sidel (Part of Tetra Laval)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing adoption of lightweight PET bottles
- 4.2.2 Surge in packaged-water and soft-drink demand across GCC
- 4.2.3 Regulatory push for food-grade rPET in Saudi Arabia and United Arab Emirates
- 4.2.4 Solar-desalination boom driving bulk-water container uptake
- 4.2.5 E-commerce refill-and-delivery models scaling returnable PET
- 4.3 Market Restraints
- 4.3.1 Intensifying anti-plastic legislation and consumer backlash
- 4.3.2 Volatile crude-linked resin pricing
- 4.3.3 rPET supply-quality gap throttling food-grade output
- 4.3.4 Water-scarcity policies discouraging single-use formats
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Intensity of Competitive Rivalry
- 4.7.5 Threat of Substitutes
- 4.8 The Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VOLUME)
- 5.1 By Material
- 5.1.1 Polyethylene Terephthalate (PET)
- 5.1.2 High-Density Polyethylene (HDPE)
- 5.1.3 Polypropylene (PP)
- 5.1.4 Low-Density Polyethylene (LDPE)
- 5.1.5 Bioplastics
- 5.1.6 Other Plastics
- 5.2 By Packaging Type
- 5.2.1 Bottles
- 5.2.2 Jars and Canisters
- 5.2.3 Jerrycans
- 5.2.4 Ampoules and Vials
- 5.2.5 Other Packaging Types
- 5.3 By End-user Industry
- 5.3.1 Beverages
- 5.3.1.1 Non-Alcoholic Beverages
- 5.3.1.1.1 Bottled Water
- 5.3.1.1.2 Carbonated Soft Drinks
- 5.3.1.1.3 Dairy and Functional Drinks
- 5.3.1.1.4 Other Non-Alcoholic Beverages
- 5.3.1.2 Alcoholic Beverages
- 5.3.1.1 Non-Alcoholic Beverages
- 5.3.2 Food
- 5.3.3 Pharmaceuticals
- 5.3.4 Cosmetics and Personal Care
- 5.3.5 Industrial Chemicals
- 5.3.6 Other End-user Industries
- 5.3.1 Beverages
- 5.4 By Manufacturing Technology
- 5.4.1 Extrusion Blow Moulding
- 5.4.2 Injection Stretch Blow Moulding
- 5.4.3 Injection Blow Moulding
- 5.4.4 Compression Blow Moulding
- 5.4.5 Other Manufacturing Technologies
- 5.5 By Geography
- 5.5.1 Middle East
- 5.5.1.1 Saudi Arabia
- 5.5.1.2 United Arab Emirates
- 5.5.1.3 Turkey
- 5.5.1.4 Rest of Middle East
- 5.5.2 Africa
- 5.5.2.1 South Africa
- 5.5.2.2 Kenya
- 5.5.2.3 Rest of Africa
- 5.5.1 Middle East
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-Level Overview, Market-Level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 ALPLA Werke Alwin Lehner GmbH & Co KG
- 6.4.3 Nampak Ltd
- 6.4.4 Gerresheimer AG
- 6.4.5 Mpact Ltd
- 6.4.6 Plastipak Holdings, Inc.
- 6.4.7 Silgan Holdings Inc.
- 6.4.8 SABIC - Saudi Basic Industries Corporation
- 6.4.9 Indorama Ventures Public Co. Ltd.
- 6.4.10 Graham Packaging Company, L.P.
- 6.4.11 Resilux NV
- 6.4.12 Alpha Packaging Inc.
- 6.4.13 Packnet SA
- 6.4.14 Emirates Plastic Industries Factory LLC
- 6.4.15 Takween Advanced Industries Co.
- 6.4.16 Al Amana Plastic LLC
- 6.4.17 Huhtamaki Oyj
- 6.4.18 Sonoco Products Company
- 6.4.19 Origin Materials, Inc.
- 6.4.20 Sidel (Part of Tetra Laval)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

