PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120512

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120512
Explosion Proof Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the explosion proof equipment market size reached USD 10.57 billion in 2026 and is forecast to climb to USD 14.14 billion by 2031, reflecting a 5.99% CAGR across the period.
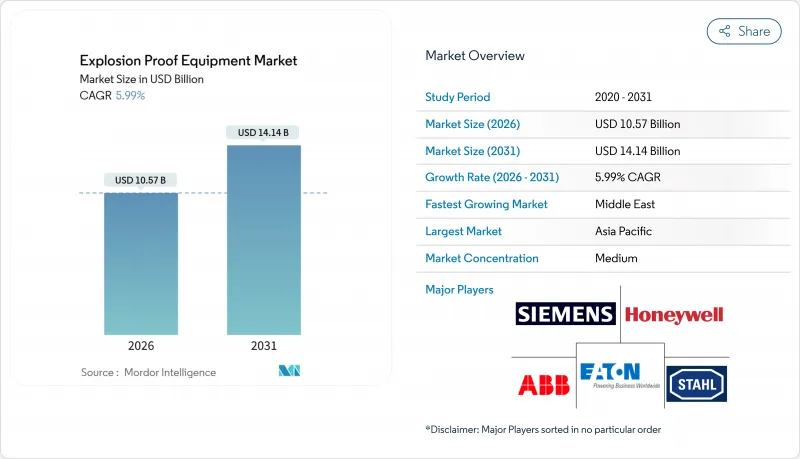
This report is Segmented by Method of Protection (Containment, Intrinsic Safety, Pressurization, and More), Zone (Zone 0, Zone 1, and More), End-User (Oil and Gas, Chemicals, Mining, Energy, and More), System (Power, Motors, Automation, and More), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Explosion Proof Equipment Market Trends and Insights
Stricter Global ATEX/IECEx Enforcement
Mutual recognition of IECEx test reports rose from 28 to 38 member states between 2024 and 2026, cutting duplicate type-testing times by roughly 50% and forcing non-compliant legacy gear out of service. The European Union closed a self-certification loophole in the revised ATEX Directive, obliging third-party audits for all Group II assemblies, and fines above EUR 500,000 (USD 565,000) were issued in Germany and France during 2025. TUV Sud and Intertek logged a 22% surge in audit requests as OEMs scrambled to comply before customs blocks took effect. Gulf-region operators aligned procurement with IECEx to avoid port delays, pushing certified demand far beyond historical oil and gas orders. Collectively, these moves lift the baseline CAGR by an estimated 0.9 percentage points.
Rising Green-Hydrogen Projects Needing Class I Equipment
Cumulative electrolyzer capacity reached 3.2 GW by 2025, with another 12 GW under execution, and each stack requires Class I, Division 1 junction boxes, compressors and gas detection loops. California's Hydrogen Safety Panel capped allowable hydrogen concentration at 1%, effectively mandating SIL 2 trip logic and intrinsically safe signal loops. Jafurah Phase 2 alone allocated roughly USD 1 billion for Ex-rated electrical scope in 2024 procurement rounds. TUV-certified turbines capable of 100% hydrogen now ship with flame-proof ignition systems, broadening adoption in peaker plants and chemical off-gas recovery lines. As export-scale hydrogen terminals start in 2028, the driver is expected to add 1.2 percentage points to the forecast CAGR.
High Certification and Recertification Cost
Obtaining Ex certificates typically costs USD 50,000-150,000 per product family, and any design tweak triggers an additional USD 20,000-40,000 plus a 3-6 month delay. Intertek's 2024 report notes project durations lengthened to 19 weeks as IIoT devices required cybersecurity evidence under IEC 62443-4-2. Niche suppliers therefore skip secondary markets, fragmenting the explosion proof equipment market and depressing economies of scale. End-users see higher spares prices because OEMs must amortize compliance cost across thin volumes, subtracting roughly 0.6 percentage points from growth.
Other drivers and restraints analyzed in the detailed report include:
- IIoT-Ready Explosion-Proof Retrofits
- Rapid LED Migration in Hazardous Lighting
- Divergent Regional Zoning Standards
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Intrinsic safety claimed 34.17% of the explosion proof equipment market in 2025 and is projected to grow at 6.19% through 2031, outpacing pressurization, explosion containment and other legacy approaches. The shift lowers enclosure mass and eliminates machined flame paths, reducing both upfront material and lifecycle maintenance costs. ABB's AC500-S PLC family embeds intrinsic outputs that negate separate barrier racks, freeing 25% of cabinet footprint. Emerson's SIL 3 safety controller connects directly to HART loops in Zone 1 areas, preserving wiring and enabling hot-cutovers without production downtime. Variable-frequency drives continue to require flame-proof housings, yet semiconductor advances that distribute heat are narrowing the power levels where containment is essential. Pressurization systems remain the method of choice in analyzer shelters, although purge-air loss alarms and interlocks add complexity. Explosion proof equipment market size for intrinsic safety reached USD 3.6 billion in 2026 and is foreseen to exceed USD 4.9 billion by 2031. Smaller machine builders appreciate the ability to certify once and roll platforms across voltages and regions, reinforcing long-term preference for energy-limiting protection.
While containment retains relevance for 600 V switchgear and 250 kW motors, its share continues to erode. OEMs now cast modular flame-proof housings that accept drive, starter or disconnect inserts to amortize testing fees, but even these platforms face stiff competition from intrinsic fieldbus architectures. Sand-filled and oil-immersed techniques find support in underground mining transformers, yet high oil prices make double-walled tanks expensive, steering miners toward compact intrinsic telemetry. Explosion proof equipment market share for pressurization is forecast to dip below 12% by 2031 as predictive-maintenance programs value the safer live-work privileges intrinsic circuits provide. The transition is already visible in procurement specifications that rank intrinsic safety ahead of containment whenever loop power stays below 30 V.
Zone 1 still dominates in absolute terms, representing 41.53% of installed devices in 2025, yet combustible-dust areas are expanding faster due to giga-factory and pharmaceutical powder lines. Explosion proof equipment market size for Zone 20 and Zone 21 combined crossed USD 1.8 billion in 2026 and is projected to reach USD 2.7 billion by 2031. Lithium-ion cathode mixing, graphite anode processing and solvent recovery systems present hybrid dust-and-vapor risks that demand IP6X enclosures with elevated temperature codes. Regulators in the United States cited 47 facilities in 2025 for dust violations, prompting immediate retrofits of conveyors and bucket elevators.
OEMs respond with dual-certified products that serve both gas and dust hazards, reducing inventory burden for distributors. Eaton's CEAG switches and BARTEC's Zone 20 luminaires exemplify this trend, each carrying IP66/IP67 ingress ratings to resist cleaning fluids while blocking fine powders. Municipal wastewater plants, long considered moderate-risk, are upgrading blower rooms to Zone 1 to accommodate rising methane concentrations from co-digestion. Meanwhile, Zone 0 remains niche outside electrolyzer cathode chambers and storage tank sumps, but unit values are high because only intrinsically safe apparatus is admissible. The explosion proof equipment market maintains a cost premium of 30%-50% in Zone 0 compared with Zone 2, contributing outsized revenue from a limited installed base.
Complete Report Scope:
- By Method of Protection
- Explosion Containment (Flame-Proof)
- Intrinsic Safety
- Pressurization / Purged
- Explosion Prevention
- Explosion Segregation
- By Zone
- Zone 0
- Zone 1
- Zone 2
- Zone 20
- Zone 21
- Zone 22
- By End-User Industry
- Oil and Gas
- Chemicals and Petrochemicals
- Mining and Metals
- Energy and Power
- Pharmaceuticals
- Food and Beverage Processing
- Waste-Water Treatment
- Hydrogen Production and Fuel Cells
- Other End-User Industries
- By System
- Power Supply and Distribution
- Motors and Drives
- Automation and Control Systems
- Lighting Systems
- Material Handling Equipment
- Surveillance and Detection
- Heating and HVAC
- Other Systems
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Australia and New Zealand
- Rest of Asia Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia Pacific retained the largest share at 32.71% in 2025 owing to refinery and petrochemical build-outs across China, India, and Southeast Asia. China commissioned eight ethylene crackers in 2024, each ordering up to 3,000 Ex devices, while India's coastal investment zones are committing more than USD 100 billion to integrated complexes. Japan's ammonia co-firing retrofits require Class I equipment to manage the 15%-28% flammability window of ammonia, and South Korea is adding blue-hydrogen loops in existing refineries.
North America accounted for roughly 28% of 2025 revenue, as U.S. Gulf Coast steam crackers, LNG terminals, and hydrogen hubs secured orders following the DOE's USD 7 billion in grants. Canadian oil-sands operators continue to replace aging Class I motors with higher-efficiency Ex e units featuring corrosion-resistant coatings for saline tailings ponds. Mexico benefits indirectly by assembling flameproof enclosures to bypass anti-dumping tariffs on Chinese castings and by shipping finished goods duty-free into the United States.
The Middle East is forecast to post the fastest 8.27% CAGR through 2031, powered by Jafurah, Ruwais and Yasref mega-projects that bundle Ex electrical packages into multi-billion-dollar EPC contracts. Hydrogen, ammonia and methanol export terminals along the Persian Gulf demand SIL 3 shutdown systems, fiber-optic marshaling panels and thousands of Zone 0 gas detectors. Europe holds roughly 24% share, yet growth is constrained by energy-price uncertainty; still, BASF, Shell and TotalEnergies are digitizing historic complexes with intrinsic wireless sensors. Latin America and Africa remain smaller, but pre-salt fields and new refineries in Brazil, Nigeria and Angola offer episodic upside when financing aligns.
- ABB Ltd.
- Eaton Corporation plc
- Siemens AG
- Honeywell International Inc.
- R. STAHL AG
- Pepperl+Fuchs GmbH
- Emerson Electric Co.
- Bartec GmbH
- Rockwell Automation Inc.
- Intertek Group plc
- Marechal Electric Group
- Adalet Inc.
- CZ Electric Co. Ltd.
- MAM Explosion-Proof Technology (Shanghai) Co. Ltd.
- G.M. International SRL
- Alloy Industry Co. Ltd.
- Hawke International
- Cooper Crouse-Hinds (Eaton)
- WEG Industries
- Advantech Co. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stricter Global ATEX/IECEx Enforcement
- 4.2.2 Rising Green-Hydrogen Projects Needing Class I Equipment
- 4.2.3 IIoT-Ready Explosion-Proof Retrofits
- 4.2.4 Rapid LED Migration in Hazardous Lighting
- 4.2.5 Lithium-Ion Gigafactories Demand for Dust-Zone Gear
- 4.2.6 Space-Industry Test Stands Requiring Ex-Rated Systems
- 4.3 Market Restraints
- 4.3.1 High Certification and Recertification Cost
- 4.3.2 Divergent Regional Zoning Standards
- 4.3.3 Supply-Chain Delays for Flame-Proof Castings
- 4.3.4 Anti-Dumping Tariffs on Chinese Ex Enclosures
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Method of Protection
- 5.1.1 Explosion Containment (Flame-Proof)
- 5.1.2 Intrinsic Safety
- 5.1.3 Pressurization / Purged
- 5.1.4 Explosion Prevention
- 5.1.5 Explosion Segregation
- 5.2 By Zone
- 5.2.1 Zone 0
- 5.2.2 Zone 1
- 5.2.3 Zone 2
- 5.2.4 Zone 20
- 5.2.5 Zone 21
- 5.2.6 Zone 22
- 5.3 By End-User Industry
- 5.3.1 Oil and Gas
- 5.3.2 Chemicals and Petrochemicals
- 5.3.3 Mining and Metals
- 5.3.4 Energy and Power
- 5.3.5 Pharmaceuticals
- 5.3.6 Food and Beverage Processing
- 5.3.7 Waste-Water Treatment
- 5.3.8 Hydrogen Production and Fuel Cells
- 5.3.9 Other End-User Industries
- 5.4 By System
- 5.4.1 Power Supply and Distribution
- 5.4.2 Motors and Drives
- 5.4.3 Automation and Control Systems
- 5.4.4 Lighting Systems
- 5.4.5 Material Handling Equipment
- 5.4.6 Surveillance and Detection
- 5.4.7 Heating and HVAC
- 5.4.8 Other Systems
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN
- 5.5.3.6 Australia and New Zealand
- 5.5.3.7 Rest of Asia Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Eaton Corporation plc
- 6.4.3 Siemens AG
- 6.4.4 Honeywell International Inc.
- 6.4.5 R. STAHL AG
- 6.4.6 Pepperl+Fuchs GmbH
- 6.4.7 Emerson Electric Co.
- 6.4.8 Bartec GmbH
- 6.4.9 Rockwell Automation Inc.
- 6.4.10 Intertek Group plc
- 6.4.11 Marechal Electric Group
- 6.4.12 Adalet Inc.
- 6.4.13 CZ Electric Co. Ltd.
- 6.4.14 MAM Explosion-Proof Technology (Shanghai) Co. Ltd.
- 6.4.15 G.M. International SRL
- 6.4.16 Alloy Industry Co. Ltd.
- 6.4.17 Hawke International
- 6.4.18 Cooper Crouse-Hinds (Eaton)
- 6.4.19 WEG Industries
- 6.4.20 Advantech Co. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet Needs Assessment

