PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154967

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154967
South America Explosion Proof Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
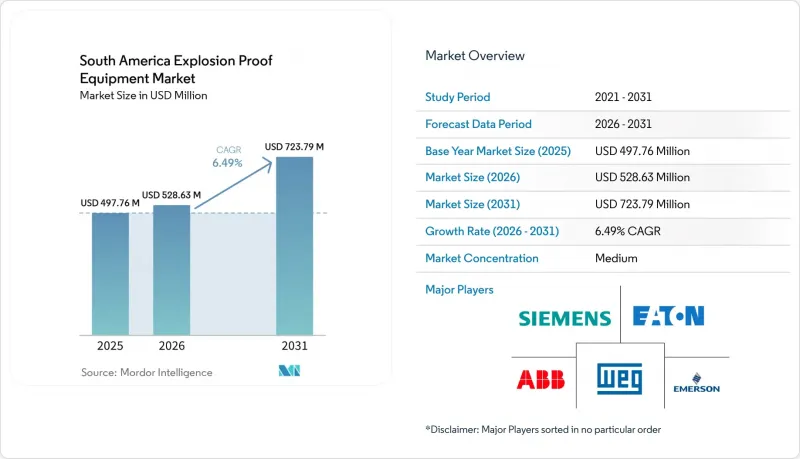
According to Mordor Intelligence, the South America explosion proof equipment market was valued at USD 497.8 million in 2025 and is estimated to grow from USD 528.6 million in 2026 to USD 723.8 million by 2031, at a CAGR of 6.5% during the forecast period (2026-2031).
South America Explosion Proof Equipment Market Trends and Insights
Expansion of Brazil Offshore Oil and Gas and Refining Infrastructure
Petrobras's 2026-2030 business plan allocates USD 69.2 billion to exploration and production and includes 8 new production systems, 11 Buzios FPSOs, refinery expansion plans, and a strategy that keeps offshore production and related processing assets at the center of its capital program. These developments require certified motors, cable glands, junction boxes, lighting, automation equipment, field instrumentation, and supporting electrical infrastructure in classified locations, with specifications often set before construction begins. The May 2026 contracts between Petrobras and SBM Offshore for 2 SEAP FPSOs represent investments exceeding BRL 60 billion, or USD 11.9 billion, and extend equipment specification activities over several years, from engineering through commissioning. Each FPSO creates demand across equipment supply, installation, inspection, replacement work, documentation, and the ongoing maintenance programs required after it enters operation. Existing offshore assets also require equipment replacement during field extension and maintenance programs, particularly where components must remain suitable for the designated hazardous-area classification. This combination of new construction and installed-base work supports a longer procurement cycle for the South America explosion-proof equipment market and provides qualified suppliers opportunities across both original equipment and aftermarket activities.
Expansion of Copper, Iron Ore, Lithium, and Gold Mining
Mining sites require equipment suitable for combustible dust and hazardous operating conditions in crushing, conveying, drilling, mineral processing, pumping, and material transfer activities. Dust can occur in underground works, ore-handling circuits, enclosed processing areas, and storage points, thereby broadening the use of hazardous-area equipment beyond oil and gas facilities. The South America explosion-proof equipment market, therefore, has exposure to mining projects that require reliable electrical distribution, motors, lighting, monitoring systems, cable connections, and enclosures that meet demanding site conditions. Equipment selection depends on the zone classification, dust characteristics, temperature requirements, installation conditions, maintenance access, and the need to protect personnel and plant assets. Remote mining operations also place greater value on durable products, spare parts availability, and local maintenance support because extended downtime can disrupt essential processing tasks. These operating conditions make certified equipment an integral part of the site design, commissioning, maintenance, and replacement processes rather than a stand-alone purchase.
High Certification and Lifecycle Compliance Costs
Certification costs can be significant because equipment approval may involve testing, factory assessment, surveillance, certificate renewal, technical records, and ongoing evidence that product specifications remain compliant. Brazil's regulatory framework can create additional work for suppliers that already hold IECEx or ATEX approvals. ABENDI reported that more than 280 Brazilian professionals held IECEx Certified Persons competence certificates by December 2025. The available qualified workforce remains limited relative to the training, inspection, installation, and maintenance needs of hazardous-area installations. Smaller operators can delay upgrades when certification and training costs rise or when compliance work competes with other capital priorities. These costs can limit addressable demand in the South America explosion proof equipment market, particularly for smaller projects with limited procurement budgets and limited access to specialist engineering resources.
Other drivers and restraints analyzed in the detailed report include:
- Stricter Hazardous-Area Compliance and Certification Enforcement
- Industrial Automation and IIoT Retrofit Adoption
- High Upfront Cost for Certified Equipment and Engineering
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Explosion Prevention held 42.9% of the South America explosion proof equipment market share in 2025 and is expected to grow at a 8% CAGR through 2031. The category includes increased safety, non-sparking, and encapsulation approaches that operators select when they seek a suitable balance of protection, equipment weight, maintenance access, and installation practicality. It is relevant to offshore installations where equipment layout, available space, and the weight of installed systems affect project design and maintenance planning. The South America explosion proof equipment market size for this method also reflects the need to match the protection approach to the type of hazard, the equipment function, and the conditions at the operating location. ABENDI noted ongoing development of Brazilian explosive-atmosphere standards and maintenance practices during 2025, reinforcing the importance of appropriate selection and documented inspection.
Flameproof equipment remains important in oil and gas wellhead and process areas where robust ignition containment is required, while intrinsic safety is widely applicable to instrumentation and sensor circuits in gas-hazard locations. Pressurization and purging are suited to larger control enclosures and analyzers where replacing each individual component may not be practical or may require extensive changes to installed systems. Physical separation measures, such as barriers and blast walls, address applications where equipment layout and separation are central to risk control. Suppliers must maintain a broad protection portfolio because no single method fits every process, location, maintenance arrangement, or hazard classification. This requirement keeps product selection closely linked to site-specific engineering, inspection, installation, and maintenance practices.
Zone 1 represented 37.8% of regional value in 2025. This zone is associated with locations where flammable gas may be present during normal operations, including offshore platforms, refinery units, receiving terminals, and other hydrocarbon-processing assets. Brazil's offshore assets form a substantial installed base for Zone 1 equipment because upstream operations require extensive electrical, instrumentation, detection, and communications systems. Equipment replacement can remain necessary as mature assets undergo maintenance and life-extension work, and the South America explosion proof equipment market supports these needs through motors, lighting, enclosures, glands, controls, and detection equipment. Petrobras's planned exploration, production, and refining investments maintain the importance of these applications.
Zone 20 is forecast to advance at a 7.8% CAGR through 2031, making it the fastest-growing zone classification in the supplied estimates. It applies to locations where combustible dust clouds are continuously present or present for long periods, including enclosed grain, sugar, biofuels, mining, and other material-handling processes. Zones 2 and 22 cover a broad range of applications where hazardous gas or dust is less likely to be continuously present, while Zones 0 and 21 remain important for narrower applications that require protection against continuous-presence hazards. This spread of zone classifications requires suppliers to provide equipment that is appropriate for the operating environment, hazard profile, inspection regime, and practical installation conditions. It also means that a facility may require several protection solutions rather than a single equipment design across all areas.
Complete Report Scope:
- By Method of Protection
- Explosion Containment (Flame-Proof)
- Intrinsic Safety
- Pressurization / Purged
- Explosion Prevention
- Explosion Segregation
- By Zone
- Zone 0
- Zone 1
- Zone 2
- Zone 20
- Zone 21
- Zone 22
- By End-User Industry
- Oil and Gas
- Chemicals and Petrochemicals
- Mining and Metals
- Energy and Power
- Pharmaceuticals
- Food and Beverage Processing
- Wastewater Treatment
- Hydrogen Production and Fuel Cells
- Other End-User Industries
- By System
- Power Supply and Distribution
- Motors and Drives
- Automation and Control Systems
- Lighting Systems
- Material Handling Equipment
- Surveillance and Detection
- Heating and HVAC
- Other Systems
- By Country
- Brazil
- Argentina
- Chile
- Colombia
- Peru
- Rest of South America
List of Companies Covered in this Report:
- WEG S.A.
- ABB Ltd.
- Siemens AG
- Eaton Corporation plc
- Emerson Electric Co.
- Pepperl+Fuchs SE
- R. STAHL AG
- BARTEC Top Holding GmbH
- Honeywell International Inc.
- Rockwell Automation, Inc.
- Schneider Electric SE
- Marechal Electric Group
- G.M. International SRL
- Warom Technology Incorporated Company
- Hawke International
- Kohlbach Motores e Equipamentos Eletricos Ltda.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Brazil Offshore Oil and Gas and Refining Infrastructure
- 4.2.2 Expansion of Copper, Iron Ore, Lithium and Gold Mining
- 4.2.3 Stricter Hazardous-Area Compliance and Certification Enforcement
- 4.2.4 Industrial Automation and IIoT Retrofit Adoption
- 4.2.5 Aging Installed-Base Replacement Across Process Industries
- 4.2.6 Dust-Zone Safety Upgrades in Grain, Sugar and Biofuels Processing
- 4.3 Market Restraints
- 4.3.1 High Certification and Lifecycle Compliance Costs
- 4.3.2 High Upfront Cost for Certified Equipment and Engineering
- 4.3.3 Fragmented National Acceptance of Ex Standards
- 4.3.4 Currency Volatility, Import Delays and Specialist Shortages
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Method of Protection
- 5.1.1 Explosion Containment (Flame-Proof)
- 5.1.2 Intrinsic Safety
- 5.1.3 Pressurization / Purged
- 5.1.4 Explosion Prevention
- 5.1.5 Explosion Segregation
- 5.2 By Zone
- 5.2.1 Zone 0
- 5.2.2 Zone 1
- 5.2.3 Zone 2
- 5.2.4 Zone 20
- 5.2.5 Zone 21
- 5.2.6 Zone 22
- 5.3 By End-User Industry
- 5.3.1 Oil and Gas
- 5.3.2 Chemicals and Petrochemicals
- 5.3.3 Mining and Metals
- 5.3.4 Energy and Power
- 5.3.5 Pharmaceuticals
- 5.3.6 Food and Beverage Processing
- 5.3.7 Wastewater Treatment
- 5.3.8 Hydrogen Production and Fuel Cells
- 5.3.9 Other End-User Industries
- 5.4 By System
- 5.4.1 Power Supply and Distribution
- 5.4.2 Motors and Drives
- 5.4.3 Automation and Control Systems
- 5.4.4 Lighting Systems
- 5.4.5 Material Handling Equipment
- 5.4.6 Surveillance and Detection
- 5.4.7 Heating and HVAC
- 5.4.8 Other Systems
- 5.5 By Country
- 5.5.1 Brazil
- 5.5.2 Argentina
- 5.5.3 Chile
- 5.5.4 Colombia
- 5.5.5 Peru
- 5.5.6 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 WEG S.A.
- 6.4.2 ABB Ltd.
- 6.4.3 Siemens AG
- 6.4.4 Eaton Corporation plc
- 6.4.5 Emerson Electric Co.
- 6.4.6 Pepperl+Fuchs SE
- 6.4.7 R. STAHL AG
- 6.4.8 BARTEC Top Holding GmbH
- 6.4.9 Honeywell International Inc.
- 6.4.10 Rockwell Automation, Inc.
- 6.4.11 Schneider Electric SE
- 6.4.12 Marechal Electric Group
- 6.4.13 G.M. International SRL
- 6.4.14 Warom Technology Incorporated Company
- 6.4.15 Hawke International
- 6.4.16 Kohlbach Motores e Equipamentos Eletricos Ltda.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

