PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122040

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122040
United States Ophthalmic Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the United States ophthalmic devices market size is projected to be USD 16.65 billion in 2025, USD 17.63 billion in 2026, and reach USD 24.11 billion by 2031, growing at a CAGR of 6.46% from 2026 to 2031.
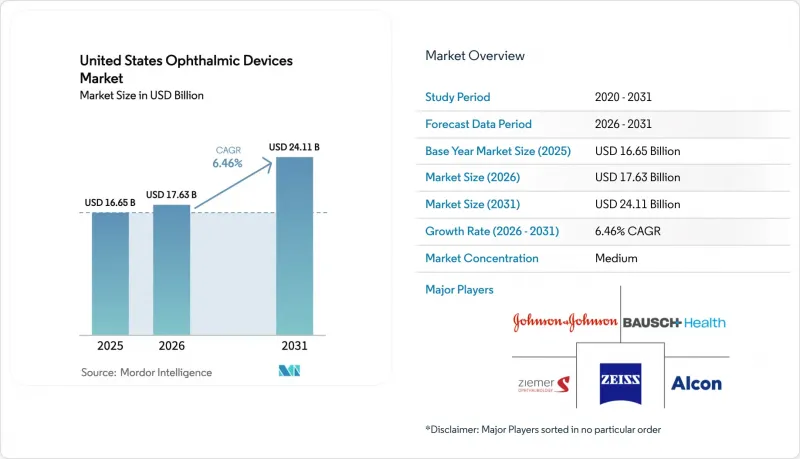
This report is Segmented by Device Type (Diagnostic & Monitoring Devices, Surgical Devices, and Vision Care Devices), Disease Indication (Cataract, Glaucoma, Diabetic Retinopathy, Other Disease Indications), End-User (Hospitals, Specialty Ophthalmic Clinics, and More). The Market Forecasts are Provided in Terms of Value (USD).
United States Ophthalmic Devices Market Trends and Insights
Aging Population & Cataract Prevalence Surge
The U.S. Census Bureau expects the 65-plus cohort to reach 73 million by 2030, up from 58 million in 2022. Cataract formation accelerates after age 60, and the National Eye Institute projects 50 million Americans could have cataracts by 2050. Medicare covers standard monofocal cataract extraction, ensuring broad access, while premium IOL penetration rose to 35% of procedures in 2024, according to JAMA Ophthalmology. Sun Belt states attract retiring patients and record-high volumes, prompting vendors to open regional service hubs to minimize downtime.
Rising Diabetes & Glaucoma Comorbidity Burden
The CDC counted 38.4 million Americans with diabetes in 2024, and roughly a quarter will develop diabetic retinopathy within 15 years of diagnosis. Glaucoma Research Foundation data indicate 3.3 million Americans aged 40 and older have glaucoma, expected to reach 4.3 million by 2030. Diabetic patients face a 40% higher risk of open-angle glaucoma, prompting demand for integrated platforms that identify both conditions in one visit. Autonomous AI systems such as IDx-DR extend screening into primary-care offices, easing rural capacity gaps.
High Capital Cost of Femtosecond & OCT Platforms
Acquiring a femtosecond laser requires USD 500,000-750,000, with annual service fees of USD 50,000-100,000. Independent practices rarely reach the 300-case threshold needed to justify these expenses. Advanced multimodal OCT units cost more than USD 150,000, prompting rural clinics to defer upgrades. Leasing and click-fee programs shift risk to vendors, tightening their profit margins.
Other drivers and restraints analyzed in the detailed report include:
- Shift of Cataract & MIGS Procedures to ASCs
- Surge in Premium IOL & Daily-Disposable Contact Lens Uptake
- Reimbursement Uncertainty for Emerging MIGS & AI Diagnostics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Vision care devices accounted for 63.27% of revenue in 2025, underpinned by the vast base of spectacle and contact lens users. Diagnostic and monitoring equipment is on track for a 7.32% CAGR through 2031 as AI platforms migrate into primary care settings. Spectacle lenses, especially EssilorLuxottica's Stellest for myopia control, continue to drive high unit demand. Daily-disposable contact lenses continue to outpace monthly formats, driven by convenience and perceived hygiene. Surgical devices remain vital for cataract, vitreoretinal, refractive, and glaucoma care. Premium IOLs bundled with advanced phacoemulsification consoles deepen vendor-ASC relationships, while MIGS and sustained-release glaucoma implants open new therapy classes.
A broad installed base of phaco consoles means replacement cycles create stable revenue, but the commoditization of consumables tightens margins. Diagnostic players are differentiating through cloud connectivity and AI-based analytics. The CIRRUS 6000 OCT illustrates this shift, automatically segmenting retinal layers to flag early change and reducing technician variability. Fundus cameras coupled with EyeArt AI extend reliable screening to retail and federally qualified clinics. Collectively, these trends reinforce growth in the United States ophthalmic devices market even as vision-care dominance persists.
Complete Report Scope:
- By Device Type
- Diagnostic & Monitoring Devices
- OCT Scanners
- Fundus & Retinal Cameras
- Autorefractors & Keratometers
- Corneal Topography Systems
- Ultrasound Imaging Systems
- Perimeters & Tonometers
- Other Diagnostic & Monitoring Devices
- Surgical Devices
- Cataract Surgical Devices
- Vitreoretinal Surgical Devices
- Refreactive Surgical Devices
- Glaucoma Surgical Devices
- Other Surgical Devices
- Vision Care Devices
- Spectacles Frames & Lenses
- Contact Lenses
- Diagnostic & Monitoring Devices
- By Disease Indication
- Cataract
- Glaucoma
- Diabetic Retinopathy
- Other Disease Indications
- By End-user
- Hospitals
- Specialty Ophthalmic Clinics
- Ambulatory Surgery Centers (ASCs)
- Other End-users
List of Companies Covered in this Report:
- Alcon
- Bausch + Lomb Corp.
- Carl Zeiss
- CooperVision Inc.
- EssilorLuxottica
- Glaukos Corp.
- Heidelberg Engineering
- Hoya Corp.
- Johnson & Johnson
- Lensar Inc.
- Lumenis
- Nidek
- Topcon Corp.
- Ziemer Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging Population & Cataract Prevalence Surge
- 4.2.2 Rising Diabetes & Glaucoma Comorbidity Burden
- 4.2.3 Shift of Cataract & MIGS Procedures to ASCS
- 4.2.4 Surge in Premium IOL & Daily-Disposable Contact Lens Uptake
- 4.2.5 AI-Integrated OCT & Fundus Imaging Adoption
- 4.2.6 Sustainability Push for Single-Use Surgical Packs
- 4.3 Market Restraints
- 4.3.1 High Capital Cost of Femtosecond & OCT Platforms
- 4.3.2 Reimbursement Uncertainty for Emerging MIGS & AI Diagnostics
- 4.3.3 Growing ASC Price Pressure on Instrument Vendors
- 4.3.4 Tariff-Driven Raw-Material Inflation for Steel/Titanium Tools
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value & Volume)
- 5.1 By Device Type
- 5.1.1 Diagnostic & Monitoring Devices
- 5.1.1.1 OCT Scanners
- 5.1.1.2 Fundus & Retinal Cameras
- 5.1.1.3 Autorefractors & Keratometers
- 5.1.1.4 Corneal Topography Systems
- 5.1.1.5 Ultrasound Imaging Systems
- 5.1.1.6 Perimeters & Tonometers
- 5.1.1.7 Other Diagnostic & Monitoring Devices
- 5.1.2 Surgical Devices
- 5.1.2.1 Cataract Surgical Devices
- 5.1.2.2 Vitreoretinal Surgical Devices
- 5.1.2.3 Refreactive Surgical Devices
- 5.1.2.4 Glaucoma Surgical Devices
- 5.1.2.5 Other Surgical Devices
- 5.1.3 Vision Care Devices
- 5.1.3.1 Spectacles Frames & Lenses
- 5.1.3.2 Contact Lenses
- 5.1.1 Diagnostic & Monitoring Devices
- 5.2 By Disease Indication
- 5.2.1 Cataract
- 5.2.2 Glaucoma
- 5.2.3 Diabetic Retinopathy
- 5.2.4 Other Disease Indications
- 5.3 By End-user
- 5.3.1 Hospitals
- 5.3.2 Specialty Ophthalmic Clinics
- 5.3.3 Ambulatory Surgery Centers (ASCs)
- 5.3.4 Other End-users
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 Alcon Inc.
- 6.3.2 Bausch + Lomb Corp.
- 6.3.3 Carl Zeiss Meditec AG
- 6.3.4 CooperVision Inc.
- 6.3.5 EssilorLuxottica SA
- 6.3.6 Glaukos Corp.
- 6.3.7 Heidelberg Engineering GmbH
- 6.3.8 Hoya Corp.
- 6.3.9 Johnson & Johnson Vision Care Inc.
- 6.3.10 Lensar Inc.
- 6.3.11 Lumenis Be Ltd
- 6.3.12 Nidek Co. Ltd
- 6.3.13 Topcon Corp.
- 6.3.14 Ziemer Ophthalmic Systems AG
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

