PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122392

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122392
Industrial Battery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the industrial battery market size is estimated at USD 41.93 billion in 2026, and is expected to reach USD 93.71 billion by 2031, at a CAGR of 17.45% during the forecast period (2026-2031).
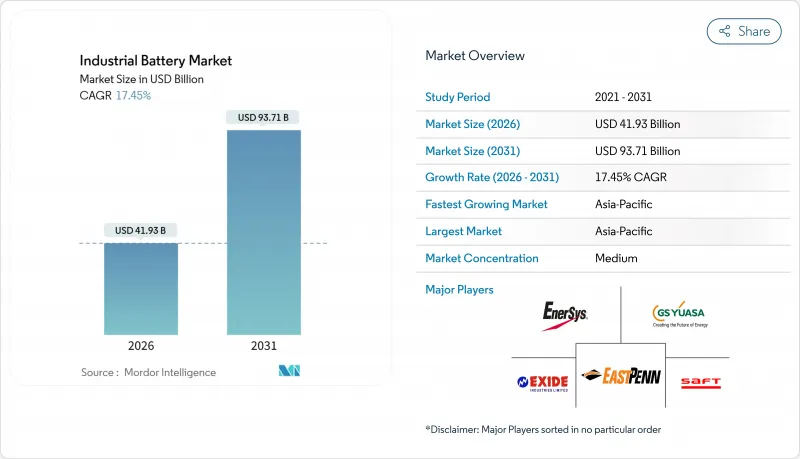
This report is Segmented by Technology (Lithium-Ion, Lead-Acid, Nickel-Based, and Others), Application (Forklift and Motive Power, Telecom Backup, UPS/Data Centres, Grid-Scale ESS, and Others), End-User Industry (Power and Utilities, Oil and Gas, Manufacturing and Warehousing, Telecom, and Others), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa).
Global Industrial Battery Market Trends and Insights
Declining Lithium-Ion Battery Cost Curve
Pack prices slid to USD 115 per kWh in 2024, the sharpest drop since 2017, and major banks forecast sub-USD 80 per kWh by late 2026 as cell-to-pack integration cuts overhead. Chinese LFP cells traded at USD 50-53 per kWh in early 2024, forcing Western rivals to localize or cede margin. Utility-scale four-hour systems are now modeled to reach USD 147-243 per kWh by 2035, eroding lead-acid's total-cost supremacy in telecom backup. Buyers increasingly align budgets to ten-year life-cycle analyses, tilting orders toward lithium-ion despite residual thermal-runaway concerns.
Renewable-Powered ESS Build-Outs
Grid-scale battery additions rose 38% year-over-year to October 2025 and are set to add 94 GW/247 GWh in 2025 alone, jumping to 220 GW/972 GWh by 2035 as intermittent solar and wind portfolios require firming capacity. The United States plans 18.2 GW of storage in 2025, benefiting from investment-tax credits and state mandates. China's provincial rules force new renewables to pair 10-20% storage, creating near-term demand, although capped arbitrage margins cloud profitability. India targets 4 GWh of standalone storage by 2026 to stabilize high-renewable grids. Europe's frequency-regulation premiums remain attractive for batteries, though interconnector growth could compress spreads after 2028.
Critical-Mineral Price Volatility
Lithium carbonate plunged 75% from its 2022 peak, then tightened again in 2025 as inventory destocking met robust demand, unsettling contract negotiations and cash-flow planning. China processes more than 90% of anode materials and 85% of cathodes, amplifying geopolitical exposure for Western buyers. Supply bottlenecks in purified phosphoric acid and high-purity manganese sulfate can double input costs within a quarter, prompting buyers to shorten procurement cycles and raise working-capital buffers. U.S. strategic stockpiles address security rather than price, and may constrict spot availability.
Other drivers and restraints analyzed in the detailed report include:
- Warehouse Automation & AGVs Surge
- DC Micro-Grids in Data Centres
- Lead-Acid Pollution Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Lithium-ion held 51.26% revenue in 2025 and is projected to compound at 18.56% to 2031, solidifying its leadership in the industrial battery market. Lead-acid's legacy telecom and starter-lighting niches shrink as buyers weigh total cost over calendar life. Nickel-based chemistries stay relevant in aerospace and rail, yet flat volumes reflect lithium-ion's broadened temperature range.
Emerging sodium-ion cells promise 20-30% cost savings versus LFP by swapping abundant sodium for scarce lithium, while vanadium redox flow batteries gain traction for six-hour-plus discharge durations. Solid-state prototypes remain three-to-five-times costlier than lithium-ion, prompting most industrial buyers to monitor rather than commit. Recycling mandates accelerate lead-acid's retreat in Europe, redirecting investment to higher-margin lithium-based lines.
Complete Report Scope:
- By Technology
- Lithium-ion
- Lead-acid
- Nickel-based
- Others (incl. Flow Battery, Sodium-ion)
- By Application
- Forklift and Motive Power
- Telecom Backup
- UPS/Data Centres
- Grid-Scale ESS
- Others (incl Automated Guided Vehicles, Rail and Marine)
- By End-User Industry
- Power and Utilities
- Oil and Gas
- Manufacturing and Warehousing
- Telecom
- Others (incl Transportation and Logistics)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Nordic Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific dominated the industrial battery market with 49.92% revenue in 2025 and will grow at 19.53% through 2031. China's 85% share of global cell output and mandatory 10-20% storage pairing for new renewables spur demand, while India's USD 2.4 billion Production-Linked Incentive lures 50 GWh of domestic capacity. South Korea's LG Energy Solution and Samsung SDI exceed 520 GWh of combined capacity, exporting to North America and Europe. Japan remains focused on high-nickel cells for automotive and niche industrial uses.
North America benefits from a USD 35 per kWh production credit and 30+ gigafactory announcements since 2022, targeting 1 TWh of capacity by 2030. Canada's mineral endowment positions it as a Western alternative, although refining lags extraction. Mexico attracts assembly investments but faces permitting bottlenecks.
Europe's Critical Raw Materials Act seeks 10% domestic sourcing and 40% local processing by 2030, supporting Northvolt, ACC, and CATL's European lines. Germany, France, and the U.K. lead in frequency-regulation storage, though expanded interconnectors may pressure margins after 2028. Nordic hydropower attracts energy-intensive cathode synthesis, yet yield challenges slow ramp-ups.
South America and the Middle East-Africa remain nascent, with Brazil and the U.A.E. piloting utility-scale projects, but limited manufacturing keeps scale small relative to Asia-Pacific and North America.
- EnerSys
- East Penn Manufacturing
- Exide Industries
- GS Yuasa Corp.
- Saft Groupe SA
- Amara Raja Batteries
- Panasonic Energy
- CATL
- BYD Co. Ltd.
- LG Energy Solution
- Samsung SDI
- Johnson Controls
- Leoch Int'l
- JYC Battery
- Narada Power
- Crown Battery
- Hoppecke Batteries
- NorthStar Battery
- Trojan Battery
- Vision Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Declining lithium-ion battery cost curve
- 4.2.2 Renewable-powered ESS build-outs
- 4.2.3 Warehouse automation & AGVs surge
- 4.2.4 DC micro-grids in data centres
- 4.2.5 Telecom tower storage mandates
- 4.2.6 OEM-driven 2nd-life leasing models
- 4.3 Market Restraints
- 4.3.1 Critical-mineral price volatility
- 4.3.2 Lead-acid pollution regulations
- 4.3.3 Solid-state tech "wait-and-see" effect
- 4.3.4 Rising BESS fire-risk insurance costs
- 4.4 Battery/Raw-Material Price Trends & Forecast
- 4.5 Import and Export Analysis
- 4.6 Supply-Chain Analysis
- 4.7 Regulatory Landscape
- 4.8 Technological Outlook
- 4.9 Porter's Five Forces
- 4.9.1 Bargaining Power of Suppliers
- 4.9.2 Bargaining Power of Buyers
- 4.9.3 Threat of New Entrants
- 4.9.4 Threat of Substitutes
- 4.9.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Technology
- 5.1.1 Lithium-ion
- 5.1.2 Lead-acid
- 5.1.3 Nickel-based
- 5.1.4 Others (incl. Flow Battery, Sodium-ion)
- 5.2 By Application
- 5.2.1 Forklift and Motive Power
- 5.2.2 Telecom Backup
- 5.2.3 UPS/Data Centres
- 5.2.4 Grid-Scale ESS
- 5.2.5 Others (incl Automated Guided Vehicles, Rail and Marine)
- 5.3 By End-User Industry
- 5.3.1 Power and Utilities
- 5.3.2 Oil and Gas
- 5.3.3 Manufacturing and Warehousing
- 5.3.4 Telecom
- 5.3.5 Others (incl Transportation and Logistics)
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 France
- 5.4.2.3 United Kingdom
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Nordic Countries
- 5.4.2.7 Russia
- 5.4.2.8 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 South Korea
- 5.4.3.5 ASEAN Countries
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 United Arab Emirates
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 South Africa
- 5.4.5.4 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 EnerSys
- 6.4.2 East Penn Manufacturing
- 6.4.3 Exide Industries
- 6.4.4 GS Yuasa Corp.
- 6.4.5 Saft Groupe SA
- 6.4.6 Amara Raja Batteries
- 6.4.7 Panasonic Energy
- 6.4.8 CATL
- 6.4.9 BYD Co. Ltd.
- 6.4.10 LG Energy Solution
- 6.4.11 Samsung SDI
- 6.4.12 Johnson Controls
- 6.4.13 Leoch Int'l
- 6.4.14 JYC Battery
- 6.4.15 Narada Power
- 6.4.16 Crown Battery
- 6.4.17 Hoppecke Batteries
- 6.4.18 NorthStar Battery
- 6.4.19 Trojan Battery
- 6.4.20 Vision Group
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

