PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124544

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124544
Europe Thermal Power - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Europe thermal power market size in terms of installed base is expected to decrease from 615.90 gigawatt in 2025 to 605.52 gigawatt in 2026 and decline to 567.56 gigawatt by 2031, declining at a CAGR of -1.29% over 2026-2031.
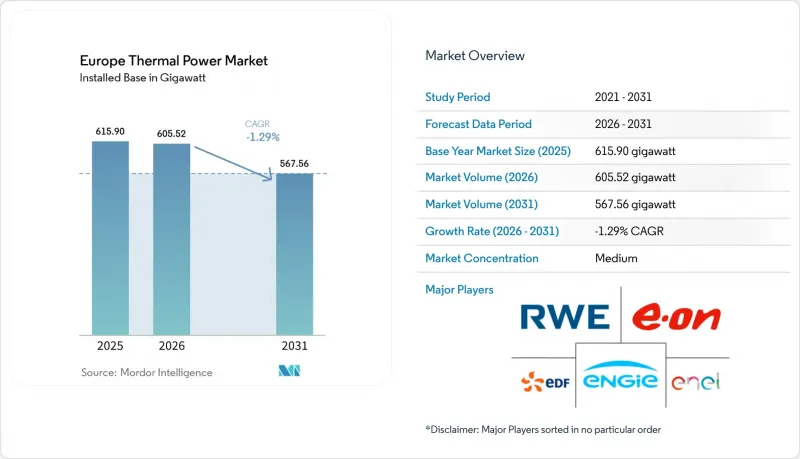
This report is Segmented by Source Type (Coal, Natural Gas, Oil, Nuclear, Others), Technology (Steam Turbine, CCGT, ICE, CHP, Others), Capacity (Below 100 MW, 100-500 MW, 500-1000 MW, Above 1000 MW), Application (Utility-Scale, Industrial Captive, Distributed, Peaker Plants), and Geography (United Kingdom, Germany, France, Russia, Rest of Europe). The Market Forecasts are Provided in Terms of Volume (GW).
Europe Thermal Power Market Trends and Insights
Ageing Coal Fleet Replacement with CCGT
Coal retirement plans are accelerating demand for efficient replacement capacity in the Europe thermal power market. ENTSO-E reported that hard coal and lignite capacity fell by 12 GW between 2024 and the winter of 2025-2026, while gas capacity rose by 4 GW. Germany agreed a framework with the European Commission in January 2026 for 12 GW of controllable, hydrogen-ready capacity that is intended to operate by 2031. The program gives developers with existing grid connections an advantage because replacement projects can move faster than new sites. GE Vernova received an order from Enea Group in November 2025 for two 9HA.01 combined-cycle blocks at Kozienice, with steam turbines to be made in Elblag, Poland. Local equipment production can shorten procurement timelines and support national industrial objectives during coal-to-gas replacement.
Rising Electricity Demand from Data Centers and Electrification
Data center demand is increasing the value of firm capacity in the Europe thermal power market. ENTSO-E expects European data center electricity consumption to exceed 134 TWh by 2030, compared with 87 TWh in 2024. Facilities requiring 99.999% uptime need a dependable electricity supply when renewable output is low. Gas-fired generation can provide balancing power and support grid stability in these conditions. Load concentration in Dublin, Amsterdam, London, and Frankfurt adds pressure to regional networks and favors capacity close to demand centers. Distributed CHP units and peaking plants near data campuses may secure direct power contracts that are less dependent on wholesale dispatch patterns in the Europe thermal power market.
Escalating EU ETS Carbon Prices
EU carbon prices are raising operating costs for fossil-fired plants in the Europe thermal power market. ESMA reported that EU allowance prices averaged EUR 74 per tonne of carbon dioxide equivalent in 2025 and reached EUR 90 per tonne in January 2026. The revised EU ETS targets a 62% reduction in covered emissions by 2030 from 2005 levels. The cost burden is greatest for coal plants because of their higher emissions intensity. Gas plants emit less carbon, but their margins can also weaken when electricity prices do not offset fuel and allowance costs. Older open-cycle units with low utilization may face earlier closure without a formal retirement order in the Europe thermal power market.
Other drivers and restraints analyzed in the detailed report include:
- Government Backing for Natural-Gas Bridge Capacity
- Abundant New LNG/Gas Import Infrastructure
- Rapid Fall in Solar and Wind Power LCOE
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Natural gas held 51.9% of the market share by source type in 2025 and is forecast to grow at a 1.1% CAGR through 2031. Its position reflects new gas additions in Germany, Poland, Greece, and Ukraine, even as the overall installed base declines. Coal remains in structural decline as retirement policies and carbon costs weaken its economics. Germany and Poland continue to have major coal fleets, but their future capacity plans rely increasingly on replacement generation. Nuclear power remains relevant within the broader thermal classification because it uses a steam cycle for electricity generation. Oil and geothermal capacity represent a smaller part of the regional fleet and are most relevant in island systems and remote industrial locations.
Russia anchors a large share of gas-fired capacity and gives the source type a different role than in Western Europe. Gazprom states that its generation assets include large electric and thermal capacity through subsidiaries such as Mosenergo. In Russia, gas remains a major source of regular power and heat supply. In much of the EU, gas is increasingly used for flexibility as variable renewable capacity grows. This difference means that the Europe thermal power market contains both baseload-oriented gas fleets and flexible gas plants that operate around renewable output. The result is a source mix in which natural gas remains the core fuel, but its operating patterns vary substantially by country.
CCGT held 33.2% of the market share in 2025 and is the fastest-growing technology, with the Europe thermal power market size for CCGT forecast to expand at a 2.6% CAGR through 2031. Combined-cycle plants offer higher efficiency than older steam-cycle units and are better suited to hydrogen-ready design requirements. Steam turbine plants remain a large installed base, especially where coal generation and older central power stations are concentrated. ICE plants serve distributed generation and island-grid applications where smaller scale and modular installation are important. CHP systems remain relevant in industrial facilities and district heating networks across Scandinavia, the Baltics, and Central Europe.
Germany's framework for new controllable capacity supports hydrogen-ready CCGT investment. Uniper received preliminary approval in April 2026 for an 890 MW hydrogen-ready unit at Staudinger. Larissa Thermoelectric selected AVAX in August 2026 for a 794 MW CCGT project in Greece that will use Mitsubishi Power technology. DTEK is advancing a 650 MW CCGT project at Burshtyn with GE Vernova. DTEK. These projects show that the Europe thermal power industry is directing development activity toward combined-cycle capacity rather than legacy steam technology.
Complete Report Scope:
- By Source Type
- Coal
- Natural Gas
- Oil
- Nuclear
- Others (geothermal, etc.)
- By Technology
- Steam turbine Power Plant
- Combined Cycle Gas Turbine (CCGT)
- Internal Combustion Engine (ICE) Power Plants
- Cogeneration / Combined Heat and Power (CHP) Plants
- Others (CSP, Open Cycle, etc.)
- By Capacity
- Below 100 MW
- 100-500 MW
- 500-1000 MW
- Above 1000 MW
- By Application
- Utility-Scale Thermal Plants
- Industrial Captive Power Plants
- Distributed Thermal Plants
- Peaker Plants
- By Geography
- United Kingdom
- Germany
- France
- Russia
- Rest of Europe
List of Companies Covered in this Report:
- Engie SA
- Electricite de France SA
- Enel S.p.A.
- RWE AG
- E.ON SE
- Rosatom State Atomic Energy Corp.
- Siemens Energy AG
- Iberdrola SA
- Endesa SA
- Uniper SE
- Vattenfall AB
- Fortum Oyj
- CEZ Group
- Verbund AG
- PGE Polska Grupa Energetyczna
- SSE plc
- Statkraft AS
- Drax Group plc
- Orsted A/S
- Gazprom Energoholding
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Ageing coal fleet replacement with CCGT
- 4.2.2 Rising electricity demand from data centres & electrification
- 4.2.3 Government backing for natural-gas 'bridge' capacity
- 4.2.4 Abundant new LNG/gas import infrastructure
- 4.2.5 Licensing wave of small modular high-temperature reactors
- 4.2.6 Coal-to-biomass repowering for capacity-market payments
- 4.3 Market Restraints
- 4.3.1 Escalating EU ETS carbon prices
- 4.3.2 Rapid fall in solar- & wind-power LCOE
- 4.3.3 Stricter IED air-emission ceilings
- 4.3.4 Cooling-water scarcity & coastal permitting hurdles
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Policy Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 PESTLE Analysis
- 4.9 Investment Analysis
- 4.10 Impacts of Global Geopolitical Tensions on the Market
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Source Type
- 5.1.1 Coal
- 5.1.2 Natural Gas
- 5.1.3 Oil
- 5.1.4 Nuclear
- 5.1.5 Others (geothermal, etc.)
- 5.2 By Technology
- 5.2.1 Steam turbine Power Plant
- 5.2.2 Combined Cycle Gas Turbine (CCGT)
- 5.2.3 Internal Combustion Engine (ICE) Power Plants
- 5.2.4 Cogeneration / Combined Heat and Power (CHP) Plants
- 5.2.5 Others (CSP, Open Cycle, etc.)
- 5.3 By Capacity
- 5.3.1 Below 100 MW
- 5.3.2 100-500 MW
- 5.3.3 500-1000 MW
- 5.3.4 Above 1000 MW
- 5.4 By Application
- 5.4.1 Utility-Scale Thermal Plants
- 5.4.2 Industrial Captive Power Plants
- 5.4.3 Distributed Thermal Plants
- 5.4.4 Peaker Plants
- 5.5 By Geography
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Russia
- 5.5.5 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles of International Majors (Includes Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, recent trends and developments, etc.)
- 6.4.1 Engie SA
- 6.4.2 Electricite de France SA
- 6.4.3 Enel S.p.A.
- 6.4.4 RWE AG
- 6.4.5 E.ON SE
- 6.4.6 Rosatom State Atomic Energy Corp.
- 6.4.7 Siemens Energy AG
- 6.4.8 Iberdrola SA
- 6.4.9 Endesa SA
- 6.4.10 Uniper SE
- 6.4.11 Vattenfall AB
- 6.4.12 Fortum Oyj
- 6.4.13 CEZ Group
- 6.4.14 Verbund AG
- 6.4.15 PGE Polska Grupa Energetyczna
- 6.4.16 SSE plc
- 6.4.17 Statkraft AS
- 6.4.18 Drax Group plc
- 6.4.19 Orsted A/S
- 6.4.20 Gazprom Energoholding
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

