PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124639

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124639
Antibody Drug Conjugates - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the antibody drug conjugates market size is expected to grow from USD 15.61 billion in 2025 to USD 20.12 billion in 2026 and is forecast to reach USD 71.55 billion by 2031 at 28.88% CAGR over 2026-2031.
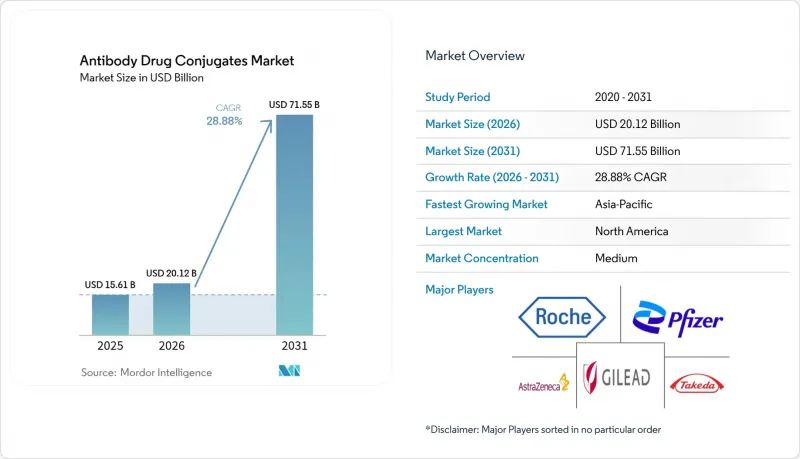
This report is Segmented by Product (Adcetris, Kadcyla, Padcev, and More), Payload Class (Microtubule Inhibitors, DNA-Damaging Agents, and More), Linker Chemistry (Cleavable, Non-Cleavable, Site-Specific), Application (Breast, Hematologic, Urothelial, Lung, and More), End User (Hospitals, Specialty Cancer Centres, and More), and Geography. Market Forecasts are Provided in Terms of Value (USD).
Global Antibody Drug Conjugates Market Trends and Insights
Rising Incidences of Solid Tumors
Worldwide cancer diagnoses reached 19.96 million in 2022, and models project 35 million annual cases by 2050. Breast, lung, and colorectal cancers already anchor ADC approvals yet only 8% of eligible patients received an ADC in 2025, signaling significant headroom for the Antibody-Drug Conjugates market. Lung cancer incidence in China surpassed 800,000 cases in 2024, boosting demand for TROP2- and HER2-targeting conjugates. Solid-tumor heterogeneity spurs development of multi-antigen ADC cocktails, a strategy expected to expand the treatable population by 30% pending regulatory acceptance. Together these forces enlarge the addressable pool for precision payloads and underpin double-digit volume growth through 2031.
Rapid Expansion of >=65-yr Demographic
The global population aged 65 years and older reached 761 million in 2024 and will exceed 1.5 billion by 2050. Cancer incidence in seniors is ten-fold higher than in younger adults, and geriatric guidelines prefer ADCs because targeted delivery lowers systemic toxicity. Japan, where 29% of citizens were over 65 in 2025, cleared four elderly-focused ADC labels, including Enhertu, which cut hospitalizations by 40% versus chemotherapy. In 2025, Medicare began reimbursing home-based ADC infusions, adding 15,000 new treatment starts annually. These demographic and policy shifts lift utilization across mature health systems and reinforce long-run demand in the Antibody-Drug Conjugates market.
High Treatment Costs
Annual U.S. therapy costs range from USD 168,000 for Enhertu to USD 174,000 for Trodelvy, exceeding median household income in 47 states. European HTA bodies rejected reimbursement for three ADCs in 2025 because incremental cost-effectiveness ratios topped EUR 100,000 per quality-adjusted life year. Manufacturing complexity deters biosimilar entrants, preserving originator pricing power through patent lifespans to 2035. Patient-assistance programs defray only 18% of out-of-pocket charges versus 40% for checkpoint inhibitors. High costs temper uptake, particularly in emerging markets, and shave 4.7 percentage points off the projected CAGR.
Other drivers and restraints analyzed in the detailed report include:
- Accelerated R&D Funding and Clinical Trial Initiations
- Growing Pharmaceutical Investments
- Payload Supply Constraints
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Kadcyla held 23.55% of 2025 product revenue, but Enhertu is on track for a 29.25% CAGR through 2031, the fastest among marketed brands. This surge follows HER2-low breast and second-line non-small-cell lung approvals that added 180,000 addressable patients in North America and Europe during 2025. Padcev's first-line urothelial label prompted 73% sequencing shifts away from platinum regimens, validating MMAE payloads in solid tumors. Trodelvy broadened into hormone-receptor-positive breast disease, but infusion reactions in 32% of patients slowed uptake. Polivy and Adcetris face substitution from bispecific T-cell engagers showing superior progression-free survival. Elahere lifted FRa-positive ovarian cancer outcomes, yet testing gaps in community clinics cap penetration. Overall, product churn skews toward topoisomerase payloads, realigning the Antibody-Drug Conjugates market toward solid-tumor indications.
A second-tier cohort-Zynlonta, Blenrep, Mylotarg, Tivdak-contributes incremental revenue streams but battles narrow biomarker windows and payer scrutiny. Blenrep returned to U.S. shelves in 2024 after confirmatory survival data, underscoring regulatory volatility. Pipeline entrants such as Dato-DXd and DusiTag-001 promise broader antigen targeting, suggesting competitive intensity will rise through 2031. These trends indicate ongoing rotation in brand leadership and reinforce the need for differentiated payload-linker platforms inside the Antibody-Drug Conjugates market.
Topoisomerase I inhibitors delivered 53.53% of 2025 revenue, powered by deruxtecan's bystander-killing that addresses antigen-low tumors. The Antibody-Drug Conjugates market size for microtubule inhibitor programs is projected to expand 30.75% CAGR because Pfizer now controls six approved vedotin ADCs and 14 pipeline assets. DNA-damaging payloads such as PBD dimers retain niche share but face yield and safety hurdles. Emerging immunomodulatory payloads attracted USD 1.2 billion in venture backing across 2024-2025, signaling future modality shifts. Payload selection now aligns with tumor microenvironment: hypoxic tumors favor DNA-cleavers, while well-vascularized lesions respond to microtubule disruptors. Robust pipeline diversity ensures that the Antibody-Drug Conjugates market will see payload pluralism rather than single-class dominance.
In parallel, cleavable linkers enable bystander effects crucial for heterogeneous solid cancers. Site-specific conjugation further magnifies payload flexibility, allowing developers to match cytotoxins to antigens without raising systemic toxicity. Consequently, strategic control of payload chemistry has become a revenue stream via out-licensing, as evidenced by Daiichi Sankyo's USD 3.2 billion milestone haul. This economic leverage will intensify demand for proprietary payload platforms across the Antibody-Drug Conjugates market.
Complete Report Scope:
- By Product
- Adcetris (brentuximab vedotin)
- Kadcyla (trastuzumab emtansine)
- Padcev (enfortumab vedotin)
- Polivy (polatuzumab vedotin)
- Enhertu (trastuzumab deruxtecan)
- Trodelvy (sacituzumab govitecan)
- Elahere (mirvetuximab soravtansine)
- Other Approved ADCs
- By Payload Class
- Microtubule Inhibitors (MMAE, DM1, DM4)
- DNA-Damaging Agents (PBD, Calicheamicin, Duocarmycin)
- Topoisomerase I Inhibitors (DXd, SN-38)
- Emerging Payloads (Auristatin variants, novel alkylators)
- By Linker Chemistry
- Cleavable Linkers
- Non-cleavable Linkers
- Site-specific / Next-Gen Conjugation Technologies
- By Application (Indication)
- Breast Cancer
- Hematologic Cancers (Lymphoma, Leukemia, Myeloma)
- Urothelial / Bladder Cancer
- Lung Cancer
- Gynaecologic Cancers (Ovary, Endometrium, Cervix)
- Other Solid Tumors
- By End User
- Hospitals
- Specialty Cancer Centres
- Biopharma & Contract Research Organisations
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 41.55% of 2025 revenue after Medicare began reimbursing outpatient ADC infusions at 106% of average sales price, prompting hospital build-outs of oncology suites. The FDA cleared four new ADC labels between 2024-2025, and Health Canada aligned review timelines, cutting regional launch gaps to eight months. Payload manufacturing clusters in the United States, where Pfizer, Lonza, and Catalent run seven of 12 global conjugation plants, reducing cycle times for Phase 3 material. Biosimilar competition is minimal because reproducing drug-antibody ratios remains technically complex.
Asia-Pacific is the fastest-growing region at 29.22% CAGR through 2031 as China's regulator authorized six domestic ADCs, capturing 23% of the country's biologics spend in 18 months. Japan approved Enhertu for five indications, giving Daiichi Sankyo a 34% share of national ADC revenue. India issued accelerated nods for two biosimilar ADCs in 2025, signaling future price competition where out-of-pocket spending dominates. Australia shortened reviews to 11 months under a 2024 FDA cooperation pact, enabling simultaneous Padcev and Trodelvy launches.
Europe, the Middle East, and South America trail because HTA agencies in Germany, France, and the U.K. demanded real-world evidence before reimbursing three ADCs. EMA's conditional approvals speed initial access yet impose post-marketing costs of USD 8-12 million per indication. Brazil approved Kadcyla and Enhertu in 2025, but private insurance limits coverage to HER2-overexpressing tumors, excluding HER2-low cases in 55% of patients. Saudi Arabia and the UAE embraced FDA reliance pathways, approving four ADCs in 2025 and positioning the Gulf as a fast-track market. Overall, regional disparities in reimbursement and manufacturing footprint influence adoption curves across the Antibody-Drug Conjugates market.
- Abbvie
- ADC Therapeutics
- Amgen
- Astellas Pharma
- AstraZeneca
- BeiGene Ltd.
- BioNTech
- Bristol-Myers Squibb
- Catalent
- Daiichi Sankyo Co. Ltd
- Roche
- Genmab
- Gilead Sciences
- GlaxoSmithKline
- ImmunoGen
- Lonza Group
- MacroGenics Inc.
- Mersana Therapeutics
- Pfizer Inc. (Seagen Inc.)
- RemeGen Co., Ltd
- Synaffix BV
- Takeda Pharmaceuticals
- WuXi XDC
- Zai Lab Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising incidences of solid tumors
- 4.2.2 Rapid expansion of Above 65-yr demographic
- 4.2.3 Accelerated R&D funding and clinical trial initiations
- 4.2.4 Growing pharmaceutical investments
- 4.2.5 Increasing demand for low-toxicity and effective drugs
- 4.2.6 Reimbursement expansion for outpatient ADC administration
- 4.3 Market Restraints
- 4.3.1 High treatment costs
- 4.3.2 Payload supply constraints (auristatin/PBD) causing production bottlenecks
- 4.3.3 Competition from emerging T-cell engagers & bispecific antibodies
- 4.3.4 High manufacturing complexity
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Adcetris (brentuximab vedotin)
- 5.1.2 Kadcyla (trastuzumab emtansine)
- 5.1.3 Padcev (enfortumab vedotin)
- 5.1.4 Polivy (polatuzumab vedotin)
- 5.1.5 Enhertu (trastuzumab deruxtecan)
- 5.1.6 Trodelvy (sacituzumab govitecan)
- 5.1.7 Elahere (mirvetuximab soravtansine)
- 5.1.8 Other Approved ADCs
- 5.2 By Payload Class
- 5.2.1 Microtubule Inhibitors (MMAE, DM1, DM4)
- 5.2.2 DNA-Damaging Agents (PBD, Calicheamicin, Duocarmycin)
- 5.2.3 Topoisomerase I Inhibitors (DXd, SN-38)
- 5.2.4 Emerging Payloads (Auristatin variants, novel alkylators)
- 5.3 By Linker Chemistry
- 5.3.1 Cleavable Linkers
- 5.3.2 Non-cleavable Linkers
- 5.3.3 Site-specific / Next-Gen Conjugation Technologies
- 5.4 By Application (Indication)
- 5.4.1 Breast Cancer
- 5.4.2 Hematologic Cancers (Lymphoma, Leukemia, Myeloma)
- 5.4.3 Urothelial / Bladder Cancer
- 5.4.4 Lung Cancer
- 5.4.5 Gynaecologic Cancers (Ovary, Endometrium, Cervix)
- 5.4.6 Other Solid Tumors
- 5.5 By End User
- 5.5.1 Hospitals
- 5.5.2 Specialty Cancer Centres
- 5.5.3 Biopharma & Contract Research Organisations
- 5.5.4 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 AbbVie Inc.
- 6.3.2 ADC Therapeutics SA
- 6.3.3 Amgen Inc.
- 6.3.4 Astellas Pharma Inc.
- 6.3.5 AstraZeneca plc
- 6.3.6 BeiGene Ltd.
- 6.3.7 BioNTech SE
- 6.3.8 Bristol-Myers Squibb Co.
- 6.3.9 Catalent Inc.
- 6.3.10 Daiichi Sankyo Co. Ltd
- 6.3.11 F. Hoffmann-La Roche Ltd
- 6.3.12 Genmab A/S
- 6.3.13 Gilead Sciences Inc.
- 6.3.14 GSK plc
- 6.3.15 ImmunoGen Inc.
- 6.3.16 Lonza Group AG
- 6.3.17 MacroGenics Inc.
- 6.3.18 Mersana Therapeutics Inc.
- 6.3.19 Pfizer Inc. (Seagen Inc.)
- 6.3.20 RemeGen Co., Ltd
- 6.3.21 Synaffix BV
- 6.3.22 Takeda Pharmaceutical Co. Ltd
- 6.3.23 WuXi XDC
- 6.3.24 Zai Lab Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

