PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154272

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154272
Philippines Crawler Earthmoving Machines - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
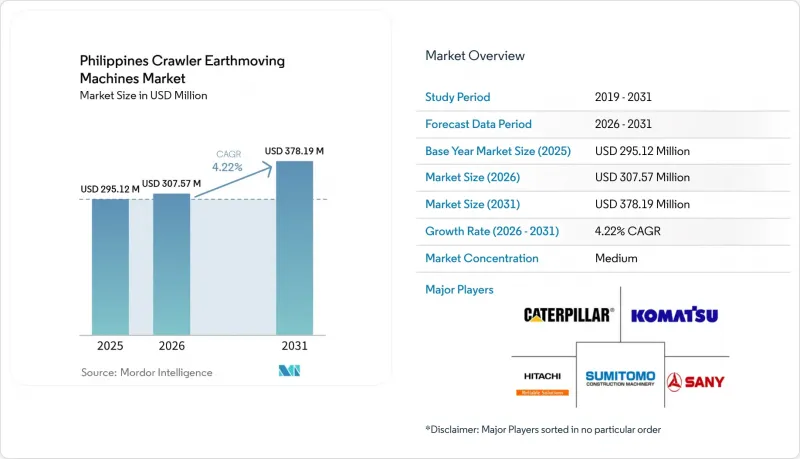
According to Mordor Intelligence, the Philippines crawler earthmoving machines market size was valued at USD 295.12 million in 2025 and is expected to reach USD 307.57 million in 2026 and USD 378.19 million by 2031, registering a 4.22% CAGR between 2026 and 2031.
Philippines Crawler Earthmoving Machines Market Trends and Insights
Government-backed Build Better More (BBM) Infrastructure Pipeline
Dozens of flagship bridges, expressways, and flood-control assets drive continuous crawler deployment cycles, especially around foundation excavation and embankment works. Multilateral financing cushions domestic budget cuts, but slower disbursement can leave machines idle at partially completed sites, reducing fleet utilization. Rental firms benefit because contractors prefer cost-flexible agreements while awaiting notice-to-proceed milestones. Steady urban migration ensures that secondary-city road upgrades remain on the docket, cementing long-run equipment demand even if mega-projects stagger.
Revival of Large-Scale Mining and Quarrying Projects in Mindanao
The commissioning of a major copper-gold project in Surigao del Norte opened a multi-year crawler-replacement pipeline tied to demanding open-pit cycles. Harsh laterite conditions accelerate undercarriage wear, compelling owners to budget for shorter rebuild intervals. Uncertainties around global nickel pricing heighten procurement caution, yet mandated rehabilitation bonds bind operators to maintaining productive fleets. Provincial road upgrades linked to mine logistics further lift localized construction demand, creating a secondary pull for mid-range excavators.
High Upfront CAPEX and Tightening Credit
6-figure price tags for mid-range excavators collide with stricter loan-to-value ratios, forcing many contractors to turn to rentals. Monetary easing trims headline interest rates, but collateral requirements stay high, challenging small builders. Leasing provides an off-balance-sheet option, though effective rates still erode thin project margins. Until liquidity conditions improve, asset-light operating models continue to gain ground, reshaping dealer revenue toward parts and service.
Other drivers and restraints analyzed in the detailed report include:
- Accelerated Replacement of Aging Crawler Fleets for Safety and Efficiency
- Electrification Incentives and Stage V Emission Mandates
- Raw-Material and Component Supply Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Crawler excavators accounted for 55.12% of the Philippines crawler earthmoving machine market share in 2025, reflecting their ability to handle digging, grading, and demolition without frequent tool changes. Compact tracked loaders and skid-steers are projected to post the fastest 4.93% CAGR because tight urban job sites reward machines with small footprints and high maneuverability. Contractors value excavators as multipurpose "anchor" assets that keep fleet sizes lean. Their compatibility with quick-attach couplers reduces downtime, resulting in predictable daily utilization. OEMs therefore prioritize excavator upgrades when introducing digital monitoring or low-emission options.
Demand for compact tracked loaders rises when redevelopment displaces large equipment from congested business districts. Rental firms increasingly stock these loaders to court short-term projects that lack room for full-sized crawlers. Meanwhile, excavators maintain dominance in bridge foundations and open-cut drainage because no other crawler variant offers comparable reach and stability. Dealers bundle attachments such as breakers and grapples with new excavator purchases to underscore the platform's versatility. Together, the two segments illustrate how flexibility, rather than raw power, shapes procurement choices in the Philippines.
Internal-combustion crawlers retained a commanding 96.91% market share in the Philippines crawler earthmoving machines market in 2025, supported by the nationwide diesel supply chain and mechanics' familiarity. Electric and hybrid models are anticipated to register a rapid 22.02% CAGR as contractors test lower-emission alternatives ahead of the incoming Euro 5/V rules. Fleet managers continue to favor diesel because refueling infrastructure is available even at remote job sites. However, hybrid drivetrains deliver tangible fuel savings during stop-and-go cycles, attracting interest among cost-sensitive bidders. Regulatory clarity gives hybrids an extra push by reducing compliance uncertainty around particulate limits.
Dealer service teams invest in high-voltage training to prepare for a gradual rise in hybrid maintenance calls. Financing partners also craft leasing packages that spread the premium on hybrid units over longer contracts. Diesel platforms remain standard on projects with round-the-clock duty cycles where downtime penalties are steep. Even so, early adopters of hybrids gain reputational benefits in government tenders that score highly on environmental criteria. Over time, those soft advantages may erode diesel's historic lock-in despite its logistical edge.
Complete Report Scope:
- By Equipment Type
- Crawler Excavators
- Crawler Bulldozers
- Crawler Loaders
- Crawler Cranes and Pipe-layers
- Compact Tracked Loaders and Skid-steers
- Others (Trencher, Drill Rig, etc.)
- By Propulsion
- Internal Combustion Engine (ICE)
- Electric and Hybrid
- By Engine Power Output
- Below 100 HP
- 100 to 200 HP
- 201 to 400 HP
- Above 400 HP
- By Application
- Construction
- Mining and Quarrying
- Agriculture and Forestry
- Others
- By Distribution Channel
- Direct OEM Sales
- Authorized Dealers
- Rental and Leasing Firms
List of Companies Covered in this Report:
- Caterpillar Inc.
- Komatsu Ltd.
- Hitachi Construction Machinery Co., Ltd.
- Volvo Construction Equipment AB
- Liebherr-International AG
- Sumitomo Construction Machinery
- Kobelco Construction Machinery
- SANY Group
- XCMG Group
- HD Hyundai Construction Equipment
- CNH Industrial - CASE CE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government-Backed Build Better More (BBM) Infrastructure Pipeline
- 4.2.2 Revival of Large-Scale Mining and Quarrying Projects in Mindanao
- 4.2.3 Accelerated Replacement of Aging Crawler Fleets for Safety and Efficiency
- 4.2.4 Electrification Incentives and Stage V Emission Mandates
- 4.2.5 Digital Twins and Telematics-Driven OPEX Savings
- 4.2.6 Surge in Deconstruction and Circular-Demolition Projects
- 4.3 Market Restraints
- 4.3.1 High Upfront CAPEX and Tightening Credit
- 4.3.2 Raw-Material and Component Supply Volatility
- 4.3.3 Scarcity of Fast-Charging Infrastructure for Above 20-T Crawlers
- 4.3.4 ESG-Linked Cost of Ownership for Diesel Units
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) & Volume (Units))
- 5.1 By Equipment Type
- 5.1.1 Crawler Excavators
- 5.1.2 Crawler Bulldozers
- 5.1.3 Crawler Loaders
- 5.1.4 Crawler Cranes and Pipe-layers
- 5.1.5 Compact Tracked Loaders and Skid-steers
- 5.1.6 Others (Trencher, Drill Rig, etc.)
- 5.2 By Propulsion
- 5.2.1 Internal Combustion Engine (ICE)
- 5.2.2 Electric and Hybrid
- 5.3 By Engine Power Output
- 5.3.1 Below 100 HP
- 5.3.2 100 to 200 HP
- 5.3.3 201 to 400 HP
- 5.3.4 Above 400 HP
- 5.4 By Application
- 5.4.1 Construction
- 5.4.2 Mining and Quarrying
- 5.4.3 Agriculture and Forestry
- 5.4.4 Others
- 5.5 By Distribution Channel
- 5.5.1 Direct OEM Sales
- 5.5.2 Authorized Dealers
- 5.5.3 Rental and Leasing Firms
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves & Partnerships
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Caterpillar Inc.
- 6.4.2 Komatsu Ltd.
- 6.4.3 Hitachi Construction Machinery Co., Ltd.
- 6.4.4 Volvo Construction Equipment AB
- 6.4.5 Liebherr-International AG
- 6.4.6 Sumitomo Construction Machinery
- 6.4.7 Kobelco Construction Machinery
- 6.4.8 SANY Group
- 6.4.9 XCMG Group
- 6.4.10 HD Hyundai Construction Equipment
- 6.4.11 CNH Industrial - CASE CE
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

