PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154282

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154282
Electric Vehicle Leasing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
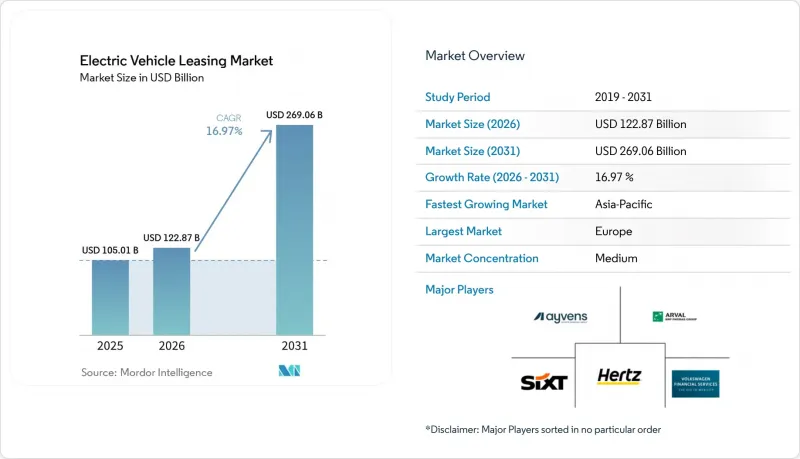
According to Mordor Intelligence, the electric vehicle leasing market size was valued at USD 105.01 billion in 2025 and is estimated at USD 122.87 billion in 2026, and is projected to reach USD 269.06 billion by 2031, growing at a CAGR of 16.97% from 2026 to 2031.
Global Electric Vehicle Leasing Market Trends and Insights
Government Incentives and Tax Credits Favor Leasing
Fiscal architecture channels bigger subsidies through leasing than through direct purchase in several key markets. United States commercial lessors can claim the full USD 7,500 credit irrespective of customer income thresholds, passing the benefit to lessees in the form of lower money factors . Fleet operators in India can benefit from the FAME-II scheme, which provides significant incentives for electric vehicles, making EVs more financially attractive than traditional purchases. China's purchase-tax exemption, recently extended through 2027, now includes provincial-level top-ups for leasing companies deploying vehicles in ride-hailing applications. Germany's benefit-in-kind valuation for battery-electric company cars keeps salary-sacrifice leases firmly ahead of outright acquisitions. Lessors, therefore, lobby for multiyear subsidy visibility, arguing that opaque policy timelines inflate the risk premium baked into residuals.
Corporate Sustainability Mandates Electrify Fleets
Corporations committed to the Science-Based Targets initiative are shifting towards zero-emission fleets, viewing leasing as a cost-effective compliance strategy. The European Union mandates that by 2030, 45% of new corporate vehicle acquisitions must be zero-emission, with the target increasing further by 2035 . Simultaneously, the United States offers a commercial clean-vehicle credit under the Inflation Reduction Act, providing financial incentives for leased units at the time of origination. Ayvens reported a surge in demand in 2025, revealing a notable increase in battery-electric vehicles from 2024. Fleet managers, eager to secure residual guarantees, are rolling out multi-year tenders, favoring lessors who boast integrated maintenance and depot-charging partnerships. In contrast, those without dedicated infrastructure are feeling the pinch, as outsourcing services drive up lifecycle costs.
2026-27 Off-lease EV Glut May Depress Prices
In 2026-2027, North American and European leases will see the return of a significant number of electric vehicles to the market. This influx is set to substantially increase the off-lease volume of 2025, potentially leading to a notable impact on auction values. Data indicates that in 2026, used-EV prices experienced a decline, driven by a supply surge outpacing retail demand. Hertz faced challenges in 2025 due to accelerated depreciation on its Model 3 units. In response, lessors are tightening future residual guarantees, a move that either increases monthly payments or shortens contract lengths, effectively tempering the pace of demand growth.
Other drivers and restraints analyzed in the detailed report include:
- Declining Battery Costs Improve Residual Values
- Rising EV Model Variety Lowers Entry Cost via Leasing
- Uncertain Residual Values Amid Rapid Tech Change
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger cars dominated with 81.25% of the electric vehicle leasing market revenue in 2025, but growth momentum is gradually shifting toward vans and pickups that serve e-commerce logistics. Commercial vehicles represent the most dynamic component of the electric vehicle leasing market, set to expand at a 17.86% CAGR. Amazon's commitment to lease 100,000 Rivian electric delivery vans underpins scale economics in depot charging and maintenance. DHL's eSprinter program in 2025 illustrated how turnkey leasing simplifies compliance with low-emission-zone rules.
Lessors are layering telematics into usage-based fee structures, linking payment schedules to kilometers driven or parcels delivered. Light commercial vehicles under 3.5 tons headline demand, partly because municipal regulations increasingly bar combustion vans from urban cores. In passenger cars, compact and mid-size segments exhibit the fastest leasing rotation due to earlier cost parity. Luxury EV leasing lags due to higher residual volatility, although software-defined upgrades may improve retention over time.
Battery-electric vehicles (BEVs) captured 73.18% of 2025 lease originations and are forecast to expand at 19.13% CAGR, widening their lead over plug-in hybrids. Toyota revealed that in 2025, a significant portion of its leased fleet in Europe comprised battery electric vehicles (BEVs), showing notable growth from the previous year. With several jurisdictions set to exclude plug-in hybrid electric vehicles (PHEVs) from zero-emission mandates post-2030, hybrid residual values face constraints, leading lessors to shorten contract durations. As a result, BEVs dominate the electric vehicle leasing market across various propulsion categories.
Fuel-cell electric vehicles hold a minimal share, finding their niche in hydrogen-infrastructure corridors located in California, Germany, and South Korea. The current strategy emphasizes phasing out PHEV portfolios by 2027, coinciding with OEMs' discontinuation of dual-drivetrain lines. In response, lessors are adjusting by modeling steeper depreciation curves for hybrids and reallocating capital towards BEVs, which not only qualify for more substantial subsidies but also boast lower maintenance costs.
Complete Report Scope:
- By Vehicle Type
- Passenger Cars
- Commercial Vehicles
- By Propulsion Type
- Battery Electric Vehicles
- Plug-in Hybrid Electric Vehicles
- Fuel-Cell Electric Vehicles
- By End User
- Individual Customers
- Corporate Fleets
- Government Agencies
- Ride-Sharing and Delivery Platforms
- By Duration
- Short-Term (Less than 12 months)
- Mid-Term (1-3 years)
- Long-Term (More than 3 years)
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- Spain
- Italy
- France
- Netherlands
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- South Korea
- Indonesia
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Europe controlled 46.22% of the electric vehicle leasing market in 2025, buoyed by policy instruments such as Germany's company-car tax regime and the United Kingdom's plug-in van grant. France continues its ecological bonus for vehicles leased under a specific price threshold through 2026. In the Netherlands, high charger density alleviates range anxiety, supporting strong individual lease penetration. Arval highlights an increase in zero-emission vehicles in European origins between 2023 and 2025. Europe faces the challenge of managing the influx of off-lease inventory during 2026-2027 as residual-value pressures grow.
Asia-Pacific is the fastest-growing region at 17.48% CAGR, propelled by China's 40% new-energy-vehicle sales mandate for 2030. Beijing extends its purchase-tax exemption until 2027, while Shenzhen offers a leasing subsidy, spurring corporate adoption. India's FAME-II disburses INR 10,000 crore (USD 1.2 billion) in incentives, while Maharashtra's top-up grants slice the total cost of ownership for fleet operators. While Japan and South Korea grapple with hybrid consumer preferences and limited charging infrastructure, both nations have set legally binding goals to phase out internal combustion engines (ICE) by 2035, paving the way for intensified leasing activities later in the decade. Meanwhile, Southeast Asia witnesses a surge in momentum, particularly with Grab-led ride-hailing electrification efforts in Jakarta and Bangkok.
North America's uptake pivots on the Inflation Reduction Act's clean-vehicle credit, which lessors capture at origination. Tesla Financial Leasing, Enterprise, and Hertz dominate volume, although Hertz's 2024-2025 residual-value setback underscores risk. Canada furnishes CAD 5,000 (approximately USD 3,700) complemented by federal incentives plus provincial add-ons, sustaining a cross-border pipeline of zero-emission lease demand . South American penetration remains embryonic; pilot taxi and bus programs in Brazil, Chile, and Argentina advance but face tariff and infrastructure drags. Gulf Cooperation Council states roll out fleet-oriented leasing pilots aligned with national diversification agendas, while South Africa experiments with corporate EV rentals in high-tourism corridors.
- Ayvens Group
- Arval (BNP Paribas)
- Sixt SE
- Hertz Global Holdings, Inc.
- Enterprise Mobility
- Avis Budget Group
- Mercedes-Benz Mobility
- Volkswagen Financial Services AG
- Tesla Financial Services
- Novuna Vehicle Solutions
- Hyundai Capital Services
- Toyota Financial Services
- Rivian Financial Services
- EverFleet (Spring Free EV, Inc.)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government Incentives and Tax Credits Favor Leasing
- 4.2.2 Corporate Sustainability Mandates Electrify Fleets
- 4.2.3 Declining Battery Costs Improve Residual Values
- 4.2.4 Rising EV Model Variety Lowers Entry Cost via Leasing
- 4.2.5 Flexible Micro-Lease Platforms Expand (Less than 12 Months)
- 4.2.6 AI-driven Battery Analytics Lower Residual-value Risk
- 4.3 Market Restraints
- 4.3.1 2026-27 Off-lease EV Glut May Depress Prices
- 4.3.2 Uncertain Residual Values Amid Rapid Tech Change
- 4.3.3 Limited Public Charging Dampens Lessee Confidence
- 4.3.4 Higher Interest Rates Lift Lease Payments
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value, USD)
- 5.1 By Vehicle Type
- 5.1.1 Passenger Cars
- 5.1.2 Commercial Vehicles
- 5.2 By Propulsion Type
- 5.2.1 Battery Electric Vehicles
- 5.2.2 Plug-in Hybrid Electric Vehicles
- 5.2.3 Fuel-Cell Electric Vehicles
- 5.3 By End User
- 5.3.1 Individual Customers
- 5.3.2 Corporate Fleets
- 5.3.3 Government Agencies
- 5.3.4 Ride-Sharing and Delivery Platforms
- 5.4 By Duration
- 5.4.1 Short-Term (Less than 12 months)
- 5.4.2 Mid-Term (1-3 years)
- 5.4.3 Long-Term (More than 3 years)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 Spain
- 5.5.3.4 Italy
- 5.5.3.5 France
- 5.5.3.6 Netherlands
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 India
- 5.5.4.2 China
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Indonesia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Ayvens Group
- 6.4.2 Arval (BNP Paribas)
- 6.4.3 Sixt SE
- 6.4.4 Hertz Global Holdings, Inc.
- 6.4.5 Enterprise Mobility
- 6.4.6 Avis Budget Group
- 6.4.7 Mercedes-Benz Mobility
- 6.4.8 Volkswagen Financial Services AG
- 6.4.9 Tesla Financial Services
- 6.4.10 Novuna Vehicle Solutions
- 6.4.11 Hyundai Capital Services
- 6.4.12 Toyota Financial Services
- 6.4.13 Rivian Financial Services
- 6.4.14 EverFleet (Spring Free EV, Inc.)
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

