PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154433

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154433
Craniomaxillofacial Implants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
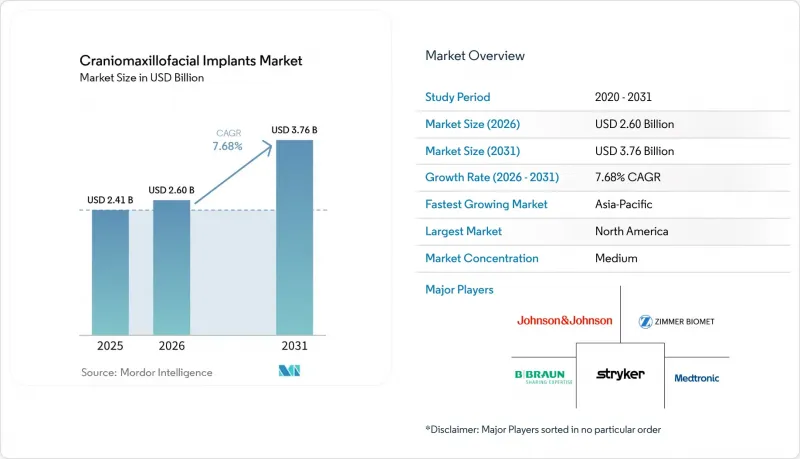
According to Mordor Intelligence, the craniomaxillofacial implants market size is projected to be USD 2.41 billion in 2025, USD 2.60 billion in 2026, and reach USD 3.76 billion by 2031, growing at a CAGR of 7.68% from 2026 to 2031.
Global Craniomaxillofacial Implants Market Trends and Insights
Rising Craniofacial Trauma and Reconstruction Volumes Anchor Near-Term Demand
Craniofacial trauma remains a key demand driver for fixation systems in the craniomaxillofacial implants market. Motor vehicle collisions accounted for 34.3% of pediatric CMF fractures reported in the U.S. National Trauma Data Bank between 2017 and 2024. Seat belt use reduced the risk of CMF fractures in motor vehicle collisions by 42.8%, yet severe trauma cases continue to require plates, screws, mesh, and other fixation products. China recorded 1,194,145 new facial fracture cases in 2024, while the age-standardized incidence increased by 17.74% between 2010 and 2021. Trauma-related costs at tertiary hospitals in China exceeded USD 5.5 billion in 2020. Orbital and midface injuries often require mesh and titanium fixation, while post-resection cranial defects sustain demand for cranioplasty procedures. These trauma and oncology-driven indications support consistent demand for established fixation hardware.
Growing Use of Patient-Specific and 3D-Printed Implants Reshapes Pricing Architecture
Patient-specific titanium cranial implants have become more accessible through established U.S. regulatory pathways. In July 2026, Walter Reed National Military Medical Center received FDA premarket clearance K253116 for its 3D MAC Titanium Cranial Plate System. The clearance was the first granted to a point-of-care institution for an implant system and supported hospital-site manufacturing for selected cranial implant cases. 3D Systems supported the center's 3D Medical Applications Center in this effort. The shift toward customized production is changing the commercial structure of the craniomaxillofacial implants market. Patient-specific implants command average selling prices that are three to five times higher than standard hardware, reflecting imaging, design, manufacturing, and sterilization requirements. Materialize and Stryker benefit from digital platforms linked to implant ordering, while conventional hardware suppliers may face competitive pressure in complex reconstruction cases.
High Implant, Planning, and Procedure Costs Constrain Penetration in Cost-Sensitive Settings
Patient-specific titanium or PEEK cranial implants can exceed USD 10,000-20,000 per case in U.S. hospital acquisition costs, including design services, additive manufacturing, and sterilization. Surgeon fees, operating room time, virtual surgical planning, and splint manufacturing can add USD 1,500-3,000 per orthognathic case. Diagnosis-related group reimbursement may not fully cover these costs, limiting adoption under fixed procedure payment models. Low- and middle-income countries account for 80-90% of global accident-related injuries requiring surgical treatment. Limited infrastructure and reimbursement coverage often lead providers to manage CMF fractures conservatively or use lower-cost generic titanium mini-plates. While modular pricing could separate implant and planning costs, limited supply chain transparency and supplier resistance to changing bundled models restrict wider adoption in the craniomaxillofacial implants market.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Orthognathic, Maxillofacial, and Aesthetic Surgery Broadens the Addressable Case Mix
- Increasing Use of Resorbable and Bioactive Implant Materials Shifts Long-Term Replacement Dynamics
- Shortage of Specialized Craniomaxillofacial Surgeons Creates Systemic Capacity Gaps
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plates and screws held 45.76% of the craniomaxillofacial implants market share in 2025, supported by their use in trauma, orthognathic surgery, and reconstruction. Titanium fixation hardware remained a baseline requirement across CMF procedures, providing the category with a broad procedural base. Stryker's Universal Select system combines variable-angle locking with AXS screw geometry, while DePuy Synthes' TRUMATCH CMF platform integrates 3D-printed titanium plates with digital preoperative planning. Mesh systems and cranial flap fixation systems remain complementary categories, while distraction and temporomandibular joint replacement systems serve narrower, higher-value indications.
Bone graft substitutes are forecast to grow at a CAGR of 8.51% from 2026 to 2031. Synthetic hydroxyapatite, beta-tricalcium phosphate, and demineralized bone matrix reduce donor-site morbidity associated with autograft harvesting, supporting their use in reconstruction. FDA Breakthrough Device designations for several bioactive graft materials shortened review timelines and indicated clinical differentiation to payers. Patient-specific implants remain a smaller revenue category but have the highest average selling price, with growth dependent on reliable planning and manufacturing workflows.
Titanium and titanium alloys accounted for 61.65% of revenue in 2025, supported by their biocompatibility, corrosion resistance, and fatigue strength. These properties established titanium as a regulatory benchmark for alternative materials and supported its use in orbital rim reconstruction, mandibular plating, and craniofacial distraction systems. Broad surgeon familiarity and an established clearance history continued to reduce adoption barriers across trauma and reconstructive procedures. The craniomaxillofacial implants market, therefore, continued to rely on titanium for core fixation requirements.
PEEK emerged as a credible alternative for patient-specific implant applications. A 2025 study reported a mean ANA aesthetic satisfaction score of 8.86 for PEEK, compared with scores of 8.25 or lower for titanium, silicone, and PMMA; the complication profile included hematoma, with no rejection or infection events. Bioabsorbable polymers are projected to grow at a CAGR of 10.89% through 2031, as they can avoid secondary hardware removal. A 2026 review described broader PEEK use across CMF and temporomandibular joint applications, including plasma treatment, hydroxyapatite nanoparticle coating, and nanotopographic modification to improve osseointegration. Ceramics and stainless steel remain mature niches, while biomaterials and composite matrices continue to develop.
Complete Report Scope:
- By Product and Technique
- Plates and Screws
- Mesh Systems
- Bone Graft Substitutes
- Dural Repair Products
- Cranial Flap Fixation Systems
- Craniomaxillofacial Distraction Systems
- Temporomandibular Joint Replacement Systems
- Patient-Specific Implants
- By Material
- Titanium and Titanium Alloys
- Stainless Steel
- Polymers
- Bioabsorbable Polymers
- Ceramic
- Biomaterials
- PEEK
- Others
- By Application
- Trauma and Fracture Reconstruction
- Neurosurgery and Cranial Reconstruction
- Orthognathic and Dental Surgery
- Pediatric Craniosynostosis Repair
- Oncology and Post-Tumor Reconstruction
- Congenital Deformity Correction
- Temporomandibular Joint Reconstruction
- Plastic and Aesthetic Reconstruction
- Others
- By End User
- Hospitals
- Ambulatory Surgery Centers
- Specialty Clinics
- Academic and Teaching Hospitals
- Research and Development Institutions
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 39.56% of revenue in 2025. The United States recorded more than 400,000 annual emergency room visits for facial fractures, while reimbursement for craniosynostosis repair and post-oncological cranioplasty supported specialized reconstruction. Extensive craniofacial care networks and the high adoption of virtual surgical planning strengthened regional demand. In July 2026, Walter Reed received clearance for the 3D MAC Titanium Cranial Plate System from 3D Systems, reinforcing the United States' position as a key regulatory and clinical market for customized implant platforms.
Europe maintained a substantial position in the craniomaxillofacial implants market, led by Germany, the United Kingdom, France, Italy, and Spain. Centralized hospital networks and academic CMF programs supported procedure volumes, although cost and logistical constraints limited broader digital integration; a 2025 survey found that 44.4% of German oral and maxillofacial surgeons used hybrid digital and conventional planning methods. In February 2026, Materialize added custom-made PEEK implants to its CMF portfolio for European surgeons. The products were manufactured under EN ISO 13485, with a 72-hour turnaround following plan approval, while European suppliers retained strong positions in resorbable fixation and patient-specific design services.
Asia-Pacific was the fastest-growing region in the craniomaxillofacial implants market, supported by China's expanding surgical infrastructure, advanced reconstructive and aesthetic systems in South Korea and Japan, and trauma and congenital reconstruction needs in India. . Domestic and global suppliers targeted fixed-price, high-volume titanium hardware demand in China. Brazil led South American volumes through established reconstructive surgery infrastructure, while Gulf Cooperation Council healthcare investment supported hospital capacity and surgeon training in the Middle East and Africa, where markets remained emerging.
- Acumed
- Anatomics
- B. Braun
- Calavera Surgical Design
- Conmed
- Integra LifeSciences
- Jeil Medical
- Johnson & Johnson
- KLS Martin SE & Co. KG
- Materialise
- Matrix Surgical USA
- Medartis Holding AG
- Medtronic
- Orthofix
- OsteoMed, L.P.
- Osteopore Limited
- Rebstock Instruments GmbH
- Renishaw plc
- Smith+Nephew plc
- Stryker
- Xilloc Medical B.V.
- Zimmer Biomet
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Craniofacial Trauma and Reconstruction Volumes
- 4.2.2 Growing Use of Patient-Specific and 3D-Printed Implants
- 4.2.3 Increasing Pediatric Craniosynostosis and Congenital Deformity Procedures
- 4.2.4 Expansion of Orthognathic, Maxillofacial and Aesthetic Surgery
- 4.2.5 Integration of Virtual Surgical Planning With Implant Workflows
- 4.2.6 Increasing Use of Resorbable and Bioactive Implant Materials
- 4.3 Market Restraints
- 4.3.1 High Implant, Planning and Procedure Costs
- 4.3.2 Shortage of Specialized Craniomaxillofacial Surgeons
- 4.3.3 Regulatory and Clinical Validation Complexity for Patient-Specific Devices
- 4.3.4 Limited Long-Term Evidence for Advanced PEEK, Magnesium and 4D-Printed Implants
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Product and Technique
- 5.1.1 Plates and Screws
- 5.1.2 Mesh Systems
- 5.1.3 Bone Graft Substitutes
- 5.1.4 Dural Repair Products
- 5.1.5 Cranial Flap Fixation Systems
- 5.1.6 Craniomaxillofacial Distraction Systems
- 5.1.7 Temporomandibular Joint Replacement Systems
- 5.1.8 Patient-Specific Implants
- 5.2 By Material
- 5.2.1 Titanium and Titanium Alloys
- 5.2.2 Stainless Steel
- 5.2.3 Polymers
- 5.2.4 Bioabsorbable Polymers
- 5.2.5 Ceramic
- 5.2.6 Biomaterials
- 5.2.7 PEEK
- 5.2.8 Others
- 5.3 By Application
- 5.3.1 Trauma and Fracture Reconstruction
- 5.3.2 Neurosurgery and Cranial Reconstruction
- 5.3.3 Orthognathic and Dental Surgery
- 5.3.4 Pediatric Craniosynostosis Repair
- 5.3.5 Oncology and Post-Tumor Reconstruction
- 5.3.6 Congenital Deformity Correction
- 5.3.7 Temporomandibular Joint Reconstruction
- 5.3.8 Plastic and Aesthetic Reconstruction
- 5.3.9 Others
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Ambulatory Surgery Centers
- 5.4.3 Specialty Clinics
- 5.4.4 Academic and Teaching Hospitals
- 5.4.5 Research and Development Institutions
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Acumed LLC
- 6.3.2 Anatomics Pty Ltd
- 6.3.3 B. Braun Melsungen AG
- 6.3.4 Calavera Surgical Design
- 6.3.5 CONMED Corporation
- 6.3.6 Integra LifeSciences Holdings Corporation
- 6.3.7 Jeil Medical Corporation
- 6.3.8 Johnson & Johnson
- 6.3.9 KLS Martin SE & Co. KG
- 6.3.10 Materialise NV
- 6.3.11 Matrix Surgical USA
- 6.3.12 Medartis Holding AG
- 6.3.13 Medtronic plc
- 6.3.14 Orthofix Medical Inc.
- 6.3.15 OsteoMed, L.P.
- 6.3.16 Osteopore Limited
- 6.3.17 Rebstock Instruments GmbH
- 6.3.18 Renishaw plc
- 6.3.19 Smith+Nephew plc
- 6.3.20 Stryker Corporation
- 6.3.21 Xilloc Medical B.V.
- 6.3.22 Zimmer Biomet Holdings, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

