PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155235

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155235
Liquefied Petroleum Gas (LPG) Power Generation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the liquefied petroleum gas power generation market size is expected to grow from USD 886.05 million in 2025 to USD 907.53 million in 2026 and is forecast to reach USD 950.49 million by 2031 at 0.92% CAGR over 2026-2031.
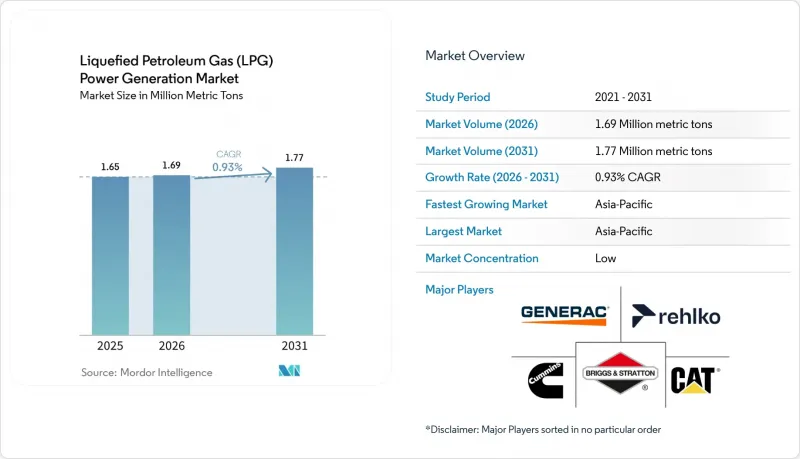
Global Liquefied Petroleum Gas (LPG) Power Generation Market Trends and Insights
Grid Reliability and Extreme-Weather Resilience
Grid reliability has become an operating concern for facilities that cannot accept power interruptions. The Department of Energy assessment cited by PERC showed a widening difference between peak demand and planned firm generation in the United States. Renewable additions do not always align with the peak loads created by computing, cooling, and industrial processes. The LPG power generation market therefore benefits where operators need a generator that can start on demand and retain fuel on site. In July 2026, PERC reported that commercial facilities in the PJM region used propane-powered distributed generation for peak shaving during a hot weather alert. These operating cases support demand that extends beyond seasonal weather events.
Cleaner Backup Power Versus Diesel
Emissions rules for stationary diesel equipment can improve the position of propane in the LPG power generation market. PERC reported that propane produces 139 lbs of carbon dioxide per million BTU, compared with 161 lbs per million BTU for diesel. The same comparison showed lower sulfur oxide emissions and lower nitrogen oxide output for propane under comparable operating conditions. These characteristics can matter in urban and suburban locations where air-quality restrictions limit diesel run hours. PERC has set a target to displace 12% of diesel use in power generation, equal to 45 million gallons, by 2029. The opportunity depends on permitting rules, site economics, and the availability of propane equipment at the required scale.
LPG Distribution Gaps in Remote Markets
Fuel delivery remains a central limitation in the LPG power generation market, especially in remote areas with weak road networks or limited storage and refilling capacity. Operators depend on road tankers or ships when pipeline supply is unavailable. Delays can reduce the certainty that a generator will have fuel during an outage. The challenge is most relevant in rural parts of Asia-Pacific, Sub-Saharan Africa, and South America. Cold climates add a separate constraint because vaporization performance can reduce generator output by 10-15% in sub-zero conditions. Local permitting, noise requirements, and safety procedures can also extend deployment schedules in dense urban locations.
Other drivers and restraints analyzed in the detailed report include:
- Data Center and Critical-Facility Load Growth
- Off-Grid Electrification and Remote-Site Deployment
- Competition From Battery Storage and Solar Hybrids
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Commercial and industrial users held 50.4% of LPG power generation market share in 2025 and are forecast to grow at a 1.1% CAGR from 2026 to 2031. This group includes manufacturing facilities, hotels, retailers, and critical facilities that require continuous or quickly available power. The segment is the largest part of the LPG power generation industry because unplanned outages can interrupt operations, safety systems, and customer service. PERC stated that an outage can cost a business as much as USD 78,000 when backup coverage is inadequate. Healthcare facilities, water treatment plants, and military installations require dependable power because their operations cannot rely solely on the grid.
These installations are often designed for multiple days of continuous duty, unlike residential standby systems that commonly serve shorter events. Data center load growth and industrial automation reinforce the need for larger systems with stronger fuel management. Commercial buyers can also use on-site generation to manage peak demand charges. The LPG power generation market size for this end-user group benefits from propane storage where natural gas pipeline access is constrained. Larger orders favor suppliers that can provide installation support, maintenance, and coordinated energy controls. This makes long-term service capability an important part of competition in the LPG power generation industry.
Complete Report Scope:
- By End User
- Residential
- Commercial & Industrial
- Utility
- By Application
- Prime Mover
- Backup Power
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- Italy
- Spain
- United Kingdom
- Poland
- Netherlands
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Vietnam
- Thailand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- South Africa
- Morocco
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific held 38.5% of LPG power generation market share in 2025 and is forecast to grow at a 1.8% CAGR through 2031. The region combines industrial electrification gaps, island grids, and established residential LPG distribution in several countries. These conditions can support incremental adoption of generators for homes, businesses, and remote facilities. The regional LPG power generation market also benefits where grid extension is difficult or where resilience needs are rising. Rural and island deployments require dependable distribution because logistics remains a key deployment risk.
North America was the second-largest regional market, supported by mature propane distribution and a large standby-generator base in areas affected by hurricanes and winter storms. Generac cited nearly 1.5 billion U.S. outage hours in 2024 in its January 2025 product announcement. The company also cited a 30% rise in electricity costs per kilowatt-hour since 2020, based on U.S. Bureau of Labor Statistics data. These conditions support residential and commercial interest in on-site equipment. In Europe, grid-connected natural gas has a strong position, as German natural gas generation rose 10.2% to 70.6 billion kWh in 2025.
Europe nevertheless retains opportunities in properties without gas pipelines and in combined heat and power systems. Poland and the Netherlands have off-grid residential and agricultural demand that can support propane-based power equipment. South America and the Middle East and Africa represented the remaining volume in the global LPG power generation market. Their potential rests on broader LPG infrastructure, remote-site demand, and the ability of distributors to maintain supply reliability. The LPG power generation market has a longer-term role in areas where decentralized systems can provide electricity before grid infrastructure becomes economically viable.
- Atlas Copco AB
- Briggs & Stratton Corporation
- Caterpillar Inc.
- Champion Power Equipment
- Cummins Inc.
- DuroMax Power Equipment
- FIRMAN Power Equipment
- Generac Holdings Inc.
- INNIO Group
- MAN Energy Solutions SE
- Mitsubishi Heavy Industries, Ltd.
- Rehlko
- Rolls-Royce Power Systems AG
- Westinghouse Outdoor Power Equipment
- Winco, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Grid Reliability and Extreme-Weather Resilience
- 4.2.2 Cleaner Backup Power Versus Diesel
- 4.2.3 Data Center and Critical-Facility Load Growth
- 4.2.4 Off-Grid Electrification and Remote-Site Deployment
- 4.2.5 Propane Storage and Fuel-Supply Flexibility
- 4.2.6 LPG-Enabled Microgrids and Demand Response
- 4.3 Market Restraints
- 4.3.1 LPG Distribution Gaps in Remote Markets
- 4.3.2 Competition From Battery Storage and Solar Hybrids
- 4.3.3 Propane Vaporization and Cold-Climate Derating
- 4.3.4 Local Permitting, Noise, and Safety Complexity
- 4.4 Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By End User
- 5.1.1 Residential
- 5.1.2 Commercial & Industrial
- 5.1.3 Utility
- 5.2 By Application
- 5.2.1 Prime Mover
- 5.2.2 Backup Power
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 Europe
- 5.3.2.1 Germany
- 5.3.2.2 France
- 5.3.2.3 Italy
- 5.3.2.4 Spain
- 5.3.2.5 United Kingdom
- 5.3.2.6 Poland
- 5.3.2.7 Netherlands
- 5.3.2.8 Rest of Europe
- 5.3.3 Asia-Pacific
- 5.3.3.1 China
- 5.3.3.2 India
- 5.3.3.3 Japan
- 5.3.3.4 South Korea
- 5.3.3.5 Australia
- 5.3.3.6 Indonesia
- 5.3.3.7 Vietnam
- 5.3.3.8 Thailand
- 5.3.3.9 Rest of Asia-Pacific
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Chile
- 5.3.4.4 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 United Arab Emirates
- 5.3.5.3 Egypt
- 5.3.5.4 South Africa
- 5.3.5.5 Morocco
- 5.3.5.6 Rest of Middle East and Africa
- 5.3.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Atlas Copco AB
- 6.4.2 Briggs & Stratton Corporation
- 6.4.3 Caterpillar Inc.
- 6.4.4 Champion Power Equipment
- 6.4.5 Cummins Inc.
- 6.4.6 DuroMax Power Equipment
- 6.4.7 FIRMAN Power Equipment
- 6.4.8 Generac Holdings Inc.
- 6.4.9 INNIO Group
- 6.4.10 MAN Energy Solutions SE
- 6.4.11 Mitsubishi Heavy Industries, Ltd.
- 6.4.12 Rehlko
- 6.4.13 Rolls-Royce Power Systems AG
- 6.4.14 Westinghouse Outdoor Power Equipment
- 6.4.15 Winco, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

