PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155638

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155638
Bulk Cargo Shipping - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
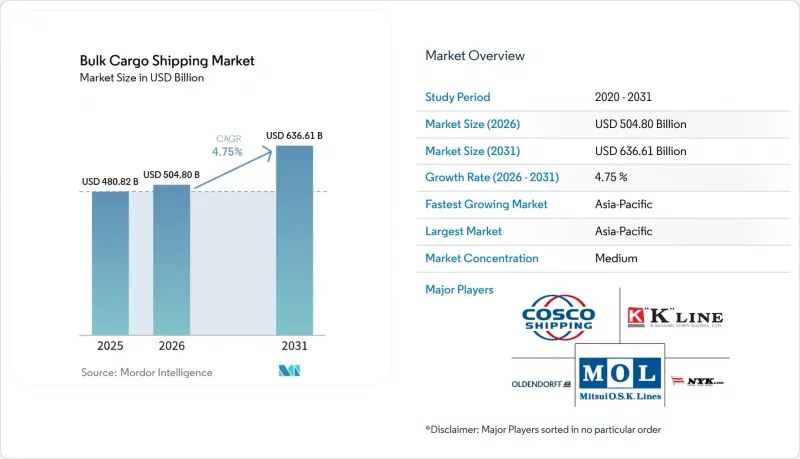
According to Mordor Intelligence, the bulk cargo shipping market size was valued at USD 480.82 billion in 2025 and is estimated to grow from USD 504.80 billion in 2026 to reach USD 636.61 billion by 2031 at 4.75% CAGR over 2026-2031.
Global Bulk Cargo Shipping Market Trends and Insights
Rising Seaborne Demand for Iron Ore and Coal
Seaborne iron ore remains a central source of cargo demand for the bulk cargo shipping market. Simandou's commercial ramp-up changed the origin mix for iron ore bound for China. The project reported monthly shipments above 2.2 million tonnes by May 2026. A Guinea-to-China voyage creates 4 times the tonne-miles of an equivalent Australian shipment. BIMCO expects longer average sailing distances to account for half of dry bulk ship demand growth in 2026, independent of changes in total cargo volumes. Coal trade declined as Indonesian exports contracted, but longer Atlantic-to-Asia routes can still support vessel utilization where buyers substitute supply origins.
Expansion of Grain and Fertilizer Trade Flows
Agricultural cargoes broaden demand beyond iron ore and coal in the bulk cargo shipping market. Seaborne agricultural trade reached 716.5 million tonnes in 2025. Grain shipments rose 15% year over year in the first 6 weeks of 2026 as South American surpluses increased exports. The Strait of Hormuz disruption halted a significant share of fertilizer movements and delayed urea, sulfur, and phosphate cargoes. The International Fertilizer Association expects constrained nitrogen availability during the 2026/27 crop cycle. When supply resumes, buyers drawing down inventories may return to the freight market at the same time, supporting Supramax and Panamax demand on agricultural routes.
Exposure to Dry Bulk Freight Rate Cyclicality
Freight rates remain vulnerable to the balance between vessel deliveries and cargo demand. The dry bulk orderbook-to-fleet ratio reached 11.0% in H1 2026, compared with 9.5% in H1 2025. The orderbook included 600 vessels scheduled for delivery during 2026. BIMCO forecasts ship supply growth of 2.8% in 2026, compared with ship demand growth of 1.5% to 2.5%. Panamax and Supramax fleets face greater exposure because they account for more than 60% of scheduled deliveries. Owners operating through long-term charters have greater protection than operators dependent on spot voyages.
Other drivers and restraints analyzed in the detailed report include:
- Fleet Efficiency Gains From Larger Bulk Carriers
- Port Automation and Digital Voyage Optimization
- Decarbonization Compliance and Fuel Transition Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Dry bulk cargo held 75.12% of 2025 revenue, giving it the largest position in the bulk cargo shipping market size. Iron ore and coal represented more than 52% of total bulk trade by volume and supported Capesize and Panamax employment on Australia-China and Brazil-China routes. The scale of these cargoes keeps dry bulk at the center of fleet utilization. Bauxite also adds to long-haul demand from West African origins. Grain provides a third major cargo stream and gives owners exposure to seasonal agricultural trade. The bulk cargo shipping market benefits because the segment's breadth helps protect operators from reliance on a single commodity.
Liquid bulk cargo is forecast to expand at a 6.17% CAGR from 2026 to 2031. Longer crude oil routes after the Hormuz disruption, new LNG liquefaction capacity, and Asian chemical tanker demand support this outlook. The shift indicates that energy and chemical flows are becoming more important to the broader bulk cargo shipping market. COSCO Shipping Bulk commissioned the YUAN HAI SI LU, described as the world's first 325,000-DWT methanol dual-fuel ore carrier. The vessel shows how cargo capacity and fuel-transition readiness can be combined in a single asset. Operators serving both dry and liquid trades can use diversified demand to manage route disruption.
Complete Report Scope:
- By Cargo Type
- Dry Bulk Cargo
- Iron Ore
- Coal
- Grain (Wheat, Corn, Soybeans, etc.)
- Fertilizers
- Cement and Clinker
- Bauxite and Alumina
- Steel Products
- Other Minor Dry Bulk Commodities
- Liquid Bulk Cargo
- Crude Oil
- Refined Petroleum Products
- Liquefied Natural Gas (LNG)
- Liquefied Petroleum Gas (LPG)
- Chemicals
- Edible and Vegetable Oils
- Molasses
- Other Liquid Bulk Commodities
- Dry Bulk Cargo
- By Shipping Route
- Domestic (Coastal)
- International
- By End-Use Industry
- Mining and Metals
- Energy and Utilities
- Agriculture
- Chemicals and Petrochemicals
- Construction and Infrastructure
- Food Processing
- Manufacturing (General Industrial)
- Others
- By Region/Country
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia-Pacific
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- Belgium
- Netherlands
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Egypt
- Rest of the Middle East and Africa
- North America
Geography Analysis
Asia-Pacific held 51.88% of 2025 revenue and is forecast to grow at a 5.63% CAGR through 2031. The region has the largest position in the Bulk cargo shipping market share because China remains the leading commodity importer. Australia is a major exporter of iron ore and coal, while China is a major destination for bulk cargoes. Simandou's development also gives Asian buyers a growing Atlantic supply route. Vietnam, Indonesia, and India broaden regional demand through industrialization, infrastructure programs, and coastal shipping reforms.
Europe and North America have different roles in the bulk cargo shipping market. For the bulk cargo shipping market, Europe is losing dry bulk import importance as coal phase-out policies reduce demand for seaborne steam coal. North America functions in the bulk cargo shipping market primarily as an exporter of grain and metallurgical coal to global markets. The Great Lakes and St. Lawrence Seaway also support regional industrial and construction commodity movements. South America, led by Brazil, is an important Atlantic source for grain and iron ore. Its position makes the Santos-to-Qingdao route important for Panamax activity and links agricultural output to Asian consumption.
The Middle East and Africa face opposing forces in 2026. The Hormuz closure disrupted Gulf crude and fertilizer cargo movements, while Saudi Arabia's East-West pipeline and Red Sea access provided partial alternatives. Africa is becoming a more important dry bulk export region through Simandou and expanding bauxite movements. Simandou is progressing toward 60 million tonnes of annual capacity. The movement of more cargo from Atlantic origins increases the role of Africa in the bulk cargo shipping market. Redirected energy flows also raise the importance of transit and trading hubs outside the disrupted corridor.
- Oldendorff Carriers
- COSCO Shipping Bulk Co., Ltd.
- NYK Line
- Mitsui O.S.K. Lines (MOL)
- Kawasaki Kisen Kaisha ("K" Line)
- Star Bulk Carriers Corp.
- CMB.TECH (Including Golden Ocean Group)
- Pacific Basin Shipping Ltd.
- Berge Bulk
- D/S NORDEN
- Ultrabulk A/S
- Genco Shipping and Trading Ltd.
- Diana Shipping Inc.
- Navios Maritime Partners L.P.
- Safe Bulkers Inc.
- Fednav Ltd.
- CSL Group
- Bahri
- Wisdom Marine Group
- Algoma Central Corporation
- Pangaea Logistics Solutions
- Lauritzen Bulkers
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview and Importance of Bulk Cargo Shipping
- 4.2 Market Drivers
- 4.2.1 Rising Seaborne Demand for Iron Ore and Coal
- 4.2.2 Expansion of Grain and Fertilizer Trade Flows
- 4.2.3 Fleet Efficiency Gains From Larger Bulk Carriers
- 4.2.4 Port Automation and Digital Voyage Optimization
- 4.2.5 Growth in Specialized Liquid Bulk Trade Corridors
- 4.2.6 Commodity Supply Re-Localization and Trade Diversion
- 4.3 Market Restraints
- 4.3.1 Exposure to Dry Bulk Freight Rate Cyclicality
- 4.3.2 Decarbonization Compliance and Fuel Transition Costs
- 4.3.3 Port Congestion and Draft Constraints at Key Terminals
- 4.3.4 Counterparty Risk in Commodity-Led Shipping Contracts
- 4.4 Industry Regulatory Framework
- 4.5 Value Chain and Distribution Channel Architecture Analysis
- 4.6 Technology Megatrends and Structural Shifts Bulk Cargo Shipping
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Rivalry Among Competitors
- 4.8 Freight Rate Analysis
- 4.8.1 Freight Rate Trends
- 4.8.2 Spot Market Analysis
- 4.8.3 Regional Freight Rate Comparison
- 4.8.4 Factors Influencing Freight Rates
- 4.9 Cost Structure Analysis
- 4.9.1 Shipping Cost Components
- 4.9.2 Fuel Cost Trends
- 4.9.3 Port Charges
- 4.9.4 Cost Optimization Strategies
- 4.10 Import-Export Trade Analysis
- 4.11 Port and Terminal Infrastructure Analysis
- 4.12 Sustainability and ESG Analysis
- 4.13 Impact of Geo-Political Events on Supply Chain Shifts
5 Market Size and Growth Forecasts (Value, 2026-2031)
- 5.1 By Cargo Type
- 5.1.1 Dry Bulk Cargo
- 5.1.1.1 Iron Ore
- 5.1.1.2 Coal
- 5.1.1.3 Grain (Wheat, Corn, Soybeans, etc.)
- 5.1.1.4 Fertilizers
- 5.1.1.5 Cement and Clinker
- 5.1.1.6 Bauxite and Alumina
- 5.1.1.7 Steel Products
- 5.1.1.8 Other Minor Dry Bulk Commodities
- 5.1.2 Liquid Bulk Cargo
- 5.1.2.1 Crude Oil
- 5.1.2.2 Refined Petroleum Products
- 5.1.2.3 Liquefied Natural Gas (LNG)
- 5.1.2.4 Liquefied Petroleum Gas (LPG)
- 5.1.2.5 Chemicals
- 5.1.2.6 Edible and Vegetable Oils
- 5.1.2.7 Molasses
- 5.1.2.8 Other Liquid Bulk Commodities
- 5.1.1 Dry Bulk Cargo
- 5.2 By Shipping Route
- 5.2.1 Domestic (Coastal)
- 5.2.2 International
- 5.3 By End-Use Industry
- 5.3.1 Mining and Metals
- 5.3.2 Energy and Utilities
- 5.3.3 Agriculture
- 5.3.4 Chemicals and Petrochemicals
- 5.3.5 Construction and Infrastructure
- 5.3.6 Food Processing
- 5.3.7 Manufacturing (General Industrial)
- 5.3.8 Others
- 5.4 By Region/Country
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Peru
- 5.4.2.3 Chile
- 5.4.2.4 Argentina
- 5.4.2.5 Rest of South America
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 South Korea
- 5.4.3.4 India
- 5.4.3.5 Australia
- 5.4.3.6 Southeast Asia
- 5.4.3.7 Rest of Asia-Pacific
- 5.4.4 Europe
- 5.4.4.1 United Kingdom
- 5.4.4.2 Germany
- 5.4.4.3 France
- 5.4.4.4 Spain
- 5.4.4.5 Italy
- 5.4.4.6 Belgium
- 5.4.4.7 Netherlands
- 5.4.4.8 NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- 5.4.4.9 Rest of Europe
- 5.4.5 Middle East and Africa
- 5.4.5.1 United Arab Emirates
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 South Africa
- 5.4.5.4 Nigeria
- 5.4.5.5 Egypt
- 5.4.5.6 Rest of the Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Key Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Geographic/Network Coverage, Products & Services, and Recent Developments)
- 6.4.1 Oldendorff Carriers
- 6.4.2 COSCO Shipping Bulk Co., Ltd.
- 6.4.3 NYK Line
- 6.4.4 Mitsui O.S.K. Lines (MOL)
- 6.4.5 Kawasaki Kisen Kaisha ("K" Line)
- 6.4.6 Star Bulk Carriers Corp.
- 6.4.7 CMB.TECH (Including Golden Ocean Group)
- 6.4.8 Pacific Basin Shipping Ltd.
- 6.4.9 Berge Bulk
- 6.4.10 D/S NORDEN
- 6.4.11 Ultrabulk A/S
- 6.4.12 Genco Shipping and Trading Ltd.
- 6.4.13 Diana Shipping Inc.
- 6.4.14 Navios Maritime Partners L.P.
- 6.4.15 Safe Bulkers Inc.
- 6.4.16 Fednav Ltd.
- 6.4.17 CSL Group
- 6.4.18 Bahri
- 6.4.19 Wisdom Marine Group
- 6.4.20 Algoma Central Corporation
- 6.4.21 Pangaea Logistics Solutions
- 6.4.22 Lauritzen Bulkers
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

