PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155640

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155640
Europe Bulk Cargo Shipping - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
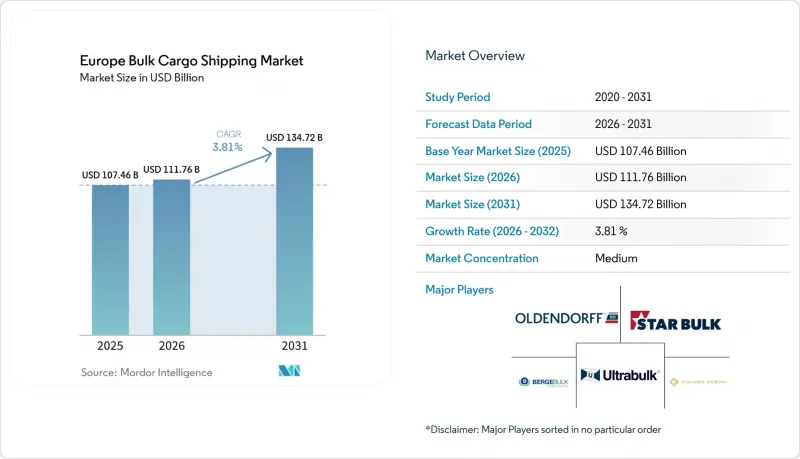
According to Mordor Intelligence, the European bulk cargo shipping market size was valued at USD 107.46 billion in 2025 and is estimated to grow from USD 111.76 billion in 2026 to reach USD 134.72 billion by 2031, at a CAGR of 3.81% during the forecast period (2026-2031).
Europe Bulk Cargo Shipping Market Trends and Insights
Energy Transition Cargo Rebalancing, Especially Biomass, LNG, Fertilizers, and Steel Inputs
European energy supply changes have altered the cargo mix used by major bulk routes. Rotterdam handled 13 million tons of LNG in 2025, a 15.1% increase from 2024, as regional buyers rebuilt gas stocks. Biomass, green-hydrogen feedstocks, and fertilizers are increasingly relevant cargoes as coal volumes decline. The European Commission states that the Alternative Fuels Infrastructure Regulation supports the deployment of alternative-fuel infrastructure in transport networks. The European bulk cargo shipping market, therefore, needs vessel capacity that can serve different cargo specifications and changing trade lanes. Open-hatch bulkers, smaller LNG carriers, and combination vessels can address parts of this shifting demand.
Nearshoring of Industrial Input Flows through European Bulk Corridors
European manufacturers are placing more attention on shorter and more resilient sourcing routes. This approach supports cargo movements between industrial hubs, ports, and inland distribution points across Europe. The European bulk cargo shipping market benefits when relocated production requires regular deliveries of iron ore, fertilizers, aggregates, and chemicals. Poland and other Central and Eastern European locations can receive more industrial inputs through Baltic and North Sea connections. More intra-European freight can raise the value of reliable short-sea schedules and connected terminal operations. This creates an opening for carriers that can coordinate sea, rail, and inland-waterway services.
High Compliance Cost from EU Emissions, Fuel, and Reporting Rules
The EU Emissions Trading System began covering maritime transport in January 2024. FuelEU Maritime applied from January 2025 to ships above 5,000 GT calling at European Economic Area ports. The regulation required a 2% reduction in greenhouse-gas intensity in 2025, with a more stringent pathway through 2050. Operators need fuel records, emissions information, and reporting systems that satisfy both regulatory and commercial requirements. Smaller short-sea operators can face a heavier administrative burden because they have fewer resources to spread these fixed costs. The European bulk cargo shipping market may consequently place a higher premium on fleets with established compliance processes.
Other drivers and restraints analyzed in the detailed report include:
- Inland-Waterway and Short-Sea Modal Shift to Reduce Truck Congestion and Emissions
- Port Decarbonization Incentives Favoring Cleaner Bulk Vessel Deployment
- Port Congestion and Labor Intermittency Disrupting Voyage Reliability
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Dry bulk cargo was the core of the Europe bulk cargo shipping market size in 2025, accounting for 62.63% of the market share, with industrial and agricultural supply chains depending on iron ore, grain, fertilizers, cement, and steel products. Northern European steelmakers still require iron ore and coking coal even as steel demand changes. EU apparent steel consumption declined 0.2% in 2025, following weakness in manufacturing and construction. EUROFER projected a 3.1% recovery by the end of 2026, subject to stronger industrial output and less geopolitical pressure. Rotterdam recorded a 17.8% increase in coal throughput during the first half of 2026 as higher gas prices affected energy purchasing. Biomass pellets, offshore-wind aggregates, and sustainable raw materials provide a partial offset to lower coal volumes. Carriers need flexible stowage, cargo-handling methods, and route planning because these cargoes have different loading and discharge needs. These supply chains continue to make dry bulk a broad operational base for European ports. Cargo owners also depend on predictable discharge windows when industrial plants and storage sites run close to scheduled inventory levels. Terminal operators must retain equipment and workforce capability for dense cargoes, seasonal agricultural volumes, and specialized minor bulks. The combination makes fleet deployment less uniform across ports, even when the underlying cargo demand is stable.
Liquid bulk cargo is projected to be the fastest-growing cargo category through 2031, expanding at a 5.23% CAGR, supported by LNG trade, refined petroleum products, and expanding chemical manufacturing across Europe. Rotterdam's LNG throughput rose 15.1% to 13 million tons in 2025. This increase reflects the need for gas import capacity as European energy sourcing changes. Liquid cargo also needs specialized tanks, terminals, safety systems, and cargo documentation. Van Moer Logistics opened 63 polymer silos at Waaslandhaven in June 2026 as the first phase of a EUR 185 million (USD 217.62 million) program. The investment showed continued confidence in chemical-cluster storage and handling capacity. Diversified food imports also sustain traffic in edible oils and molasses. The wider mix gives terminal operators more opportunities, but it requires closer control of product quality, storage, and vessel turnaround. Dedicated infrastructure can reduce handling conflicts between cargoes with different contamination, temperature, and safety requirements. Commercial success, therefore, depends on matching vessel calls with storage availability and downstream customer demand.
Complete Report Scope:
- By Cargo Type
- Dry Bulk Cargo
- Iron Ore
- Coal
- Grain (Wheat, Corn, Soybeans, etc.)
- Fertilizers
- Cement & Clinker
- Bauxite & Alumina
- Steel Products
- Other Minor Dry Bulk Commodities
- Liquid Bulk Cargo
- Crude Oil
- Refined Petroleum Products
- Liquefied Natural Gas (LNG)
- Liquefied Petroleum Gas (LPG)
- Chemicals
- Edible & Vegetable Oils
- Molasses
- Other Liquid Bulk Commodities
- Dry Bulk Cargo
- By Shipping Route
- Domestic (Coastal)
- International
- By End-Use Industry
- Mining & Metals
- Energy & Utilities
- Agriculture
- Chemicals & Petrochemicals
- Construction & Infrastructure
- Food Processing
- Manufacturing (General Industrial)
- Others
- By Country
- United Kingdom
- Germany
- France
- Spain
- Italy
- Belgium
- Netherlands
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
List of Companies Covered in this Report:
- Oldendorff Carriers
- Ultrabulk A/S
- Star Bulk Carriers
- Golden Ocean Group
- Berge Bulk
- Gearbulk
- Fednav
- Spliethoff Group
- Wagenborg Shipping
- Western Bulk
- SAL Heavy Lift
- Torvald Klaveness
- NORDEN
- Wilson ASA
- Grieg Maritime Group
- Briese Group
- AAL Shipping
- VARAMAR
- MACS Maritime Carrier Shipping
- SMT Shipping
- Diana Shipping
- Cobelfret
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview and Importance of Bulk Cargo Shipping
- 4.2 Market Drivers
- 4.2.1 Nearshoring of Industrial Input Flows Through European Bulk Corridors
- 4.2.2 Replacement Demand from Aging Short-Sea and Feeder Dry Bulk Fleets
- 4.2.3 Port Decarbonization Incentives Favoring Cleaner Bulk Vessel Deployment
- 4.2.4 Energy Transition Cargo Rebalancing, Especially Biomass, LNG, Fertilizers, and Steel Inputs
- 4.2.5 Inland-Waterway and Short-Sea Modal Shift to Reduce Truck Congestion and Emissions
- 4.2.6 Digital Berth Scheduling and Cargo Visibility Improving Vessel Utilization
- 4.3 Market Restraints
- 4.3.1 High Compliance Cost from EU Emissions, Fuel, And Reporting Rules
- 4.3.2 Port Congestion and Labor Intermittency Disrupting Voyage Reliability
- 4.3.3 Demand Volatility from Cyclical Steel, Fertilizer, and Power Markets
- 4.3.4 Limited Terminal Draft, Storage, and Transshipment Capacity in Select European Ports
- 4.4 Industry Regulatory Framework
- 4.5 Value Chain and Distribution Channel Architecture Analysis
- 4.6 Technology Megatrends and Structural Shifts Bulk Cargo Shipping
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Rivalry Among Competitors
- 4.8 Freight Rate Analysis
- 4.8.1 Freight Rate Trends
- 4.8.2 Spot Market Analysis
- 4.8.3 Country-wise Freight Rate Comparison
- 4.8.4 Factors Influencing Freight Rates
- 4.9 Cost Structure Analysis
- 4.9.1 Shipping Cost Components
- 4.9.2 Fuel Cost Trends
- 4.9.3 Port Charges
- 4.9.4 Cost Optimization Strategies
- 4.10 Import-Export Trade Analysis
- 4.11 Port and Terminal Infrastructure Analysis
- 4.12 Sustainability and ESG Analysis
- 4.13 Impact of Geo-Political Events on Supply Chain Shifts
5 Market Size & Growth Forecasts (Value, 2026-2031)
- 5.1 By Cargo Type
- 5.1.1 Dry Bulk Cargo
- 5.1.1.1 Iron Ore
- 5.1.1.2 Coal
- 5.1.1.3 Grain (Wheat, Corn, Soybeans, etc.)
- 5.1.1.4 Fertilizers
- 5.1.1.5 Cement & Clinker
- 5.1.1.6 Bauxite & Alumina
- 5.1.1.7 Steel Products
- 5.1.1.8 Other Minor Dry Bulk Commodities
- 5.1.2 Liquid Bulk Cargo
- 5.1.2.1 Crude Oil
- 5.1.2.2 Refined Petroleum Products
- 5.1.2.3 Liquefied Natural Gas (LNG)
- 5.1.2.4 Liquefied Petroleum Gas (LPG)
- 5.1.2.5 Chemicals
- 5.1.2.6 Edible & Vegetable Oils
- 5.1.2.7 Molasses
- 5.1.2.8 Other Liquid Bulk Commodities
- 5.1.1 Dry Bulk Cargo
- 5.2 By Shipping Route
- 5.2.1 Domestic (Coastal)
- 5.2.2 International
- 5.3 By End-Use Industry
- 5.3.1 Mining & Metals
- 5.3.2 Energy & Utilities
- 5.3.3 Agriculture
- 5.3.4 Chemicals & Petrochemicals
- 5.3.5 Construction & Infrastructure
- 5.3.6 Food Processing
- 5.3.7 Manufacturing (General Industrial)
- 5.3.8 Others
- 5.4 By Country
- 5.4.1 United Kingdom
- 5.4.2 Germany
- 5.4.3 France
- 5.4.4 Spain
- 5.4.5 Italy
- 5.4.6 Belgium
- 5.4.7 Netherlands
- 5.4.8 NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- 5.4.9 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Key Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Geographic/Network Coverage, Products & Services, and Recent Developments)
- 6.4.1 Oldendorff Carriers
- 6.4.2 Ultrabulk A/S
- 6.4.3 Star Bulk Carriers
- 6.4.4 Golden Ocean Group
- 6.4.5 Berge Bulk
- 6.4.6 Gearbulk
- 6.4.7 Fednav
- 6.4.8 Spliethoff Group
- 6.4.9 Wagenborg Shipping
- 6.4.10 Western Bulk
- 6.4.11 SAL Heavy Lift
- 6.4.12 Torvald Klaveness
- 6.4.13 NORDEN
- 6.4.14 Wilson ASA
- 6.4.15 Grieg Maritime Group
- 6.4.16 Briese Group
- 6.4.17 AAL Shipping
- 6.4.18 VARAMAR
- 6.4.19 MACS Maritime Carrier Shipping
- 6.4.20 SMT Shipping
- 6.4.21 Diana Shipping
- 6.4.22 Cobelfret
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

