PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155681

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155681
South America Domestic CEP - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
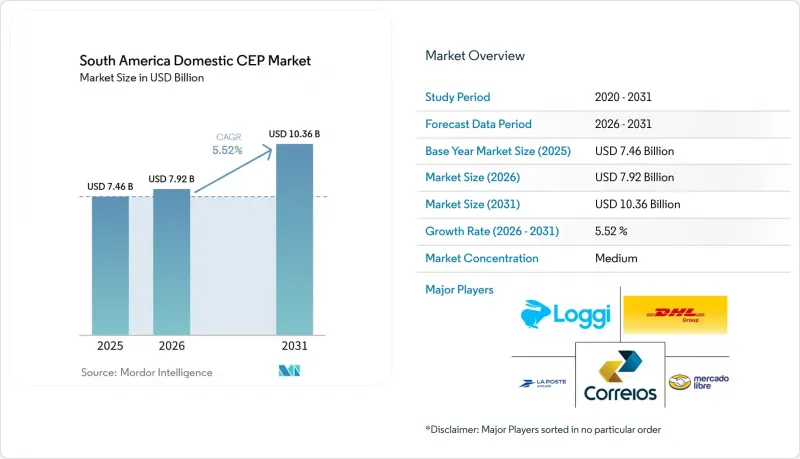
According to Mordor Intelligence, the South America domestic CEP market size was valued at USD 7.46 billion in 2025 and is estimated to grow from USD 7.92 billion in 2026 to reach USD 10.36 billion by 2031, at a CAGR of 5.52% during the forecast period (2026-2031).
South America Domestic CEP Market Trends and Insights
E-Commerce Parcel Density and Marketplace Fulfillment Expansion
E-commerce remained the primary source of domestic parcel demand across the South America domestic CEP market. MercadoLibre processed 95 orders per second in the fourth quarter of 2025 and delivered 75% of Brazilian orders within 48 hours after expanding to 27 fulfillment centers. The company announced an investment plan for 2026 targeting 42 distribution centers, and indicating continued expansion of marketplace fulfillment capacity. Shopee opened 3 fulfillment centers in 2026, and its fulfillment-network order volume increased 15 times over the preceding 12 months. Loggi reported that PUDO point use among Brazilian small and medium-sized businesses increased 53% year over year in the first half of 2026. Platform investment shifted more responsibility for network capacity from carriers to marketplaces, making carrier access to volume more dependent on digital and operational integration.
Instant-Payment Adoption Enabling Faster Order Release
Brazil's Pix system processed nearly 80 billion transactions in 2025, up 25.7% from 2024, while consumer-to-business payments represented 43% of its transactions. Immediate confirmation removed reconciliation delays that had previously held orders before dispatch. DHL Express Brazil integrated Pix processing with dLocal in February 2026, and its Pix payment volume increased 400% after the integration. DHL also reported a 31% rise in its online payment rate and shorter parcel release times. Ebanx plans Pix to account for 45% of Brazil's online sales by the end of 2026, compared with 42% in 2025. Payment systems in Colombia and Chile could support comparable improvements, although their adoption curves were expected to follow Brazil's later.
Fuel-Price, Tax, and Currency Volatility
A supply disruption in early 2026 raised oil costs and lifted diesel prices in Brazil by more than 20%. Brazil's ANTT required minimum road freight rate increases of 4.8% to 7%, but diesel remained a major cost for long-haul carriers. Chile also faced sharp fuel-price increases after its fuel-stabilization scheme was wound down. Operators with net margins of 3% to 7% had limited capacity to absorb these changes. Currency movements in Argentina raised the cost of imported inputs for providers earning local-currency revenue. Smaller carriers faced greater consolidation pressure where contracts lacked fuel or inflation protection.
Other drivers and restraints analyzed in the detailed report include:
- Same-Day and Next-Day Delivery Expectations in Major Urban Corridors
- Dark-Store and Micro-Fulfillment Expansion
- Road Quality, Congestion, and Remote-Area Delivery Constraints
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Non-express services held 77.40% of the South America domestic CEP market share in 2025. Economy shipping suited cost-sensitive consumers and supply chains that placed greater weight on total freight expense than speed. This revenue base helped carriers build route density and retain broad network coverage. The scale of these flows also supported the economics of faster services on common routes. It gave providers a broad shipment base from which to develop higher-speed products.
Express delivery was forecast to grow at a 6.44% CAGR from 2026 to 2031. Demand for shorter delivery windows was spreading from the largest Brazilian cities toward secondary cities and neighboring countries. MercadoLibre's 48-hour performance in 2025 illustrated the service standard that platform operations were setting. Express adoption was likely to remain strongest in dense urban areas where delivery volumes could support the required cost base. Smaller cities were expected to retain a greater reliance on non-express services. This difference required providers to manage separate service models within the same network.
B2C accounted for 53.17% of the South America domestic CEP market size in 2025. It was also the fastest-growing business model, with a forecast CAGR of 6.61% through 2031. Consumer e-commerce created steady parcel demand across a growing base of small online sellers. Pix reduced checkout friction and shortened the time needed to release paid orders to the delivery network. It also increased the importance of dependable real-time data exchange between sellers and carriers.
B2B continued to support parts replenishment, industrial distribution, and document transport. Its relative contribution was under pressure as digital procurement and marketplace fulfillment replaced some traditional wholesale flows. C2C services were supported by resale platforms and gig-delivery applications, although they remained smaller and had lower revenue per parcel. Consumer returns created an additional operating requirement under Brazil's Consumer Defense Code. Carriers needed to price return movements accurately to protect B2C profitability. These operational needs made consumer channels more demanding than simple outbound delivery volumes suggested.
Complete Report Scope:
- By Speed of Delivery
- Express
- Non-Express
- By Business Model
- Business-to-Business (B2B)
- Business-to-Consumer (B2C)
- Consumer-to-Consumer (C2C)
- By Shipment Weight
- Light-Weight Shipments
- Medium-Weight Shipments
- Heavy-Weight Shipments
- By Mode of Transport
- Air
- Road
- Others
- By End-User Industry
- E-Commerce
- Financial Services (BFSI)
- Healthcare
- Manufacturing
- Primary Industry
- Wholesale and Retail Trade (Offline)
- Others
- By Country
- Argentina
- Brazil
- Chile
- Colombia
- Peru
- Rest of South America
List of Companies Covered in this Report:
- Empresa Brasileira de Correios e Telegrafos
- MercadoLibre, Inc.
- Loggi Tecnologia Ltda.
- Total Express
- La Poste Group (Including DPD Group)
- DHL Group
- FedEx
- United Parcel Service of America, Inc. (UPS)
- Azul Linhas Aereas Brasileiras S.A.
- GOL Linhas Aereas S.A.
- Braspress Transportes Urgentes Ltda.
- Jamef Transportes Ltda.
- Rodonaves Transportes e Encomendas Ltda.
- Sequoia Logistica e Transportes S.A.
- Grupo Logistico Andreani
- Correo Argentino
- Chilexpress S.A.
- Correos de Chile
- Patrus Transportes
- DSV A/S
- Alfa Transportes
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Key Macroeconomic Factors (GDP, Inflation, etc.) and their Impact on the Market
- 4.3 Market Drivers
- 4.3.1 E-Commerce Parcel Density and Marketplace Fulfillment Expansion
- 4.3.2 Instant-Payment Adoption Enabling Faster Order Release
- 4.3.3 Same-Day and Next-Day Delivery Expectations in Major Urban Corridors
- 4.3.4 Transport-Corridor and Multimodal Infrastructure Investment
- 4.3.5 Dark-Store and Micro-Fulfillment Expansion
- 4.3.6 Healthcare, Perishables and Temperature-Controlled Parcel Demand
- 4.4 Market Restraints
- 4.4.1 Fuel-Price, Tax and Currency Volatility
- 4.4.2 Road Quality, Congestion and Remote-Area Delivery Constraints
- 4.4.3 Parcel-Theft, Fraud and Security Costs
- 4.4.4 Battery-Cell Availability and Electrification Readiness
- 4.5 Value Chain and Distribution Channel Analysis
- 4.6 Regulatory Framework
- 4.7 Technological Outlook
- 4.8 E-commerce Industry Performance and Profile
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Threat of New Entrants
- 4.9.2 Bargaining Power of Suppliers
- 4.9.3 Bargaining Power of Buyers
- 4.9.4 Threat of Substitutes
- 4.9.5 Competitive Rivalry
- 4.10 Impact of Geopolitical Events on the Market
5 MARKET SIZE AND GROWTH FORECASTS (Value, USD)
- 5.1 By Speed of Delivery
- 5.1.1 Express
- 5.1.2 Non-Express
- 5.2 By Business Model
- 5.2.1 Business-to-Business (B2B)
- 5.2.2 Business-to-Consumer (B2C)
- 5.2.3 Consumer-to-Consumer (C2C)
- 5.3 By Shipment Weight
- 5.3.1 Light-Weight Shipments
- 5.3.2 Medium-Weight Shipments
- 5.3.3 Heavy-Weight Shipments
- 5.4 By Mode of Transport
- 5.4.1 Air
- 5.4.2 Road
- 5.4.3 Others
- 5.5 By End-User Industry
- 5.5.1 E-Commerce
- 5.5.2 Financial Services (BFSI)
- 5.5.3 Healthcare
- 5.5.4 Manufacturing
- 5.5.5 Primary Industry
- 5.5.6 Wholesale and Retail Trade (Offline)
- 5.5.7 Others
- 5.6 By Country
- 5.6.1 Argentina
- 5.6.2 Brazil
- 5.6.3 Chile
- 5.6.4 Colombia
- 5.6.5 Peru
- 5.6.6 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Key Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Geographic Coverage, Products and Services, Recent Developments)
- 6.4.1 Empresa Brasileira de Correios e Telegrafos
- 6.4.2 MercadoLibre, Inc.
- 6.4.3 Loggi Tecnologia Ltda.
- 6.4.4 Total Express
- 6.4.5 La Poste Group (Including DPD Group)
- 6.4.6 DHL Group
- 6.4.7 FedEx
- 6.4.8 United Parcel Service of America, Inc. (UPS)
- 6.4.9 Azul Linhas Aereas Brasileiras S.A.
- 6.4.10 GOL Linhas Aereas S.A.
- 6.4.11 Braspress Transportes Urgentes Ltda.
- 6.4.12 Jamef Transportes Ltda.
- 6.4.13 Rodonaves Transportes e Encomendas Ltda.
- 6.4.14 Sequoia Logistica e Transportes S.A.
- 6.4.15 Grupo Logistico Andreani
- 6.4.16 Correo Argentino
- 6.4.17 Chilexpress S.A.
- 6.4.18 Correos de Chile
- 6.4.19 Patrus Transportes
- 6.4.20 DSV A/S
- 6.4.21 Alfa Transportes
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

