PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2156876

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2156876
Digital Insurance Brokerage - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
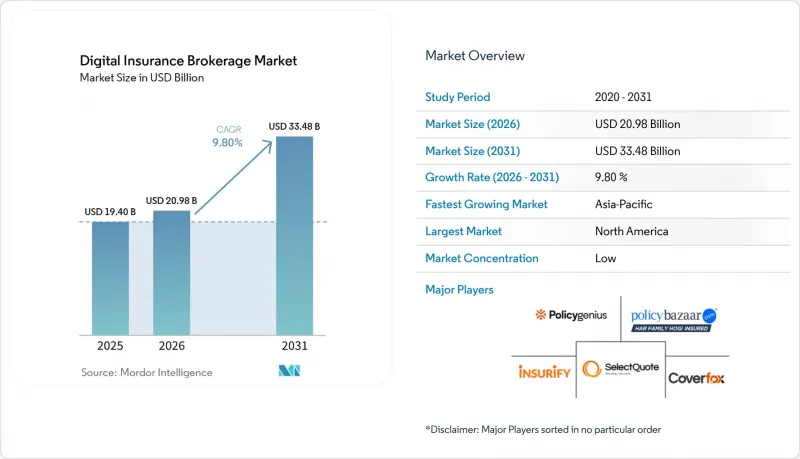
According to Mordor Intelligence, the digital insurance brokerage market size is expected to grow from USD 19.40 billion in 2025 to USD 20.98 billion in 2026 and is forecast to reach USD 33.48 billion by 2031 at 9.80% CAGR over 2026-2031.
Global Digital Insurance Brokerage Market Trends and Insights
Growing Consumer Adoption of Digital Insurance Comparison and Self-Service Purchasing
Self-service purchasing has moved beyond a niche activity for many insurance customers. In Europe, online sales accounted for 9% of life insurance premiums and 19% of non-life premiums, while non-life digital penetration exceeded 10% in Germany, the Czech Republic, France, Hungary, and Latvia. These figures show that online distribution is established in standardized lines, although adoption remains uneven across countries and products. India's online share of new policies rose from 9.2% in fiscal 2024 to 13.5% in fiscal 2026, supported by smartphone use and digital payment infrastructure. The digital insurance brokerage market benefits when customers become accustomed to comparing motor and travel policies online before considering health and life coverage. This pattern can extend digital demand into products that have historically required more support during purchase.
Expansion of API-Led Embedded and Partner-Based Insurance Distribution
Insurance is increasingly offered within non-insurance digital platforms at the point where customers make related purchases. Bolttech connected 700 distribution partners with more than 230 insurers across over 6,500 products in 2025. Cover Genius had deployed 240 million policies across more than 60 countries and reported 50% revenue growth in 2025. These models can reduce acquisition costs by reaching customers when a purchase creates a clear insurance need. The digital insurance brokerage market, therefore, faces a change in distribution, as coverage shifts from a product customers actively seek to an option presented in context. Brokers that want to remain relevant in standard personal and SME lines need API capabilities alongside traditional advisory services.
Data Privacy, Cybersecurity, and Regulatory Compliance Complexity
Digital brokers must manage several regulatory requirements when they collect, process, and use policyholder data. The Digital Operational Resilience Act took effect on January 17, 2025, adding information and communication technology risk, third-party oversight, and incident-reporting obligations for European insurance entities. The EU AI Act introduced high-risk obligations in August 2026 for relevant AI uses, including standards for data governance, transparency, and human oversight. Japan's APPI and Singapore's PDPA also place stringent obligations on platforms that handle policyholder data across borders. These obligations increase costs for participants without dedicated governance and regulatory teams. The digital insurance brokerage market can therefore favor larger, well-capitalized platforms that can absorb compliance and security investment.
Other drivers and restraints analyzed in the detailed report include:
- AI-Enabled Personalization and Automation of the Digital Brokerage Journey
- Increasing SME Demand for Faster Digital Quote, Comparison, and Policy Placement
- Legacy Carrier Systems and Limited Interoperability Across Insurance Ecosystems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Motor and auto insurance captured 28.1% of the digital insurance brokerage market share in 2025, supported by standardized coverage, price sensitivity, and broad consumer demand. These characteristics allow customers to compare policies on a more consistent basis than complex commercial or life products. Motor insurance also gives digital platforms an effective entry point for building customer relationships across renewals. This relationship can create opportunities to offer connected home, travel, health, or roadside products over time. Clear product features and recurring renewal cycles also make motor coverage a practical testing ground for digital service features. Life and annuity insurance and health and accident insurance have lower online penetration because underwriting and suitability needs are more involved. In Europe, life insurance online sales accounted for 9% of premiums in the EIOPA assessment published in March 2026.
Specialty insurance is projected to grow at a 14.9% CAGR from 2026 to 2031, making it the fastest-growing insurance line in the digital insurance brokerage market. Standardized cyber-risk scoring and parametric triggers are making selected specialty products easier to quote and place digitally. Property insurance is also moving toward digital quotation through LLM-integrated tools introduced by Aviva in March 2026 and Liberty Mutual in June 2026. Travel insurance continues to achieve strong digital conversion because it is short-duration and usually tied to a clear event. Liability insurance remains between standardized personal coverage and fully customized placement. The digital insurance brokerage market size is supported by this expansion of digitally accessible products, although complex risks still require greater human involvement.
Complete Report Scope:
- By Insurance Line
- Life and Annuity Insurance
- Health and Accident Insurance
- Motor/Auto Insurance
- Property Insurance
- Liability Insurance
- Travel Insurance
- Specialty Insurance
- By Placement Role
- Retail Digital Brokerage
- Wholesale and Specialist Digital Brokerage
- By Customer Segment
- Individual Consumers
- Small and Medium-Sized Businesses
- Large Corporates and Enterprises
- Public-Sector and Institutional Organizations
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Indonesia
- Thailand
- Malaysia
- Singapore
- Vietnam
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Turkey
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
North America held 42.7% of the digital insurance brokerage market share in 2025, supported by private capital availability, a fragmented carrier base, and established online distribution rules. Consumer-facing aggregators have developed strong positions in personal insurance, where neutral comparison is widely used. Mid-market commercial and excess and surplus lines remain less digitized than personal lines. Bolt's Connected Distribution platform, launched in August 2026, directly targets admitted, excess and surplus, and wholesale markets. Canada and Mexico add to regional activity, although differences in regulation and lower online insurance penetration limit their contribution. The digital insurance brokerage market size is supported by opportunities to digitize SME and commercial lines as wholesale APIs and quote workflows improve.
Europe is the second-largest region for the digital insurance brokerage market and has established comparison platforms in the United Kingdom, Germany, and France. Compare the Market, MoneySuperMarket, Go.Compare, CHECK24, and LeLynx.fr illustrate the region's developed personal motor and home comparison ecosystem. EIOPA reported that cross-border insurance distribution passports increased 10% from 24,036 in 2022 to 26,502 in 2024. The same report showed that online non-life sales ranged from less than 3% to more than 10% of gross written premiums across member states. Italy and Spain remain opportunities for embedded and mobile-first brokerage models. The United Kingdom's Consumer Duty and European compliance requirements under DORA, GDPR, and the AI Act raise operational demands but also support platforms with established governance processes.
Asia-Pacific is expected to grow at a 14.6% CAGR from 2026 to 2031, making it the fastest-growing geography in the digital insurance brokerage market. Growth is supported by underinsurance gaps, mobile-first consumer behavior, and regulatory liberalization in India, China, and Southeast Asia. The region's needs differ from those in mature Western markets because many consumers engage first through mobile applications and partner platforms. India's PB Fintech reported 40% revenue growth in the first quarter of fiscal 2027 as its addressable online shelf expanded through approved micro-insurance products. Southeast Asia offers a strong embedded-distribution opportunity because of low insurance penetration and a mobile-native population. South America, the Middle East, and Africa remain smaller markets, although mobile-enabled microinsurance products in Sub-Saharan Africa rose from 135 in 2020 to 282 in 2025. Policybazaar's June 2026 incorporation of DIFC-licensed subsidiaries also highlights the Middle East's role as a developing regulatory base for digital brokerage and reinsurance activity.
- Policybazaar
- Coverfox
- Policygenius
- Insurify
- SelectQuote
- The Zebra
- eHealth
- Huize
- EverQuote
- Compare the Market
- MoneySuperMarket
- Go.Compare
- CHECK24
- LeLynx.fr
- wefox
- BIMA
- Cover Genius
- bolttech
- Policy Expert
- Quotezone
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Consumer Adoption of Digital Insurance Comparison and Self-Service Purchasing
- 4.2.2 Expansion of API-Led Embedded and Partner-Based Insurance Distribution
- 4.2.3 AI-Enabled Personalization and Automation of the Digital Brokerage Journey
- 4.2.4 Increasing SME Demand for Faster Digital Quote, Comparison, and Policy Placement
- 4.2.5 Mobile-Led Expansion of Digital Insurance Access in Underpenetrated Markets
- 4.2.6 Emergence of Conversational and Agentic AI as a New Digital Brokerage Interface
- 4.3 Market Restraints
- 4.3.1 Data Privacy, Cybersecurity, and Regulatory Compliance Complexity
- 4.3.2 Legacy Carrier Systems and Limited Interoperability Across Insurance Ecosystems
- 4.3.3 Consumer Trust and Explainability Concerns in AI-Assisted Insurance Recommendations
- 4.3.4 Margin Pressure from Rising Digital Customer-Acquisition Costs and Channel Competition
- 4.4 Value Chain Analysis
- 4.4.1 Insurance Carriers and Underwriting Capacity Providers
- 4.4.2 Digital Brokerage, Comparison, and Distribution Platforms
- 4.4.3 Technology, Data, and Transaction Infrastructure Providers
- 4.5 Regulatory Landscape
- 4.5.1 Insurance Intermediary Licensing, Distribution, and Conduct Requirements
- 4.5.2 Consumer Protection, Data Privacy, and Digital Consent Requirements
- 4.5.3 AI Governance and Digital Insurance Interoperability Frameworks
- 4.6 Technological Outlook
- 4.6.1 AI-Powered Personalization, Recommendation, and Conversational Brokerage
- 4.6.2 API-First Connectivity and Embedded Insurance Enablement
- 4.6.3 Cloud-Based Automation, Digital Identity, and Real-Time Data Integration
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Insurance Line
- 5.1.1 Life and Annuity Insurance
- 5.1.2 Health and Accident Insurance
- 5.1.3 Motor/Auto Insurance
- 5.1.4 Property Insurance
- 5.1.5 Liability Insurance
- 5.1.6 Travel Insurance
- 5.1.7 Specialty Insurance
- 5.2 By Placement Role
- 5.2.1 Retail Digital Brokerage
- 5.2.2 Wholesale and Specialist Digital Brokerage
- 5.3 By Customer Segment
- 5.3.1 Individual Consumers
- 5.3.2 Small and Medium-Sized Businesses
- 5.3.3 Large Corporates and Enterprises
- 5.3.4 Public-Sector and Institutional Organizations
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 United Kingdom
- 5.4.3.2 Germany
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Australia
- 5.4.4.6 Indonesia
- 5.4.4.7 Thailand
- 5.4.4.8 Malaysia
- 5.4.4.9 Singapore
- 5.4.4.10 Vietnam
- 5.4.4.11 Rest of Asia-Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Turkey
- 5.4.5.4 South Africa
- 5.4.5.5 Egypt
- 5.4.5.6 Rest of Middle East and Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis (Top 5-6 players)
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Policybazaar
- 6.4.2 Coverfox
- 6.4.3 Policygenius
- 6.4.4 Insurify
- 6.4.5 SelectQuote
- 6.4.6 The Zebra
- 6.4.7 eHealth
- 6.4.8 Huize
- 6.4.9 EverQuote
- 6.4.10 Compare the Market
- 6.4.11 MoneySuperMarket
- 6.4.12 Go.Compare
- 6.4.13 CHECK24
- 6.4.14 LeLynx.fr
- 6.4.15 wefox
- 6.4.16 BIMA
- 6.4.17 Cover Genius
- 6.4.18 bolttech
- 6.4.19 Policy Expert
- 6.4.20 Quotezone
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
- 7.1.1 Digital Access and Inclusion for Underserved and Underinsured Customer Segments
- 7.1.2 Digitally Simplified and Affordable Insurance Solutions for Emerging Customer Needs
- 7.1.3 Digitally Efficient SME and Complex Commercial Insurance Placement
- 7.2 Future Outlook
- 7.2.1 AI-Native and Conversational Insurance Discovery and Brokerage
- 7.2.2 Real-Time, API-Enabled Insurance Distribution and Transaction Infrastructure
- 7.2.3 Hybrid, Embedded, and Cross-Border Digital Brokerage Models

