PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2157118

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2157118
North America Metal Forming Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the North America metal forming equipment market size is projected to expand from USD 3.46 billion in 2025 and USD 3.60 billion in 2026 to USD 4.18 billion by 2031, registering a CAGR of 3.03% between 2026 and 2031.
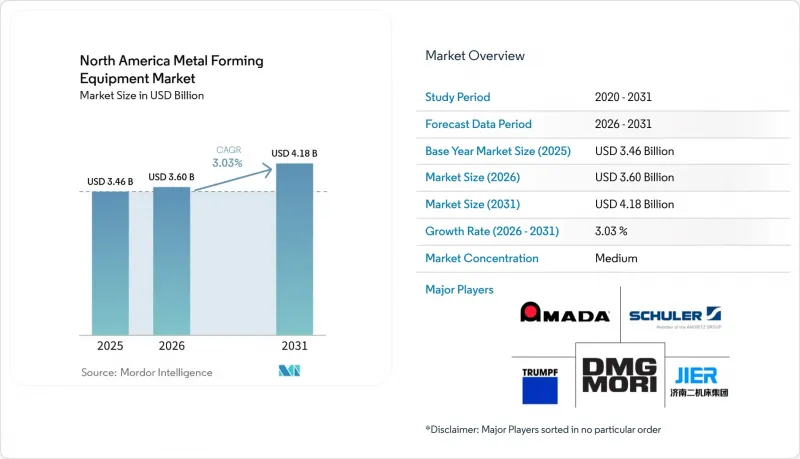
North America Metal Forming Equipment Market Trends and Insights
Reshoring and Nearshoring of Metal-Intensive Manufacturing
Reshoring is supporting capital spending on forming equipment in the region. The Reshoring Initiative reported 244,000 United States manufacturing jobs announced through reshoring and foreign direct investment in 2024. It also reported that fabricated metals announcements increased 19% in 2025. Its 2026 survey found that 63% of responding OEMs plan United States capital investment in 2026 or 2027 for reshoring or domestic expansion. New facilities commonly require larger presses, material handling, and integrated controls than the equipment they replace. The North America metal forming equipment market benefits when greenfield projects specify higher levels of automation and documented quality controls from the start.
Electrification and Battery-Component Manufacturing
Battery-component projects are creating demand for precision forming lines. The Government of Canada committed CAD 70 million (USD 50.07 million) to Volta Energy Solutions Canada's CAD 760.9 million (USD 544.28 million) copper foil facility in Granby, Quebec. The plant is expected to produce 25,000 tonnes of battery-grade copper foil per year from 2027. Battery enclosures and related structures require deep drawing, controlled forming, and repeatable handling of thin materials. AIDA's DPH Series Dedicated Former for rectangular storage battery cases received the 2025 Ten Greatest New Products Award for its single-stroke, multi-step forming capability. Such projects support the North America metal forming equipment market by adding demand for equipment that can form battery cases with fewer production stages.
High Capital Intensity and Long Payback Periods
Servo transfer presses, automated material handling, and integrated quality controls can cost multiple millions of dollars per line. These costs make complete replacements difficult for small and mid-sized fabricators with limited financing access. Beyond the equipment purchase, buyers must account for tooling, facility modifications, electrical upgrades, software integration, operator training, and commissioning costs, increasing the total investment required for automation projects. The payback periods for automated lines are 3-5 years, compared with conventional 2-3 year ranges. Longer payback periods can make capital approval more difficult, particularly for job shops with variable order volumes and limited visibility into future production requirements. Commissioning also requires certified electricians and controls engineers, which can add 6-12 weeks before production begins. Extended installation periods can create temporary production losses, particularly when an existing press must be taken offline before the new line is operational. Higher interest rates in 2023 and 2024 raised borrowing costs for long-lived capital assets. As a result, some manufacturers may favor phased automation, retrofit programs, or selective upgrades rather than full-line replacement. These conditions can slow purchase decisions in North America.
Other drivers and restraints analyzed in the detailed report include:
- Demand for Lightweight and High-Strength Components
- Aging Press Fleet Replacement and Retrofit Demand
- Steel, Servo-Drive, and Controls Cost Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Press Machines held 41.5% of the North America metal forming equipment market in 2025. The category covers mechanical, hydraulic, servo, and general-purpose systems for blanking, progressive-die stamping, and related work. Its scale reflects use across many forming applications and end-use sectors. Demand is supported by automotive components, electrical and electronics parts, appliances, industrial machinery, and other high-volume manufacturing applications where consistent forming accuracy and cycle times are important. Buyers also value equipment that supports repeatable production, operational data capture, and higher levels of automation. These requirements favor suppliers that combine press hardware with controls and lifecycle services. Integration with automated feeding, robotic part handling, in-line inspection, and production-monitoring systems is also increasing the value of complete press solutions.
Servo Presses are projected to expand at a 5.2% CAGR through 2031. Buyers seek lower energy use and more precise motion control from these systems. Programmable slide motion also allows manufacturers to optimize forming profiles for different materials and tooling requirements, while supporting faster changeovers and improved process consistency. Servo spindle press platforms with shared DC-bus energy management can reduce energy use by 70-85% per stroke compared with conventional hydraulic systems. These efficiency benefits can become more relevant for facilities operating multiple presses for extended production cycles. Press Brakes and Bending Machines are the second-largest equipment group, while Forging, Roll Forming, Hydroforming, and Extrusion equipment serve distinct applications. The mix of technologies allows manufacturers to select equipment according to material thickness, component geometry, production volume, forming force, and required dimensional accuracy. TRUMPF began producing TruBend 3000 series press brakes at its Farmington, Connecticut, facility in 2026.
Stamping and Punching held 30.5% of the North America metal forming equipment market in 2025. Automotive body production uses high-volume blanking and progressive-die lines across Michigan, Ontario, and northern Mexico. The growing use of lightweight vehicle structures and advanced high-strength steels is increasing requirements for higher press forces, tighter process control, and specialized tooling. Deep Drawing and Bending are important for fabrication and component production. These processes also support applications in appliances, HVAC systems, electrical enclosures, and industrial machinery, reducing dependence on automotive demand alone. Forging serves high-integrity powertrain and aerospace parts, while Rolling and Roll Forming benefit from construction-profile and solar-mounting demand. Automation through coil feeding, robotic transfer, in-line inspection, and die-change systems is further improving throughput in high-volume operations. This mix exposes the North America metal forming equipment market to several manufacturing investment cycles.
Hydroforming is projected to grow at a 5.1% CAGR through 2031. EV underbody assemblies and chassis frames use complex geometries that can reduce the number of welded joints. The process can support lightweight structural designs while maintaining required strength and dimensional consistency, making it relevant to vehicle weight-reduction programs. Schuler North America is adding a 5,000-ton press to its Canton, Michigan Hydroforming Production Center, alongside existing 3,500-ton and 8,500-ton equipment. Flexible lines that run advanced high-strength steel and aluminum through programmable controls remain a potential opportunity. Such flexibility can help manufacturers accommodate changing vehicle platforms and material specifications without investing in separate forming lines for every application. Much of the installed base requires setup changes to process both materials efficiently. This creates opportunities for upgraded controls, tooling optimization, automated setup systems, and process-monitoring solutions alongside new hydroforming equipment.
Complete Report Scope:
- By Equipment Type
- Press Machines
- Mechanical Presses
- Hydraulic Presses
- Servo Presses
- Other General-Purpose Presses
- Press Brakes and Bending Machines
- Hydraulic Press Brakes
- Servo / Electric Press Brakes
- Mechanical Press Brakes
- Other Bending Machines
- Forging Equipment
- Forging Presses
- Forging Hammers
- Upsetting and Heading Machines
- Other Forging Equipment
- Roll Forming and Plate/Profile Rolling Equipment
- Roll Forming Machines
- Plate Rolling Machines
- Section and Profile Rolling Machines
- Other Secondary Rolling/Forming Equipment
- Wire, Tube and Profile Forming Equipment
- Wire and Bar Drawing/Forming Equipment
- Tube Forming and Bending Equipment
- Profile Forming Equipment
- Extrusion Presses
- Hydroforming Equipment
- Other Metal Forming Equipment
- Press Machines
- By Forming Process
- Stamping and Punching
- Deep Drawing
- Bending
- Forging
- Rolling and Roll Forming
- Extrusion
- Hydroforming
- Other Forming Processes
- By Material Formed
- Carbon and Low-Alloy Steel
- Stainless Steel
- Aluminum and Aluminum Alloys
- Copper and Copper Alloys
- Titanium, Nickel and Other Non-Ferrous Metals
- Other Materials
- By End-Use Industry
- Automotive and Transportation
- Aerospace and Defense
- Industrial Machinery and Capital Equipment
- Metal Products and Fabrication
- Electrical and Electronics
- Construction and Infrastructure
- Energy and Power
- Consumer Appliances and Durable Goods
- Medical and Precision Manufacturing
- Other End-Use Industries
- By Geography
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- TRUMPF Group
- AMADA Co., Ltd.
- Schuler AG
- JIER Machine-Tool Group Co., Ltd.
- DMG MORI Co., Ltd.
- Komatsu Ltd.
- AIDA Engineering, Ltd.
- Bystronic AG
- Salvagnini Italia S.p.A.
- Prima Industrie S.p.A.
- LVD Company NV
- Cincinnati Incorporated
- Haas Automation, Inc.
- Mazak Corporation
- Okuma Corporation
- The Lincoln Electric Company
- ESAB Corporation
- Mitsubishi Heavy Industries, Ltd.
- Accurpress
- Pacific Press Technologies
- Wilson Tool International
- WardJet
- OMAX Corporation
- Magna International Inc.
- Gestamp Automocion S.A.
- Martinrea International Inc.
- Flex-N-Gate Corporation
- Autokiniton US Holdings, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Reshoring and Nearshoring of Metal-Intensive Manufacturing
- 4.2.2 Electrification and Battery-Component Manufacturing
- 4.2.3 Demand for Lightweight and High-Strength Components
- 4.2.4 Aging Press Fleet Replacement and Retrofit Demand
- 4.2.5 Automation to Offset Skilled Labor Shortages
- 4.2.6 Traceable, Cybersecure and Energy-Efficient Forming Lines
- 4.3 Market Restraints
- 4.3.1 High Capital Intensity and Long Payback Periods
- 4.3.2 Steel, Servo-Drive and Controls Cost Volatility
- 4.3.3 Shortage of Tool-and-Die and Commissioning Specialists
- 4.3.4 Cybersecurity Exposure in Connected Press Lines
- 4.4 Value and Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.5.1 OSHA Machine Guarding and Mechanical Power Press Requirements
- 4.5.2 ANSI B11.1 and ANSI B11.2 Safety Standards
- 4.5.3 ISO 9001 and IATF 16949 Supplier Requirements
- 4.5.4 USMCA Regional Content Requirements
- 4.5.5 Buy America and Infrastructure-Linked Procurement
- 4.5.6 Section 301 Tariffs and Import Compliance
- 4.6 Technological Outlook
- 4.6.1 Servo and Advanced Drive Technologies
- 4.6.2 CNC and Advanced Process Controls
- 4.6.3 Robotics and Automated Material Handling
- 4.6.4 Connected Machines and IIoT
- 4.6.5 Predictive Maintenance and Condition Monitoring
- 4.6.6 Energy-Efficient Forming Systems
- 4.6.7 Advanced High-Strength and Lightweight Material Forming
- 4.7 Impact Assessment of Geopolitical Events on the Market
5 Market Size & Growth Forecasts
- 5.1 By Equipment Type
- 5.1.1 Press Machines
- 5.1.1.1 Mechanical Presses
- 5.1.1.2 Hydraulic Presses
- 5.1.1.3 Servo Presses
- 5.1.1.4 Other General-Purpose Presses
- 5.1.2 Press Brakes and Bending Machines
- 5.1.2.1 Hydraulic Press Brakes
- 5.1.2.2 Servo / Electric Press Brakes
- 5.1.2.3 Mechanical Press Brakes
- 5.1.2.4 Other Bending Machines
- 5.1.3 Forging Equipment
- 5.1.3.1 Forging Presses
- 5.1.3.2 Forging Hammers
- 5.1.3.3 Upsetting and Heading Machines
- 5.1.3.4 Other Forging Equipment
- 5.1.4 Roll Forming and Plate/Profile Rolling Equipment
- 5.1.4.1 Roll Forming Machines
- 5.1.4.2 Plate Rolling Machines
- 5.1.4.3 Section and Profile Rolling Machines
- 5.1.4.4 Other Secondary Rolling/Forming Equipment
- 5.1.5 Wire, Tube and Profile Forming Equipment
- 5.1.5.1 Wire and Bar Drawing/Forming Equipment
- 5.1.5.2 Tube Forming and Bending Equipment
- 5.1.5.3 Profile Forming Equipment
- 5.1.6 Extrusion Presses
- 5.1.7 Hydroforming Equipment
- 5.1.8 Other Metal Forming Equipment
- 5.1.1 Press Machines
- 5.2 By Forming Process
- 5.2.1 Stamping and Punching
- 5.2.2 Deep Drawing
- 5.2.3 Bending
- 5.2.4 Forging
- 5.2.5 Rolling and Roll Forming
- 5.2.6 Extrusion
- 5.2.7 Hydroforming
- 5.2.8 Other Forming Processes
- 5.3 By Material Formed
- 5.3.1 Carbon and Low-Alloy Steel
- 5.3.2 Stainless Steel
- 5.3.3 Aluminum and Aluminum Alloys
- 5.3.4 Copper and Copper Alloys
- 5.3.5 Titanium, Nickel and Other Non-Ferrous Metals
- 5.3.6 Other Materials
- 5.4 By End-Use Industry
- 5.4.1 Automotive and Transportation
- 5.4.2 Aerospace and Defense
- 5.4.3 Industrial Machinery and Capital Equipment
- 5.4.4 Metal Products and Fabrication
- 5.4.5 Electrical and Electronics
- 5.4.6 Construction and Infrastructure
- 5.4.7 Energy and Power
- 5.4.8 Consumer Appliances and Durable Goods
- 5.4.9 Medical and Precision Manufacturing
- 5.4.10 Other End-Use Industries
- 5.5 By Geography
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 TRUMPF Group
- 6.4.2 AMADA Co., Ltd.
- 6.4.3 Schuler AG
- 6.4.4 JIER Machine-Tool Group Co., Ltd.
- 6.4.5 DMG MORI Co., Ltd.
- 6.4.6 Komatsu Ltd.
- 6.4.7 AIDA Engineering, Ltd.
- 6.4.8 Bystronic AG
- 6.4.9 Salvagnini Italia S.p.A.
- 6.4.10 Prima Industrie S.p.A.
- 6.4.11 LVD Company NV
- 6.4.12 Cincinnati Incorporated
- 6.4.13 Haas Automation, Inc.
- 6.4.14 Mazak Corporation
- 6.4.15 Okuma Corporation
- 6.4.16 The Lincoln Electric Company
- 6.4.17 ESAB Corporation
- 6.4.18 Mitsubishi Heavy Industries, Ltd.
- 6.4.19 Accurpress
- 6.4.20 Pacific Press Technologies
- 6.4.21 Wilson Tool International
- 6.4.22 WardJet
- 6.4.23 OMAX Corporation
- 6.4.24 Magna International Inc.
- 6.4.25 Gestamp Automocion S.A.
- 6.4.26 Martinrea International Inc.
- 6.4.27 Flex-N-Gate Corporation
- 6.4.28 Autokiniton US Holdings, Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.1.1 Flexible Multi-Material Forming Lines
- 7.1.2 Battery-Enclosure and EV Structural Forming
- 7.1.3 Retrofit Kits for Legacy Press Fleets
- 7.1.4 Cybersecure Remote-Service Platforms
- 7.1.5 Low-Energy Servo and Hybrid Systems
- 7.1.6 Workforce-Embedded Training and Commissioning Services

