PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2163610

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2163610
Asia-Pacific Servo Presses - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
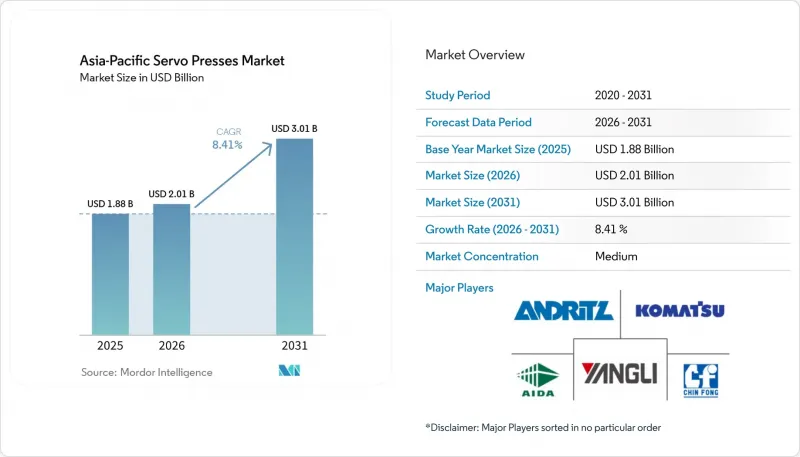
According to Mordor Intelligence, the Asia-Pacific servo presses market size is expected to grow from USD 1.88 billion in 2025 to USD 2.01 billion in 2026 and is forecast to reach USD 3.01 billion by 2031 at 8.41% CAGR over 2026-2031.
Asia-Pacific Servo Presses Market Trends and Insights
Vehicle Electrification and EV Component Production
Electric vehicle production is a central source of demand for the Asia-Pacific servo presses market. Battery enclosures, motor housing, busbar terminals, bipolar plates, and structural reinforcements require controlled forming and traceable production steps. India's automobile and auto-component incentive program had approved 82 applicants by September 2025 and supported the production of more than 1.36 million electric vehicles. BYD commissioned an integrated electric vehicle complex in Subang, Indonesia, in May 2026, including stamping operations with 130 dies shipped from Shenzhen. These investments support demand for forming equipment even where vehicle production grows more slowly because electric vehicle platforms use a broader range of stamped parts. This driver is likely to keep buyers focused on force control, tool life, and quality documentation.
Precision Electronics and Semiconductor Equipment Production
Semiconductor and electronics investment support demand for precise assembly and forming systems in the Asia-Pacific servo presses market. Global semiconductor equipment billings reached USD 135.1 billion in 2025, and China, Taiwan, and South Korea together accounted for 79% of spending. Taiwan spent USD 31.5 billion on equipment in 2025, while South Korea spent USD 25.8 billion and Japan spent USD 9.5 billion. These investments require supporting equipment for lead frames, connectors, shielding parts, and packaging components. Electromechanical presses are relevant because they can operate without hydraulic oil and fit clean manufacturing environments. Buyers are also placing more weight on secure and connected machine interfaces, which favors suppliers that can support digital production systems.
High Initial Capital Cost and Extended SME Payback Periods
High purchase costs remain a major barrier for smaller buyers in the Asia-Pacific servo presses market. A servo line for electric vehicle battery-enclosure stamping requires USD 1 million to USD 3 million per unit. In contrast, a greenfield Tier 2 automotive press shop can require more than USD 15 million in total line investment. The Asian Development Bank identifies finance access, limited collateral, short lending terms, and perceived technology risk as barriers for manufacturing small and medium enterprises in developing Asian economies. India's capital-goods incentive program offers 5%-6% incentives on incremental production value for eligible manufacturers. The support does not cover every smaller workshop so that many firms may retain older equipment longer. Financing models and retrofit options can reduce the constraint, but they do not remove it.
Other drivers and restraints analyzed in the detailed report include:
- Industry 4.0 Adoption and Closed-Loop Process Control
- Energy Efficiency and Reduced Hydraulic-System Dependence
- Shortage of Servo Programming, Controls, and Application-Engineering Skills
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Straight-side/H-frame held 42% of the Asia-Pacific servo presses market in 2025. The configuration provides stable slide guidance and even bed-pressure distribution for large progressive and transfer dies. Chinese automotive Tier 1 suppliers and Korean OEM-tier press shops use it for body panels and electric vehicle structural components. Its design supports demanding work with advanced high-strength steel and eccentric loading. C-frame and gap-frame machines remain important for precision electronics because they support easier access and quicker tool changes.
Straight-side/H-frame was also identified as the fastest-growing configuration, registering a 9.7% CAGR through 2031. New automotive plants in ASEAN are specifying servo systems from the start instead of converting older mechanical lines in stages. This supports demand for large and rigid frames in new press shops. SEYI demonstrated a high-rigidity solid-frame servo press for metallic bipolar plate micro-channel forming in July 2025. That example shows that the configuration also serves precision energy-component production. Column and post-type equipment continues to address powder compaction and specialized prototype work. Frame choice is closely tied to the size of the die, the material being formed, and the production process. Straight-side equipment supports customers who need a rigid structure for large vehicle parts and repeated cycles. C-Frame machines retain a role when operators need direct access to the tooling area. Column and post-type machines are more specialized and can support development work or powder-based applications. These differences mean that frame demand follows the mix of automotive, electronics, and specialized manufacturing in each country. Manufacturers, therefore, need to match the press structure to the intended tool and part design.
Servo-mechanical metal forming presses accounted for 49.4% of the regional market value in 2025. Their position reflects their use in high-volume automotive and appliance stamping, where crank and link-drive systems support large-tonnage forming cycles. Chinese and South Korean automotive manufacturers and Tier 1 suppliers are major buyers as they replace flywheel-driven equipment. The equipment is suited to repeatable forming tasks with demanding production volumes. Servo-hydraulic presses still serve deep drawing and large-tonnage hot-forming work where force consistency over long strokes is important.
Electromechanical and electric servo assembly presses are the fastest-growing technology type, registering a 12.5% CAGR through 2031. Electronics, medical-device, and semiconductor-component manufacturers favor oil-free equipment that can work in clean manufacturing areas. Janome Industrial Equipment's ISO Class 4-certified JP Series 5 servo presses provide an example of equipment designed for semiconductors and medical-device assembly. Hybrid systems are also used in powder compaction and multistage forming when a process needs elements of programmable movement and hydraulic force. The change toward electric systems reflects tighter needs for positioning, cleanliness, and documented process control. The Asia-Pacific servo presses industry is therefore serving a wider range of production settings than traditional metal forming alone. Technology selection is shaped by the production environment as well as by press force. Servo-mechanical systems remain practical for repeated, high-output metal-forming cycles. Electric servo systems suit customers who need cleaner operation, precise motion, and controlled assembly. Servo-hydraulic and hybrid equipment continue to serve processes where stroke length or force needs differ from standard stamping. This means that no single technology fits every plant or component. Suppliers that can explain the operating trade-offs clearly are better placed to serve automotive, electronics, and medical customers.
Complete Report Scope:
- By Frame / Structural Configuration
- C-Frame / Gap-Frame Servo Presses
- Straight-Side / H-Frame Servo Presses
- Column / Post-Type Servo Presses
- Other Servo Press Configurations
- By Servo Press Technology / System Type
- Servo-Mechanical Metal Forming Presses
- Electromechanical / Electric Servo Assembly Presses
- Servo-Hydraulic Presses
- Hybrid Servo Presses
- By Press Force / Capacity
- Up to 10 Tons
- Above 10-100 Tons
- Above 100-500 Tons
- Above 500-1,000 Tons
- Above 1,000 Tons
- By Application
- Stamping, Blanking, and Punching
- Deep Drawing and Sheet Forming
- Forging and Cold Forming
- Assembly, Press-Fitting and Joining
- Powder Compaction
- Other Precision and Specialized Pressing Applications
- By End User
- Automotive and Transportation
- Electrical and Electronics
- Aerospace and Defense
- Medical and Precision Devices
- Industrial Machinery and General Manufacturing
- Appliances and Consumer Durables
- Other End-Use Industries
- By Geography
- China
- Japan
- India
- South Korea
- Taiwan
- ASEAN(Singapore, Malaysia, Indonesia, Thailand, Vietnam, Philippines, Myanmar, Cambodia, Laos, Brunei)
- Rest of Asia-Pacific
List of Companies Covered in this Report:
- AIDA Engineering Ltd.
- Amada Co., Ltd.
- ANDRITZ AG and Schuler Group
- Chin Fong Machine Industrial Co., Ltd.
- Fagor Arrasate
- Hitachi Zosen Corporation
- Hitachi Zosen Fukui Corporation
- Hoden Seimitsu Kako Kenkyusho Co., Ltd.
- IAI Corporation
- ISGEC Heavy Engineering Ltd.
- Japan Automatic Machine Co., Ltd.
- JANOME Corporation
- JIER Machine-Tool Group Co., Ltd.
- Komatsu Ltd.
- Kistler Group
- Nidec Corporation
- Promess Incorporated
- SANYO MACHINE WORKS, LTD.
- SEYI Machinery Co., Ltd.
- Shieh Yih Machinery Industry Co., Ltd.
- SIMPAC Inc.
- SINTOKOGIO, LTD.
- THK Co., Ltd.
- TOX PRESSOTECHNIK GmbH & Co. KG
- Yangli Group Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Vehicle Electrification and EV Component Production
- 4.2.2 Precision Electronics and Semiconductor Equipment Production
- 4.2.3 Industry 4.0 Adoption and Closed-Loop Process Control
- 4.2.4 Energy Efficiency and Reduced Hydraulic-System Dependence
- 4.2.5 Servo Retrofit Demand Across Asia-Pacific's Installed Press Base
- 4.2.6 Localization of Servo Motors, Drives, and High-Tonnage Press Supply
- 4.3 Market Restraints
- 4.3.1 High Initial Capital Cost and Extended SME Payback Periods
- 4.3.2 Shortage of Servo Programming, Controls, and Application-Engineering Skills
- 4.3.3 Thermal Derating During Continuous High-Speed Stamping
- 4.3.4 Long Lead Times for High-Power Servo Motors and Control Systems
- 4.4 Value and Supply-Chain Analysis
- 4.4.1 Servo Motors, Drives, and Control Components
- 4.4.2 Press Frames, Mechanical and Hydraulic Components
- 4.4.3 Servo Press Manufacturing and System Integration
- 4.4.4 Dies, Tooling, Automation, and Robotics Ecosystem
- 4.4.5 Distribution, Installation and Commissioning
- 4.4.6 Aftermarket, Software, Retrofit and Service Ecosystem
- 4.5 Regulatory Landscape
- 4.5.1 Machinery Safety Requirements
- 4.5.2 Electrical Safety and Functional Safety Requirements
- 4.5.3 Energy-Efficiency and Industrial-Decarbonization Policies
- 4.5.4 Import Duties, Localization Policies, and Government Incentives
- 4.5.5 Factory Automation, Data Governance, and Cybersecurity Requirements
- 4.6 Technological Outlook
- 4.6.1 Advanced Servo-Mechanical and Direct-Drive Technologies
- 4.6.2 Electromechanical Precision Press Technologies
- 4.6.3 Servo-Hydraulic and Hybrid Press Technologies
- 4.6.4 Closed-Loop Force, Position and Motion Control
- 4.6.5 Digital Connectivity and IIoT Integration
- 4.6.6 AI-Enabled Process Optimization and Predictive Maintenance
- 4.6.7 Energy Recovery and Regenerative Technologies
- 4.7 Industry and Manufacturing Trends
- 4.7.1 Growth of Flexible and High-Mix Manufacturing
- 4.7.2 Automation and Integrated Press Lines
- 4.7.3 Increasing Demand for Traceable and Precision Pressing
- 4.7.4 Sustainability and Energy-Efficiency Trends
- 4.8 Sustainability and Energy Efficiency
- 4.9 Impact of Geopolitical Devvelopments on the Market
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Frame / Structural Configuration
- 5.1.1 C-Frame / Gap-Frame Servo Presses
- 5.1.2 Straight-Side / H-Frame Servo Presses
- 5.1.3 Column / Post-Type Servo Presses
- 5.1.4 Other Servo Press Configurations
- 5.2 By Servo Press Technology / System Type
- 5.2.1 Servo-Mechanical Metal Forming Presses
- 5.2.2 Electromechanical / Electric Servo Assembly Presses
- 5.2.3 Servo-Hydraulic Presses
- 5.2.4 Hybrid Servo Presses
- 5.3 By Press Force / Capacity
- 5.3.1 Up to 10 Tons
- 5.3.2 Above 10-100 Tons
- 5.3.3 Above 100-500 Tons
- 5.3.4 Above 500-1,000 Tons
- 5.3.5 Above 1,000 Tons
- 5.4 By Application
- 5.4.1 Stamping, Blanking, and Punching
- 5.4.2 Deep Drawing and Sheet Forming
- 5.4.3 Forging and Cold Forming
- 5.4.4 Assembly, Press-Fitting and Joining
- 5.4.5 Powder Compaction
- 5.4.6 Other Precision and Specialized Pressing Applications
- 5.5 By End User
- 5.5.1 Automotive and Transportation
- 5.5.2 Electrical and Electronics
- 5.5.3 Aerospace and Defense
- 5.5.4 Medical and Precision Devices
- 5.5.5 Industrial Machinery and General Manufacturing
- 5.5.6 Appliances and Consumer Durables
- 5.5.7 Other End-Use Industries
- 5.6 By Geography
- 5.6.1 China
- 5.6.2 Japan
- 5.6.3 India
- 5.6.4 South Korea
- 5.6.5 Taiwan
- 5.6.6 ASEAN(Singapore, Malaysia, Indonesia, Thailand, Vietnam, Philippines, Myanmar, Cambodia, Laos, Brunei)
- 5.6.7 Rest of Asia-Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 AIDA Engineering Ltd.
- 6.4.2 Amada Co., Ltd.
- 6.4.3 ANDRITZ AG and Schuler Group
- 6.4.4 Chin Fong Machine Industrial Co., Ltd.
- 6.4.5 Fagor Arrasate
- 6.4.6 Hitachi Zosen Corporation
- 6.4.7 Hitachi Zosen Fukui Corporation
- 6.4.8 Hoden Seimitsu Kako Kenkyusho Co., Ltd.
- 6.4.9 IAI Corporation
- 6.4.10 ISGEC Heavy Engineering Ltd.
- 6.4.11 Japan Automatic Machine Co., Ltd.
- 6.4.12 JANOME Corporation
- 6.4.13 JIER Machine-Tool Group Co., Ltd.
- 6.4.14 Komatsu Ltd.
- 6.4.15 Kistler Group
- 6.4.16 Nidec Corporation
- 6.4.17 Promess Incorporated
- 6.4.18 SANYO MACHINE WORKS, LTD.
- 6.4.19 SEYI Machinery Co., Ltd.
- 6.4.20 Shieh Yih Machinery Industry Co., Ltd.
- 6.4.21 SIMPAC Inc.
- 6.4.22 SINTOKOGIO, LTD.
- 6.4.23 THK Co., Ltd.
- 6.4.24 TOX PRESSOTECHNIK GmbH & Co. KG
- 6.4.25 Yangli Group Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
- 7.1.1 Servo Retrofit Kits for Aging Mechanical Presses
- 7.1.2 Mid-Tonnage Servo Presses for Indian and ASEAN Manufacturers
- 7.1.3 Localized Controls and Service for Chinese and Southeast Asian Buyers
- 7.1.4 Low-Carbon Press Systems for Export-Oriented Suppliers
- 7.1.5 Integrated Force-Traceability Platforms for Regulated Manufacturing
- 7.1.6 Modular Servo Press Cells for Job Shops and Contract Manufacturers
- 7.2 Future Outlook
- 7.2.1 EV Battery and Lightweight Vehicle Components
- 7.2.2 Electronics, Semiconductor, and Connector Manufacturing
- 7.2.3 Smart-Factory Integration
- 7.2.4 Regionalization of Manufacturing Supply Chains
- 7.2.5 Aftermarket, Retrofit, and Service Revenue Pools

