PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2184659

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2184659
Middle East and Africa Hair Colorants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
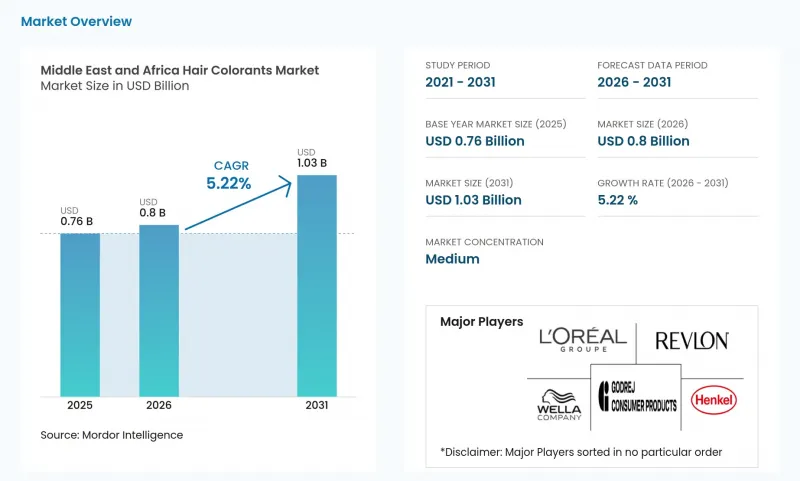
According to Mordor Intelligence, the Middle East and Africa hair colorants market size was valued at USD 0.76 billion in 2025 and is projected to reach USD 0.80 billion by 2026 and USD 1.03 billion by 2031, growing at a CAGR of 5.22% from 2026 to 2031.
Middle East and Africa Hair Colorants Market Trends and Insights
Rising Demand for Grey Hair Coverage
Grey hair coverage provides recurring demand because consumers use colorants for a practical personal-care need. The population aged 65 years and above represented 5.19% of the MENA population in 2025 . The World Bank expects this age group to reach 12% of the regional population by 2050 . The Middle East and Africa hair colorants market therefore has a larger pool of consumers who may seek regular grey coverage over time. Religious practices that encourage covering grey hair can further position hair coloring as part of regular grooming for some consumers. This pattern favors products that offer reliable coverage, clear shade results, and repeatable application at home or in salons.
Rising Popularity of Natural and Herbal Formulations
Henna-based and ammonia-free products are moving from heritage use toward a more organized commercial category in the Middle East and Africa hair colorants market. Consumer interest in halal-certified products extends beyond Muslim consumers and can support premium demand in South Africa and Turkey. Research on herbal hair dye formulations discusses scalp nourishment, hair strengthening, and improved texture as relevant product attributes. These attributes support a clearer performance case for herbal alternatives, particularly where consumers are concerned about allergens. Natural formulations can also use familiar regional ingredients to build trust without depending only on a premium label. The opportunity is strongest where brands can demonstrate consistent color performance and support their claims with credible certification.
Stringent Regulations on Cosmetic Ingredients
Ingredient controls can raise reformulation, documentation, and import requirements for suppliers in the Middle East and Africa hair colorants market. Saudi Arabia issued updates in 2025 that added 3 substances to its restricted list and 21 substances to its prohibited list. The updates apply to imported cosmetic products, with non-compliant imports barred from January 2026 and a sell-through period extending to January 2028. These requirements can increase lead times and raise the burden on smaller suppliers. Multinationals with established reformulation processes can respond more quickly than smaller regional companies. Compliance capabilities may therefore become a more important part of supplier selection and brand positioning.
Other drivers and restraints analyzed in the detailed report include:
- Social Media and Celebrity Beauty Influence
- Expanding Aging Population in the Region
- Allergic Reactions and Scalp Sensitivity Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Permanent colorants held 49.52% of the Middle East and Africa hair colorants market share in 2025, reflecting their central role in reliable grey coverage, routine color maintenance, and the established professional salon service model. For many buyers, permanent colorants provide a familiar choice when long-lasting results and regular maintenance are more important than experimenting with temporary fashion shades. The salon channel treats permanent coloring as a standard service, which supports the format's position and helps consumers obtain shade matching, application support, and repeat color services. Semi-permanent products serve consumers who want a tone refresh without a full oxidative process, allowing them to manage their appearance with less commitment to a fixed result. This is particularly relevant for younger urban women in GCC markets, where salon use, online beauty discovery, and interest in manageable color changes can occur together.
Temporary colorants are the fastest-growing product format at 6.48% from 2026 to 2031 in the Middle East and Africa hair colorants market, indicating demand for flexible products that can suit changing beauty preferences and more cautious ingredient choices. Concern about PPD sensitivity is contributing to interest in products that avoid permanent oxidative chemistry, especially for consumers who want to limit perceived exposure while retaining access to hair color. Manufacturers are offering color-depositing shampoos and wash-out glosses for consumers who value simpler application, shorter wear periods, and a less permanent change to their hair color. Bleachers and highlighters remain concentrated in salons because they need greater skill, careful processing, and shade management, resulting in limited home use across much of the region. Color-melting techniques that combine balayage and highlights can support demand for professional highlighting services, particularly when regional hair professionals present the results through social media content.
Mass-tier products captured 72.34% of the Middle East and Africa hair colorants market share in 2025, making accessible pricing central to regional volume and to everyday purchasing across many consumer groups. Egypt, Nigeria, Morocco, and lower-income GCC consumer groups remain important volume bases for this tier, where affordable products must still meet expectations on visible coverage and convenient home use. Grey coverage, color durability, and ease of application are key purchase factors for value-oriented households, particularly when consumers are buying a product for a recurring need rather than an occasional fashion change. Established brands maintain loyalty by delivering consistent results through widely available supermarket distribution, which reduces the effort needed to find a familiar product and shade. Mass products also provide the base from which suppliers can encourage consumers to trade up when they see a clear benefit in formulation, convenience, or professional-style results.
Premium-tier colorants are the fastest-growing price segment at 6.78% from 2026 to 2031 in the Middle East and Africa hair colorants market, as more consumers seek products that combine better ingredient communication with salon-style performance at home. Growth is linked to income gains in the GCC, online product discovery, and greater attention to ingredient quality, which give consumers more reasons to compare products beyond price alone. The main pathway is trading up from mass products to professional-grade or salon-quality formulations for use at home, rather than a complete replacement of value-oriented purchasing behavior. Henkel launched Creme Supreme by Schwarzkopf in May 2025 as a 3-step coloration process positioned to deliver professional-grade results at an accessible price, creating a tangible premium option for existing users. This approach shows how product design can support premium migration while retaining value-conscious consumers who still need clear performance and easy application.
Complete Report Scope:
- By Product Type
- Bleachers
- Highlighters
- Permanent Colorants
- Semi-Permanent Colorants
- Temporary Colorants
- By Price Range
- Mass
- Premium
- By Category
- Organic
- Conventional
- By Distribution Channel
- Supermarkets/Hypermarkets
- Health and Beauty Stores
- Online Retail Stores
- Other Distribution Channels
- By Geography
- Saudi Arabia
- United Arab Emirates
- Nigeria
- Egypt
- Morocco
- Turkey
- South Africa
- Rest of Middle East and Africa
List of Companies Covered in this Report:
- L'Oreal S.A.
- Henkel AG & Co. KGaA
- Wella Company
- Kao Corporation
- Revlon, Inc.
- Godrej Consumer Products Limited
- Dabur India Limited
- Hoyu Co., Ltd.
- Combe Incorporated
- Keune Haircosmetics
- Alfaparf Milano
- John Paul Mitchell Systems
- Hygienic Research Institute Pvt. Ltd.
- Laboratorios Phergal
- Avon Products
- Subrina Professional
- Farouk Systems, Inc.
- Salerm Cosmetics
- Blust On
- KYO Professional
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Grey Hair Coverage
- 4.2.2 Increasing Male Grooming and Colorant Adoption
- 4.2.3 Rising Popularity of Natural and Herbal Formulations
- 4.2.4 Social Media and Celebrity Beauty Influence
- 4.2.5 Expanding Aging Population in the Region
- 4.2.6 Growth of Professional Salon Services
- 4.3 Market Restraints
- 4.3.1 Allergic Reactions and Scalp Sensitivity Concerns
- 4.3.2 Stringent Regulations on Cosmetic Ingredients
- 4.3.3 Availability of Counterfeit and Low-Quality Products
- 4.3.4 Environmental Concerns over Chemical Waste Disposal
- 4.4 Consumer Behaviour Analysis
- 4.5 Regulatory Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Bleachers
- 5.1.2 Highlighters
- 5.1.3 Permanent Colorants
- 5.1.4 Semi-Permanent Colorants
- 5.1.5 Temporary Colorants
- 5.2 By Price Range
- 5.2.1 Mass
- 5.2.2 Premium
- 5.3 By Category
- 5.3.1 Organic
- 5.3.2 Conventional
- 5.4 By Distribution Channel
- 5.4.1 Supermarkets/Hypermarkets
- 5.4.2 Health and Beauty Stores
- 5.4.3 Online Retail Stores
- 5.4.4 Other Distribution Channels
- 5.5 By Geography
- 5.5.1 Saudi Arabia
- 5.5.2 United Arab Emirates
- 5.5.3 Nigeria
- 5.5.4 Egypt
- 5.5.5 Morocco
- 5.5.6 Turkey
- 5.5.7 South Africa
- 5.5.8 Rest of Middle East and Africa
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 L'Oreal S.A.
- 6.4.2 Henkel AG & Co. KGaA
- 6.4.3 Wella Company
- 6.4.4 Kao Corporation
- 6.4.5 Revlon, Inc.
- 6.4.6 Godrej Consumer Products Limited
- 6.4.7 Dabur India Limited
- 6.4.8 Hoyu Co., Ltd.
- 6.4.9 Combe Incorporated
- 6.4.10 Keune Haircosmetics
- 6.4.11 Alfaparf Milano
- 6.4.12 John Paul Mitchell Systems
- 6.4.13 Hygienic Research Institute Pvt. Ltd.
- 6.4.14 Laboratorios Phergal
- 6.4.15 Avon Products
- 6.4.16 Subrina Professional
- 6.4.17 Farouk Systems, Inc.
- 6.4.18 Salerm Cosmetics
- 6.4.19 Blust On
- 6.4.20 KYO Professional
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK

