PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185248

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185248
Vietnam Fourth-Party Logistics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
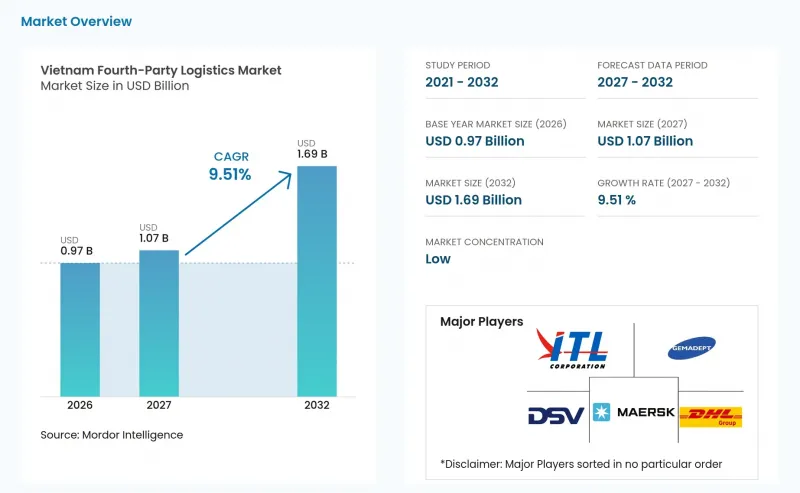
According to Mordor Intelligence, the Vietnam fourth-party logistics (4PL) market is valued at USD 0.97 billion in 2026 and is estimated to grow from USD 1.07 billion in 2027 to USD 1.69 billion by 2032, registering a CAGR of 9.51% during the forecast period 2027-2032.
Vietnam Fourth-Party Logistics Market Trends and Insights
Logistics Outsourcing Increasing Integrated Supply Chain Demand
Vietnam's logistics development strategy for 2025-2035 targets a logistics outsourcing rate of 70-80%, reflecting the government's intention to encourage wider use of professional logistics services. This policy direction creates opportunities for 4PL providers to coordinate transportation, warehousing, customs procedures, and distribution across multiple service providers. Manufacturers with complex sourcing and export networks can benefit from centralized performance monitoring, carrier management, and shipment visibility. The opportunity depends on whether shippers choose to transfer coordination responsibilities to independent integrators rather than manage individual logistics contracts internally.
Manufacturing Relocation Expanding Multi-Country Coordination Requirements
Vietnam's manufacturing activity creates demand for coordinated inbound materials, factory inventory, customs documentation, and outbound distribution. Manufacturers operating across several Asian sourcing markets need to align supplier schedules with production requirements and export commitments. Fourth-party logistics providers can support these operations by integrating multiple carriers and logistics partners into a common planning and monitoring structure. The country's role in international manufacturing networks therefore provides a structural opportunity for providers with cross-border coordination capabilities, reliable local partners, and technology that connects shipment and inventory information.
Skilled Talent Shortages Limiting Advanced Planning Capabilities
Fourth-party logistics operations require personnel who can combine transportation planning, data analysis, customs knowledge, and supplier coordination. A shortage of employees with these combined capabilities can constrain the implementation of advanced control towers and integrated supply chain services. Providers may need to invest in internal training and recruitment before taking responsibility for complex customer accounts. Differences in workforce availability between major logistics centers and less-developed locations can also affect service consistency and the cost of expanding operations.
Other drivers and restraints analyzed in the detailed report include:
- Omnichannel Growth Increasing Complex Fulfillment Orchestration Demand
- Government Support Encouraging Advanced Logistics Service Adoption
- Legacy Systems Hindering Integrated Data Exchange Efficiency
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solution integrators account for a 43.67% share of the Vietnam fourth-party logistics market in 2026. Their position reflects the need among complex shippers to coordinate transportation providers, warehouses, customs brokers, and distribution partners through a single management structure. These services are relevant to manufacturers with international sourcing networks and multiple export destinations. Solution Integrators can centralize performance monitoring and exception management while allowing customers to retain existing relationships with individual logistics operators.
Digital platform 4PL is projected to register a CAGR of 10.34% during 2027-2032. Cloud-based control towers, system interfaces, and automated reporting can improve shipment visibility and reduce manual coordination. In February 2026, Samsung SDS showcased its Cello Square digital logistics capabilities at Manifest 2026, highlighting control-tower monitoring and technology-enabled supply chain management. Platform adoption will depend on integration with local service providers, the availability of accurate data, and the ability to support customers' existing operating systems.
Complete Report Scope:
- By Operating Model
- Lead Logistics Provider (LLP)
- Solution Integrator
- Digital Platform 4PL
- By End-User Industry
- FMCG
- Retail and E-commerce
- Fashion and Lifestyle
- Technology and Electronics
- Refrigerated and Pharma
- Automotive and Mobility
- Industrial Manufacturing
- Others
- By Enterprise Size
- Small and Medium Enterprises
- Large Enterprises
- By Region
- Northern Vietnam
- Central Vietnam
- Southern Vietnam
List of Companies Covered in this Report:
- DHL Group
- DSV
- A.P. Moller - Maersk
- Kuehne+Nagel
- APL Logistics
- CEVA Logistics
- GEODIS
- Nippon Express Holdings
- Samsung SDS
- FM Logistic
- Gemadept Corporation
- Yusen Logistics
- CJ Logistics
- Indo Trans Logistics Corporation (ITL)
- Transimex Corporation
- Bee Logistics Corporation
- Vinafco Corporation
- Viettel Logistics
- U&I Logistics
- ASL Logistics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
- 3.1 Market Size, Growth, and Forecast Outlook
- 3.2 Key Demand Drivers and 4PL Market Trends
- 3.3 Major Logistics Networks and Demand Concentration
- 3.4 Competitive Landscape and Leading 4PL Providers
4 MARKET LANDSCAPE
- 4.1 Market Overview and Importance of 4PL
- 4.2 Market Drivers
- 4.2.1 Logistics Outsourcing Increasing Integrated Supply Chain Demand
- 4.2.2 Manufacturing Relocation Expanding Multi-Country Coordination Requirements
- 4.2.3 Omnichannel Growth Increasing Complex Fulfillment Orchestration Demand
- 4.2.4 Government Support Encouraging Advanced Logistics Service Adoption
- 4.2.5 Fragmented Capacity Increasing Neutral Supply Chain Orchestration
- 4.2.6 Export Compliance Increasing Carbon and Customs Data Demand
- 4.3 Market Restraints
- 4.3.1 Skilled Talent Shortages Limiting Advanced Planning Capabilities
- 4.3.2 Legacy Systems Hindering Integrated Data Exchange Efficiency
- 4.3.3 Shipper Data Reluctance Restricting End-to-End Visibility
- 4.3.4 Regional Infrastructure Gaps Reducing Network Optimization Efficiency
- 4.4 Value Chain Structure and 4PL Service Flow Analysis
- 4.5 Regulatory Framework and 4PL Compliance Requirements Analysis
- 4.6 Technology Adoption and Supply Chain Digitalization Analysis
- 4.7 Transportation and Warehousing Investment Trend Analysis
- 4.8 Domestic and Cross-Border Cargo Flow Complexity Assessment
- 4.9 Regional Logistics Investment and Network Expansion Analysis
- 4.10 Porter's Five Forces Analysis
- 4.10.1 Threat of New Entrants
- 4.10.2 Bargaining Power of Buyers
- 4.10.3 Bargaining Power of Suppliers
- 4.10.4 Threat of Substitute Services
- 4.10.5 Intensity of Competitive Rivalry
- 4.11 Impact of Geo-Political Events on Supply Chain Shifts
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Operating Model
- 5.1.1 Lead Logistics Provider (LLP)
- 5.1.2 Solution Integrator
- 5.1.3 Digital Platform 4PL
- 5.2 By End-User Industry
- 5.2.1 FMCG
- 5.2.2 Retail and E-commerce
- 5.2.3 Fashion and Lifestyle
- 5.2.4 Technology and Electronics
- 5.2.5 Refrigerated and Pharma
- 5.2.6 Automotive and Mobility
- 5.2.7 Industrial Manufacturing
- 5.2.8 Others
- 5.3 By Enterprise Size
- 5.3.1 Small and Medium Enterprises
- 5.3.2 Large Enterprises
- 5.4 By Region
- 5.4.1 Northern Vietnam
- 5.4.2 Central Vietnam
- 5.4.3 Southern Vietnam
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Geographic Coverage, Products and Services, Recent Developments)
- 6.4.1 DHL Group
- 6.4.2 DSV
- 6.4.3 A.P. Moller - Maersk
- 6.4.4 Kuehne+Nagel
- 6.4.5 APL Logistics
- 6.4.6 CEVA Logistics
- 6.4.7 GEODIS
- 6.4.8 Nippon Express Holdings
- 6.4.9 Samsung SDS
- 6.4.10 FM Logistic
- 6.4.11 Gemadept Corporation
- 6.4.12 Yusen Logistics
- 6.4.13 CJ Logistics
- 6.4.14 Indo Trans Logistics Corporation (ITL)
- 6.4.15 Transimex Corporation
- 6.4.16 Bee Logistics Corporation
- 6.4.17 Vinafco Corporation
- 6.4.18 Viettel Logistics
- 6.4.19 U&I Logistics
- 6.4.20 ASL Logistics
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space Opportunities and Unmet 4PL Service Needs
- 7.2 High-Potential End-User Segments and Growth Opportunities
- 7.3 Strategic Growth Priorities Across 4PL Ecosystem
- 7.4 Future Market Outlook and Emerging Demand Pockets
8 APPENDIX

