PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185980

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185980
NVOCC Ocean Groupage Consolidation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the NVOCC ocean groupage consolidation market size is projected to expand from USD 13.60 billion in 2026 and USD 14.46 billion in 2027 to USD 19.29 billion by 2032, registering a CAGR of 5.93% between 2027 and 2032.
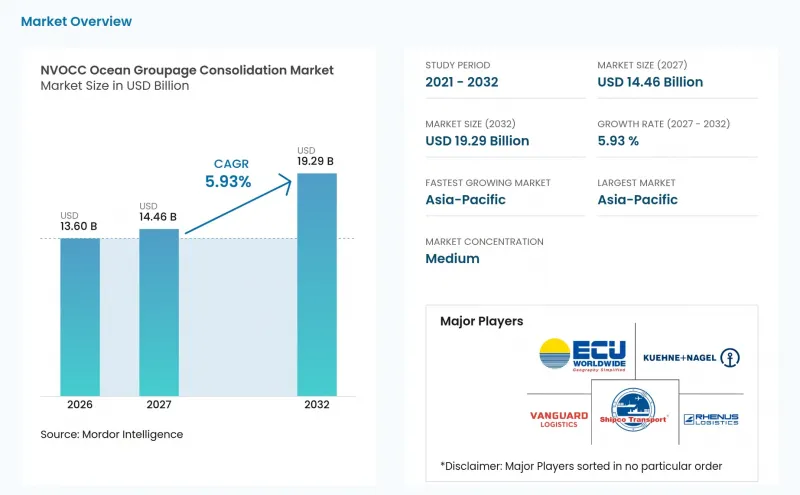
The NVOCC ocean groupage consolidation market is supported by a rising number of sub-container-load shipments that do not justify a full container or air freight. This report is Segmented by Service Type (Consolidation, Deconsolidation, Documentation/Compliance, Value-Added Services), by End User (Manufacturing, E-Commerce, Healthcare, Electronics, and More), by Cargo Type (Dry, Reefer, Dangerous Goods, High-Value, Others), and by Geography (North America, South America, Europe, Asia-Pacific, MEA). The Market Forecasts are Provided in Terms of Value (USD).
Global NVOCC Ocean Groupage Consolidation Market Trends and Insights
Cross-Border E-Commerce and Smaller Shipment Batches
Cross-border e-commerce has changed the size profile of ocean shipments by increasing direct-to-consumer replenishment activity. Sellers that source from Asia frequently move cargo below 10 cubic meters, which is below the threshold for a dedicated 20-foot container. Those orders enter shared-container networks because parcel express is unsuitable for larger replenishment loads. The removal of the USD 800 de minimis threshold for China and Hong Kong-origin goods in early 2025 redirected part of parcel trade into formal, documented ocean movements. UNCTAD expects containerized seaborne trade to grow 2.3% annually from 2026 to 2030, providing a stable volume base for the NVOCC ocean groupage consolidation market.
SME Export Participation and Sourcing Diversification
Small and medium-sized enterprises account for 36% of exports and 41% of imports in developed economies, according to the WCO, WTO, and ICC. These businesses often have shipment sizes that are too large for express freight but too small to fill a container each week. The NVOCC ocean groupage consolidation market, therefore, depends on their access to documented trade and predictable customs processes. Manufacturers expanded secondary sourcing in Vietnam, India, and Mexico during 2025 as tariff policy increased the value of alternative supply locations. Buyer consolidation can combine cargo from several Asian suppliers before export and lower container freight station-to-port costs by 15%-25%. Tiered Authorized Economic Operator programs can reduce the trade-facilitation barriers facing smaller exporters.
Port Congestion and Schedule Unreliability
Global container shipping schedule reliability averaged 65.2% in September 2025 and fell to 61.4% in October 2025. Average delays for late vessel arrivals reached 4.98 days during October 2025. A missed sailing affects every co-loader in a shared container because each shipment has a different cargo-ready date and delivery requirement. Capacity churn on the Asia-North Europe lane reached 11.0 million TEU in 2025, compared with a 3-5 million TEU historical range from 2012 to 2019. Antwerp yard utilization reached 90% for dry and reefer containers in late October 2025, while Santos and Paranagua also experienced bottlenecks. These conditions weaken the case for ocean groupage when pharmaceutical, fashion, and seasonal retail cargo cannot tolerate delays.
Other drivers and restraints analyzed in the detailed report include:
- Ocean Cost Advantage for Non-Urgent Cargo
- API-Enabled Booking, Documentation, and Shipment Visibility
- Ocean-Rate Volatility and Variable Container Utilization
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Consolidation services held 43.50% of the NVOCC ocean groupage consolidation market size in 2026. The service brings several consignments into one container and charges each shipper for the volume used. Buyer's consolidation can reduce container freight station-to-port costs by 15%-25% compared with individual LCL bookings. This service remains central because it gives smaller shippers access to ocean freight without funding a full container. Major hubs such as Singapore, Rotterdam, Long Beach, and Dubai support frequent departures where cargo matching is strong. De-consolidation and distribution are the next major activities because imported shared containers need sorting and delivery after arrival. Providers that manage origin consolidation and destination de-consolidation can control more of the shipment process.
Value-added services are forecast to register a 7.69% CAGR from 2027 to 2032. This category includes customs advice, carbon-data reporting, duty calculations, and last-mile coordination. Mixed containers require consistent shipment information because a documentation error can delay the entire load. The NVOCC ocean groupage consolidation market, therefore, rewards operators that screen records before cargo reaches the port. DCSA's standards support more consistent electronic booking and bill-of-lading data across carrier systems. Customers can receive these services through one interface rather than buying them from separate providers. This can improve customer retention and lift revenue per TEU-equivalent shipment.
Complete Report Scope:
- By Service Type
- Consolidation Services
- De-Consolidation and Distribution
- Documentation, Customs, and Compliance Services
- Value-Added Services
- By End User
- Manufacturing and Automotive
- Retail and E-Commerce
- Healthcare and Pharmaceuticals
- Electronics and Electrical Equipment
- Chemicals and Petrochemicals
- Agriculture and Forestry
- Other Industries
- By Cargo Type
- Dry and General Cargo
- Reefer and Temperature-Controlled Cargo
- Dangerous Goods
- High-Value and Security-Sensitive Cargo
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Peru
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Nordics (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Southeast Asia (ASEAN)
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Qatar
- South Africa
- Nigeria
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific held 35.80% of the NVOCC ocean groupage market share in 2026 and is forecast to register a 7.78% CAGR through 2032. China, Vietnam, India, South Korea, and the wider ASEAN region generate the largest concentration of export-side LCL freight. The region also produces inbound demand as consumer spending and e-commerce grow. These two-way flows support higher sailing frequency and more reliable cargo matching. The NVOCC ocean groupage consolidation market benefits when both import and export loads exist on the same lanes. Inland rail, road, and port connections can extend the cargo catchment area of ASEAN consolidation hubs. Such links allow smaller exporters to reach regular ocean consolidation services.
North America and Europe remain the next-largest geographic groups. The USMCA area produces cross-border demand among the United States, Mexico, and Canada as sourcing patterns become more regional. European ports including Rotterdam, Antwerp, and Hamburg serve as origin and de-consolidation locations for Asia-Europe trade. Middle East and Africa is smaller but is gaining more formal NVOCC coverage through port and inland logistics investment. Jebel Ali remains an important regional hub for shared-container freight. South America also offers room for development as trade links with Europe deepen. Service quality in these locations depends on terminal capacity, customs administration, and regular sailing schedules.
- ECU Worldwide (Part of Allcargo Logistics)
- Vanguard Logistics Services
- Shipco Transport
- Rhenus Logistics
- Kuehne + Nagel
- DHL Global Forwarding
- DSV A/S
- CEVA Logistics
- GEODIS
- Sinotrans Limited
- NIPPON EXPRESS HOLDINGS, INC.
- Yusen Logistics Co., Ltd.
- JAS Worldwide
- Hellmann Worldwide Logistics SE & Co. KG
- Expeditors International of Washington, Inc.
- Savino Del Bene S.p.A.
- Scan Global Logistics
- DACHSER SE
- CWT Globelink
- Kintetsu World Express, Inc.
- Dimerco Express Corporation
- Kerry Logistics Network Limited
- OEC Group
- Amass Global Network
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cross-Border E-Commerce and Smaller Shipment Batches
- 4.2.2 SME Export Participation and Sourcing Diversification
- 4.2.3 Ocean Cost Advantage for Non-Urgent Cargo
- 4.2.4 API-Enabled Booking, Documentation, and Shipment Visibility
- 4.2.5 Multi-Origin Sourcing and Micro-Consolidation Density
- 4.2.6 Free-Trade Agreements and Port-Hinterland Connectivity
- 4.3 Market Restraints
- 4.3.1 Port Congestion and Schedule Unreliability
- 4.3.2 Ocean-Rate Volatility and Variable Container Utilization
- 4.3.3 Customs, Security, and Mixed-Consignment Compliance
- 4.3.4 Carbon Accounting and Data-Traceability Burden
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Geopolitical Events on the Market
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Service Type
- 5.1.1 Consolidation Services
- 5.1.2 De-Consolidation and Distribution
- 5.1.3 Documentation, Customs, and Compliance Services
- 5.1.4 Value-Added Services
- 5.2 By End User
- 5.2.1 Manufacturing and Automotive
- 5.2.2 Retail and E-Commerce
- 5.2.3 Healthcare and Pharmaceuticals
- 5.2.4 Electronics and Electrical Equipment
- 5.2.5 Chemicals and Petrochemicals
- 5.2.6 Agriculture and Forestry
- 5.2.7 Other Industries
- 5.3 By Cargo Type
- 5.3.1 Dry and General Cargo
- 5.3.2 Reefer and Temperature-Controlled Cargo
- 5.3.3 Dangerous Goods
- 5.3.4 High-Value and Security-Sensitive Cargo
- 5.3.5 Others
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Peru
- 5.4.2.4 Chile
- 5.4.2.5 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Nordics (Denmark, Finland, Iceland, Norway, and Sweden)
- 5.4.3.8 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 India
- 5.4.4.3 Japan
- 5.4.4.4 South Korea
- 5.4.4.5 Australia
- 5.4.4.6 Southeast Asia (ASEAN)
- 5.4.4.7 Rest of Asia-Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Qatar
- 5.4.5.4 South Africa
- 5.4.5.5 Nigeria
- 5.4.5.6 Egypt
- 5.4.5.7 Rest of Middle East and Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Key Strategic Moves in the Market
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Geographic/Network Coverage, Products and Services, Recent Developments)
- 6.4.1 ECU Worldwide (Part of Allcargo Logistics)
- 6.4.2 Vanguard Logistics Services
- 6.4.3 Shipco Transport
- 6.4.4 Rhenus Logistics
- 6.4.5 Kuehne + Nagel
- 6.4.6 DHL Global Forwarding
- 6.4.7 DSV A/S
- 6.4.8 CEVA Logistics
- 6.4.9 GEODIS
- 6.4.10 Sinotrans Limited
- 6.4.11 NIPPON EXPRESS HOLDINGS, INC.
- 6.4.12 Yusen Logistics Co., Ltd.
- 6.4.13 JAS Worldwide
- 6.4.14 Hellmann Worldwide Logistics SE & Co. KG
- 6.4.15 Expeditors International of Washington, Inc.
- 6.4.16 Savino Del Bene S.p.A.
- 6.4.17 Scan Global Logistics
- 6.4.18 DACHSER SE
- 6.4.19 CWT Globelink
- 6.4.20 Kintetsu World Express, Inc.
- 6.4.21 Dimerco Express Corporation
- 6.4.22 Kerry Logistics Network Limited
- 6.4.23 OEC Group
- 6.4.24 Amass Global Network
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

