PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2186098

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2186098
Lithium-Ion Battery Transportation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
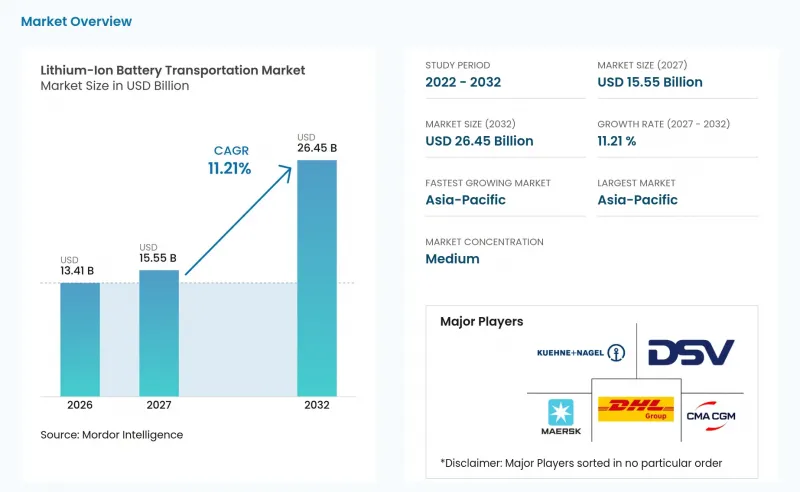
According to Mordor Intelligence, the Lithium-Ion battery transportation market size was valued at USD 13.41 billion in 2026 and is estimated to grow from USD 15.55 billion in 2027 to reach USD 26.45 billion by 2032, at a CAGR of 11.21% during the forecast period (2027-2032).
Global Lithium-Ion Battery Transportation Market Trends and Insights
Electrification of Vehicles, Consumer Electronics, and Energy Storage
The lithium-ion battery transportation market benefits from higher movement volumes across vehicle, electronics, and stationary storage supply chains. The International Energy Agency expects global electric-vehicle battery demand to exceed 3 TWh by 2030 under its Stated Policies Scenario. Larger battery packs increase shipment weight, packaging needs, and documentation requirements for each unit transported. North American electric vehicles carry battery packs that are larger than European equivalents, which raises handling requirements on many routes. Consumer electronics and battery energy storage systems add shipment needs across more than one product category. This breadth gives the lithium-ion battery transportation market a wider demand base than one dependent only on passenger electric vehicles.
Cross-Border Battery Manufacturing and Trade Expansion
The lithium-ion battery transportation market depends on cross-border movement because production capacity and end demand remain in different locations. Battery exports from China reached record levels in 2025, with 114 countries or territories each buying at least USD 10 million of Chinese batteries through September. European and U.S. capacity additions will change trade patterns, but ramp-up periods still require inbound cells and materials from Asia. China restricted overseas transfers of 8 battery manufacturing technologies in July 2025, including Lithium Iron Phosphate (LFP) cathode production processes. Existing supply relationships and the freight networks serving them therefore remain commercially important. The lithium-ion battery transportation market will continue to adjust as trade moves are redistributed rather than removed.
Thermal Runaway and Fire-Liability Exposure
Thermal runaway presents a safety and liability constraint for the lithium-ion battery transportation market. The National Transportation Safety Board found that improperly secured battery energy storage system units shifted during heavy weather aboard Genius Star XI in 2025, triggering thermal runaway in 3 units and 2 cargo-hold fires. The incident caused USD 3.8 million in damage. The Morning Midas fire also drew attention to the difficulty of stopping thermal runaway after it spread through cells. Ocean and air carriers must account for fire risk when setting acceptance criteria, packaging standards, and cargo positions. This leaves a continuing operational constraint in the lithium-ion battery transportation market, especially for high-energy battery loads.
Other drivers and restraints analyzed in the detailed report include:
- Specialized Dangerous-Goods Compliance and Certified Packaging Demand
- Reverse Logistics and Battery Traceability Requirements
- Fragmented Cross-Border Dangerous-Goods Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Roadways accounted for 45.2% of the lithium-ion battery transportation market size in 2026. Truck transport supports domestic and regional trips between gigafactories, assembly plants, distribution centers, service networks, and recycling facilities. Road carriers can provide direct pickup and delivery, which reduces handoffs for time-sensitive or high-value battery shipments. European Agreement concerning the International Carriage of Dangerous Goods by Road (ADR) compliance is widely understood among established, which supports carrier qualification for these movements. The road segment of the lithium-ion battery transportation industry remains important because most battery supply chains require a road leg before or after another mode.
Multimodal transport is projected to grow at an 11.3% CAGR from 2027 to 2032. Integrated providers can combine air, sea, road, and rail when lead time, cost, disruption exposure, and documentation need to be balanced. Battery passport requirements create a need for auditable data during each modal handoff under Regulation (EU) 2023/1542. Kuehne+Nagel identifies sea-air combinations as one option for reducing dependency on a single mode. Airways serve urgent, lower-volume movements, while waterways remain necessary for major intercontinental flows. Railways offer a lower-emission continental option where route capability and rules allow. Prototype batteries require bespoke handling across every mode because special provisions and unit-specific controls can apply.
Complete Report Scope:
- By Transport Mode
- Roadways
- Airways
- Waterways
- Railways
- Multimodal Transport
- By Battery Status
- New Cells and Packs
- Used and Returned Batteries
- Damaged and Defective Batteries
- Prototype Batteries
- End-of-life Batteries
- By End User
- Battery and Vehicle OEMs
- Cell and Pack Manufacturers
- Distributors and Dealers
- Recyclers and Second-life Operators
- Government and Defense Organizations
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- Italy
- Spain
- United Kingdom
- Poland
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Vietnam
- Thailand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- South Africa
- Morocco
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific held 44.3% of the lithium-ion battery transportation market share in 2026. China remains central to regional and global battery movements because its export base serves a broad range of destinations. China's 2025 export controls on cathodes, graphite anodes, and battery-related technology require permits and add compliance work to trade flows. South Korea and Japan supply high-value Nickel Manganese Cobalt (NMC) and specialty cells to vehicle producers in North America and Europe. Vietnam, Thailand, and Indonesia are moving toward broader assembly and logistics roles. Indonesia's support for Lithium Iron Phosphate (LFP)-related materials and electric-vehicle adoption points to further regional production dispersion. These changes add routes to the lithium-ion battery transportation market rather than replacing China-linked trade lanes.
Europe is shaped by production activity and a detailed regulatory framework. The EU battery passport requirement begins in February 2027 for covered batteries. This is encouraging logistics investment in traceable storage, handling, and reporting systems. DHL Supply Chain began construction in May 2026 on a 17,000 m2 Battery Logistics Hub in Holtum, Netherlands, for high-voltage battery storage and service. Germany, France, Poland, and the United Kingdom serve as major nodes because of their manufacturing links and established ADR-certified carrier networks. Morocco's announced battery-related investment base creates a North Africa-Europe corridor linked to phosphate resources, trade agreements, and automotive production. The lithium-ion battery transportation market in Europe therefore places unusual importance on regulatory readiness and regional storage capacity.
North American movement is shaped by domestic-content aims and persistent cross-border supply requirements. Maersk estimated U.S. lithium-ion battery transportation spending at USD 2.4 billion to USD 3.0 billion in June 2026. United States, Canadian, and Mexican transport rules create a demanding compliance environment for carriers operating across the region. South America supports outbound mineral movements from Chile, Argentina, and Brazil toward Asian and European processing locations. The Middle East and Africa remain smaller contributors today, but Morocco's investment pipeline and Gulf battery energy storage projects support incremental demand. These regions add sourcing, manufacturing, and deployment routes that widen the geographic scope of the lithium-ion battery transportation market.
- A.P. Moller - Maersk
- Bertling Logistics
- C.H. Robinson Worldwide, Inc.
- CMA CGM Group
- DGD Transport
- DHL Group
- DSV A/S
- Expeditors International of Washington, Inc.
- FedEx Corporation
- GEODIS
- GXO Logistics, Inc.
- Hellmann Worldwide Logistics SE & Co. KG
- Kintetsu World Express, Inc.
- Kuehne + Nagel International AG
- Nippon Express Holdings, Inc.
- Rhenus Group
- Sinotrans Limited
- Toll Group
- United Parcel Service, Inc. (UPS)
- Yusen Logistics Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Electrification of Vehicles, Consumer Electronics and Energy Storage
- 4.2.2 Cross-Border Battery Manufacturing and Trade Expansion
- 4.2.3 Specialized Dangerous-Goods Compliance and Certified Packaging Demand
- 4.2.4 Reverse Logistics Growth From Battery Replacement and Recycling
- 4.2.5 State-of-Health Data as a Logistics Service Differentiator
- 4.2.6 Battery Passport and Chain-of-Custody Requirements
- 4.3 Market Restraints
- 4.3.1 Thermal Runaway and Fire-Liability Exposure
- 4.3.2 Fragmented Cross-Border Dangerous-Goods Requirements
- 4.3.3 Limited Certified Capacity and Specialized Warehousing
- 4.3.4 Uncertain Classification of Damaged, Defective and Recalled Batteries
- 4.4 Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Transport Mode
- 5.1.1 Roadways
- 5.1.2 Airways
- 5.1.3 Waterways
- 5.1.4 Railways
- 5.1.5 Multimodal Transport
- 5.2 By Battery Status
- 5.2.1 New Cells and Packs
- 5.2.2 Used and Returned Batteries
- 5.2.3 Damaged and Defective Batteries
- 5.2.4 Prototype Batteries
- 5.2.5 End-of-life Batteries
- 5.3 By End User
- 5.3.1 Battery and Vehicle OEMs
- 5.3.2 Cell and Pack Manufacturers
- 5.3.3 Distributors and Dealers
- 5.3.4 Recyclers and Second-life Operators
- 5.3.5 Government and Defense Organizations
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 France
- 5.4.2.3 Italy
- 5.4.2.4 Spain
- 5.4.2.5 United Kingdom
- 5.4.2.6 Poland
- 5.4.2.7 Russia
- 5.4.2.8 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Indonesia
- 5.4.3.7 Vietnam
- 5.4.3.8 Thailand
- 5.4.3.9 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Chile
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Egypt
- 5.4.5.4 South Africa
- 5.4.5.5 Morocco
- 5.4.5.6 Rest of Middle East and Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 A.P. Moller - Maersk
- 6.4.2 Bertling Logistics
- 6.4.3 C.H. Robinson Worldwide, Inc.
- 6.4.4 CMA CGM Group
- 6.4.5 DGD Transport
- 6.4.6 DHL Group
- 6.4.7 DSV A/S
- 6.4.8 Expeditors International of Washington, Inc.
- 6.4.9 FedEx Corporation
- 6.4.10 GEODIS
- 6.4.11 GXO Logistics, Inc.
- 6.4.12 Hellmann Worldwide Logistics SE & Co. KG
- 6.4.13 Kintetsu World Express, Inc.
- 6.4.14 Kuehne + Nagel International AG
- 6.4.15 Nippon Express Holdings, Inc.
- 6.4.16 Rhenus Group
- 6.4.17 Sinotrans Limited
- 6.4.18 Toll Group
- 6.4.19 United Parcel Service, Inc. (UPS)
- 6.4.20 Yusen Logistics Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

