PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187189

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187189
Vietnam Plastics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
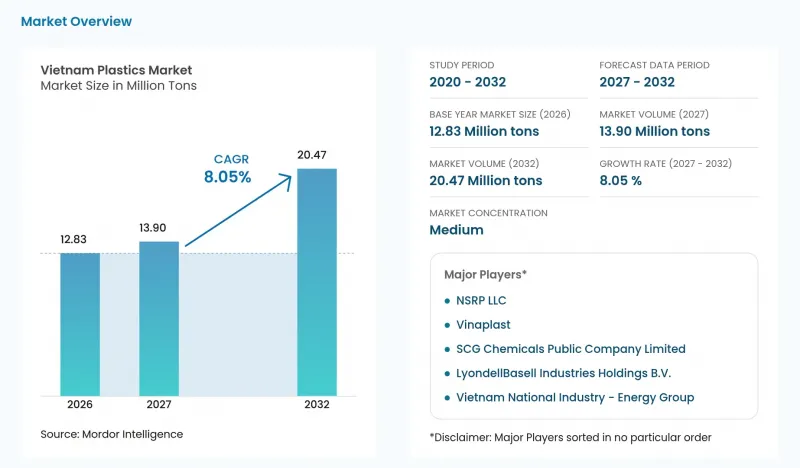
According to Mordor Intelligence, the Vietnam plastics market size was valued at 12.83 million tons in 2026 and estimated to grow from 13.9 million tons in 2027 to reach 20.47 million tons by 2032, at a CAGR of 8.05% during the forecast period (2027-2032).
This report is segmented by Type (Traditional Plastics, Bioplastics, and more), Technology (Extrusion, Injection Molding, and more), and Application (Packaging, Building and Construction, and more). The market forecasts are provided in terms of volume (tons), based on availability.
Vietnam Plastics Market Trends and Insights
Robust Growth in Domestic Construction Projects
Vietnam's construction industry value added grew 12.22% year over year in January-September 2026. Clean-water infrastructure provides a concrete route from construction activity to plastic-pipe orders. In 2025, Tien Phong Plastic supplied DN2000 HDPE pipes to the Song Da clean-water project, which included more than 6,000 meters of pipeline serving western Hanoi communities. That pipeline was equivalent to nearly 500 pipe sections, giving the large-diameter format a repeated role within one infrastructure program. Water-utility projects create a specification-led outlet for DN2000 HDPE pipe producers that is distinct from the broader construction cycle.
Booming Food-grade & E-commerce Packaging Demand
Food packaging creates recurring conversion work as goods move through production. Vietnam's flexible plastic packaging volume was projected at approximately 0.25 million tons in 2025, with demand concentrated in processed food, seafood, and healthcare. E-commerce operators create a separate dispatch-packaging opportunity whose plastic requirement depends on the material and format selected. Flexible packaging therefore ties converter resin demand to processed-food, seafood and healthcare production.
Heavy Dependence on Imported Naphtha and Propylene
Input dependence exposes Vietnamese converters to supply risk and to the cost of imported resin. In May 2025, industry reporting put imported raw and auxiliary materials at 70% of Vietnam's plastics inputs and identified raw materials as the industry's largest cost component. Following the Iran-USA-Israel conflict that began February 28, 2026, Middle Eastern crude-oil and petrochemical-feedstock export constraints affected Tien Phong Plastic's resin availability in Vietnam. By the end of March 2026, Tien Phong Plastic reported PVC, HDPE and PPR resin prices more than 65%, 69% and 57% above their respective 2025 averages, with limited availability. Raw materials were 74.6% of its total costs, making the March resin-price shock a direct source of margin pressure.
Other drivers and restraints analyzed in the detailed report include:
- Rising Foreign Direct Investment in Downstream Resin Conversion
- Surge in Automotive & Electronics Relocation to Vietnam
- Escalating Environmental Activism Against Single-use Plastics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Traditional plastics accounted for a 50.33% share of the Vietnam plastics market size in 2026, making it the largest segment. In February 2026, Long Son Petrochemicals reported monthly output of around 100,000 metric tons of resins following its August 2025 restart, including HDPE, LLDPE, and PP. About half of that output served Vietnam's domestic market, with the rest exported. These PE and PP resins have applications in packaging, agriculture, electrical appliances, and automotive production. Serving multiple conversion industries gives traditional resins several channels for absorbing high-volume production, supporting their commercial scale beyond a single end use.
Bioplastics is the fastest-growing segment, with a forecast 12.2% CAGR during 2027-2032. In November 2025, TotalEnergies Corbion appointed Vichem as its official Luminy PLA distribution partner in Vietnam. Vichem gives PLA buyers a named local source for Luminy grades and a defined route to the supplier's Vietnamese offering.
Complete Report Scope:
- By Type
- Traditional Plastics
- Polyethylene
- Polypropylene
- Polystyrene
- Poly Vinyl Chloride
- Engineering Plastics
- Polyurethanes
- Fluoropolymers
- Polyamides
- Polycarbonates
- Styrene Copolymers (ABS and SAN)
- Thermoplastic Polyesters
- Other Engineering Plastics
- Bioplastics
- Traditional Plastics
- By Technology
- Blow Molding
- Extrusion
- Injection Molding
- Other Technologies
- By Application
- Packaging
- Electrical and Electronics
- Building and Construction
- Automotive and Transportation
- Housewares
- Furniture and Bedding
- Other Applications
List of Companies Covered in this Report:
- AGC Inc.
- Billion Industrial Holdings Limited
- Far Eastern New Century Corporation
- Hyosung Chemical
- LyondellBasell Industries Holdings B.V.
- NAN YA PLASTICS CORPORATION
- NSRP LLC
- SCG Chemicals Public Company Limited
- SKC
- Toray Industries, Inc.
- Vietnam National Industry - Energy Group
- Vietnam Polystyrene Co., Ltd
- Vinaplast
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Robust Growth in Domestic Construction Projects
- 4.2.2 Booming Food-grade & E-commerce Packaging Demand
- 4.2.3 Rising Foreign Direct Investment in Downstream Resin Conversion
- 4.2.4 Surge in Automotive & Electronics Relocation to Vietnam
- 4.2.5 Government Incentives for Recycled-content Resins
- 4.3 Market Restraints
- 4.3.1 Heavy Dependence on Imported Naphtha and Propylene
- 4.3.2 Escalating Environmental Activism Against Single-use Plastics
- 4.3.3 Rising Competition from Bio-based Substitutes in FMCG
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Raw Material Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VOLUME)
- 5.1 By Type
- 5.1.1 Traditional Plastics
- 5.1.1.1 Polyethylene
- 5.1.1.2 Polypropylene
- 5.1.1.3 Polystyrene
- 5.1.1.4 Poly Vinyl Chloride
- 5.1.2 Engineering Plastics
- 5.1.2.1 Polyurethanes
- 5.1.2.2 Fluoropolymers
- 5.1.2.3 Polyamides
- 5.1.2.4 Polycarbonates
- 5.1.2.5 Styrene Copolymers (ABS and SAN)
- 5.1.2.6 Thermoplastic Polyesters
- 5.1.2.7 Other Engineering Plastics
- 5.1.3 Bioplastics
- 5.1.1 Traditional Plastics
- 5.2 By Technology
- 5.2.1 Blow Molding
- 5.2.2 Extrusion
- 5.2.3 Injection Molding
- 5.2.4 Other Technologies
- 5.3 By Application
- 5.3.1 Packaging
- 5.3.2 Electrical and Electronics
- 5.3.3 Building and Construction
- 5.3.4 Automotive and Transportation
- 5.3.5 Housewares
- 5.3.6 Furniture and Bedding
- 5.3.7 Other Applications
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 AGC Inc.
- 6.4.2 Billion Industrial Holdings Limited
- 6.4.3 Far Eastern New Century Corporation
- 6.4.4 Hyosung Chemical
- 6.4.5 LyondellBasell Industries Holdings B.V.
- 6.4.6 NAN YA PLASTICS CORPORATION
- 6.4.7 NSRP LLC
- 6.4.8 SCG Chemicals Public Company Limited
- 6.4.9 SKC
- 6.4.10 Toray Industries, Inc.
- 6.4.11 Vietnam National Industry - Energy Group
- 6.4.12 Vietnam Polystyrene Co., Ltd
- 6.4.13 Vinaplast
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

