PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187202

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187202
Asia-Pacific Beauty and Personal Care Products - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the Asia-Pacific beauty and personal care products market size is expected to grow from USD 159.3 billion in 2026 to USD 169.5 billion in 2027 and is forecast to reach USD 228.7 billion by 2032 at 6.18% CAGR over 2027-2032.
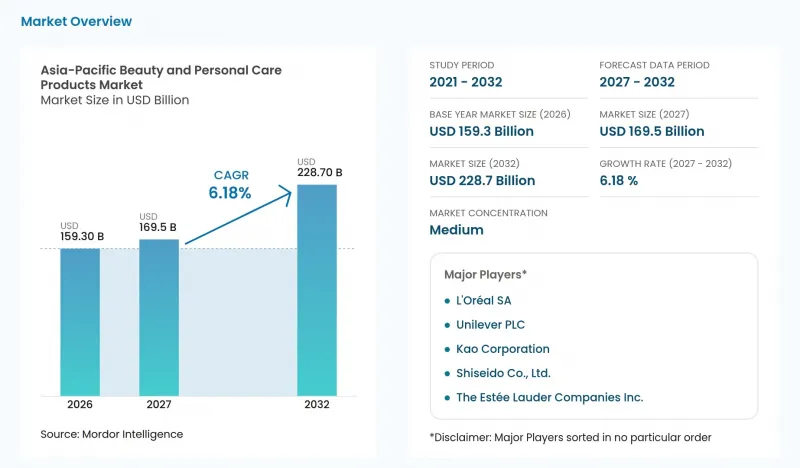
This report is segmented by Product Type (Personal Care Products and more), Category (Mass Products and more), Ingredient Type (Conventional/Synthetic and more), Distribution Channel (Health & Beauty Stores and more), and Geography (China and more). The market forecasts are provided in terms of value (USD), based on availability.
Asia-Pacific Beauty and Personal Care Products Market Trends and Insights
Rising demand for premium and natural beauty products
Premium beauty growth gives suppliers a reason to distinguish channel expansion from country selection. L'Oreal Luxe reported growth close to 5% in Asia outside Travel Retail in the second half of 2025. In the first half of 2026, North Asia was the division's largest growth contributor, boosted by double-digit growth in China. The earlier result concerns non-travel business across Asia, while the later reading locates a country contribution within North Asia. This pairing favors premium launch support concentrated on Asian non-travel channels and on China, rather than a plan dependent entirely on travel-retail demand.
Increasing beauty and self-care awareness among consumers
Self-care awareness supports skincare demand when consumers use products to address continuing skin-health needs rather than appearance alone. In a multiple-response survey of MyVoice online panelists in Japan conducted August 1-7, 2026, 47.2% of skincare and cosmetics users cited keeping skin healthy or addressing skin concerns. Shiseido reported that Elixir's 2025 sales value in Japan grew by double digits versus 2024, measured by customer purchasing behavior. Elixir is positioned as an aging-care skincare brand. For suppliers serving Japan, organizing a skincare range by the concern it addresses connects product development to an expressed use motive.
Stringent regulatory requirements and compliance challenges
Assortment breadth creates a regulatory workload before an imported cosmetics range can reach Indian buyers. India's Central Drugs Standard Control Organization requires pre-import registration covering cosmetics, pack sizes, variants, and manufacturing premises. For a brand considering several variants, the relevant entry decision therefore extends beyond whether a single formula is commercially attractive. Because registration also covers manufacturing premises, an importer's range is tied to specific production sites before the first shipment.
Other drivers and restraints analyzed in the detailed report include:
- Growing influence of social media and beauty influencers
- Increasing male grooming and inclusive beauty trends
- Supply chain disruptions and raw material price volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Personal care products were the largest segment, holding 84.96% of the market in 2026. Hindustan Unilever Limited (HUL) reported INR 95.67 billion (USD 1.08 billion) in audited standalone Personal Care segment revenue from sales and other operating revenue in FY2025-26. An entrant in India therefore encounters a personal-care incumbent with annual segment revenue above USD 1 billion, which makes competing for an existing consumer franchise the relevant scale challenge.
Cosmetics/makeup products are the fastest-growing segment, with a forecast 7.3% CAGR over 2027-2032. Mao Geping Cosmetics reported company-level color-cosmetics sales volume of 12.5 million units in the first half of 2026, compared with 9.06 million in the first half of 2025. Separately, Yatsen's Color Cosmetics Brands net revenues fell 35.8% year over year in the second quarter of 2026. These company outcomes show different commercial directions, with an expanding unit-sales business alongside a contracting brand-revenue portfolio. Segment growth therefore leaves distinct tasks for suppliers, scaling delivery where product volumes rise and addressing weaker brand revenues where an individual commercial business has contracted.
Mass products accounted for a 75.06% share of the Asia-Pacific beauty and personal care products market size in 2026, making them the largest segment. In January 2026, Unilever described Sunsilk as a mass hair-care line. In June 2026, HUL hair-care vice president Sairam Subramanian reported that Sunsilk reached half of Indian households. The combination of mass positioning and extensive household reach shows how a brand can participate in this category through a broad consumer-facing business. An existing mass hair-care line can therefore provide a platform for product development aimed at a wide household audience, giving brand reach a role beyond the sales of an individual item.
Premium products are the fastest-growing segment, with a forecast 7.6% CAGR over 2027-2032. For the quarter ended June 30, 2026, Yatsen reported strong skincare-portfolio growth led by clinical and premium brands including Galenic, its mainland China DR.WU business, and Eve Lom. That performance supports product development around differentiated skincare propositions within Yatsen's growing portfolio. The company also described optimization of its brand portfolio and distribution channels. For this portfolio, brand selection and channel optimization are linked decisions about which premium skincare offers buyers can reach.
Complete Report Scope:
- By Product Type
- Personal Care Products
- Hair Care
- Shampoo
- Conditioner
- Hair Colourant
- Hair Styling Products
- Others
- Skin Care
- Facial Care Products
- Body Care Products
- Lip and Nail Care Products
- Bath and Shower
- Shower Gels
- Soaps
- Others
- Oral Care
- Toothbrush
- Toothpaste
- Mouthwashes and Rinses
- Others
- Men's Grooming Products
- Deodorants and Antiperspirants
- Perfumes and Fragrances
- Hair Care
- Cosmetics/Make-up Products
- Facial Cosmetics
- Eye Cosmetics
- Lip and Nail Make-up Products
- Personal Care Products
- By Category
- Premium Products
- Mass Products
- By Ingredient Type
- Natural and Organic
- Conventional/Synthetic
- By Distribution Channel
- Health & Beauty Stores
- Supermarkets/Hypermarkets
- Online Retail Stores
- Other Channels
- By Geography
- China
- India
- Japan
- Australia
- Indonesia
- South Korea
- Thailand
- Singapore
- Rest of Asia-Pacific
List of Companies Covered in this Report:
- L'Oreal SA
- Shiseido Co., Ltd.
- Unilever PLC
- The Estee Lauder Companies Inc.
- Kao Corporation
- Amorepacific Group
- The Procter & Gamble Company
- Beiersdorf AG
- LG Household & Health Care Ltd.
- Kenvue, Inc.
- Coty Inc.
- The Colgate-Palmolive Company
- Henkel AG & Co. KGaA
- Natura Cosmeticos S.A.
- Revlon Group Holdings LLC
- Chanel SA
- LVMH Moet Hennessy Louis Vuitton
- Clarins Groupe
- Colorbar Cosmetics Pvt. Ltd.
- Honasa Consumer Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for premium and natural beauty products
- 4.2.2 Increasing beauty and self-care awareness among consumers
- 4.2.3 Growing influence of social media and beauty influencers
- 4.2.4 Increasing male grooming and inclusive beauty trends
- 4.2.5 Technological innovations in beauty and skincare formulations
- 4.2.6 Growing demand for anti-aging and personalized beauty solutions
- 4.3 Market Restraints
- 4.3.1 Stringent regulatory requirements and compliance challenges
- 4.3.2 Supply chain disruptions and raw material price volatility
- 4.3.3 Counterfeit and unbranded product market growth
- 4.3.4 Environmental concerns over packaging waste and chemicals
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Consumer Behaviour Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Personal Care Products
- 5.1.1.1 Hair Care
- 5.1.1.1.1 Shampoo
- 5.1.1.1.2 Conditioner
- 5.1.1.1.3 Hair Colourant
- 5.1.1.1.4 Hair Styling Products
- 5.1.1.1.5 Others
- 5.1.1.2 Skin Care
- 5.1.1.2.1 Facial Care Products
- 5.1.1.2.2 Body Care Products
- 5.1.1.2.3 Lip and Nail Care Products
- 5.1.1.3 Bath and Shower
- 5.1.1.3.1 Shower Gels
- 5.1.1.3.2 Soaps
- 5.1.1.3.3 Others
- 5.1.1.4 Oral Care
- 5.1.1.4.1 Toothbrush
- 5.1.1.4.2 Toothpaste
- 5.1.1.4.3 Mouthwashes and Rinses
- 5.1.1.4.4 Others
- 5.1.1.5 Men's Grooming Products
- 5.1.1.6 Deodorants and Antiperspirants
- 5.1.1.7 Perfumes and Fragrances
- 5.1.1.1 Hair Care
- 5.1.2 Cosmetics/Make-up Products
- 5.1.2.1 Facial Cosmetics
- 5.1.2.2 Eye Cosmetics
- 5.1.2.3 Lip and Nail Make-up Products
- 5.1.1 Personal Care Products
- 5.2 By Category
- 5.2.1 Premium Products
- 5.2.2 Mass Products
- 5.3 By Ingredient Type
- 5.3.1 Natural and Organic
- 5.3.2 Conventional/Synthetic
- 5.4 By Distribution Channel
- 5.4.1 Health & Beauty Stores
- 5.4.2 Supermarkets/Hypermarkets
- 5.4.3 Online Retail Stores
- 5.4.4 Other Channels
- 5.5 By Geography
- 5.5.1 China
- 5.5.2 India
- 5.5.3 Japan
- 5.5.4 Australia
- 5.5.5 Indonesia
- 5.5.6 South Korea
- 5.5.7 Thailand
- 5.5.8 Singapore
- 5.5.9 Rest of Asia-Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 L'Oreal SA
- 6.4.2 Shiseido Co., Ltd.
- 6.4.3 Unilever PLC
- 6.4.4 The Estee Lauder Companies Inc.
- 6.4.5 Kao Corporation
- 6.4.6 Amorepacific Group
- 6.4.7 The Procter & Gamble Company
- 6.4.8 Beiersdorf AG
- 6.4.9 LG Household & Health Care Ltd.
- 6.4.10 Kenvue, Inc.
- 6.4.11 Coty Inc.
- 6.4.12 The Colgate-Palmolive Company
- 6.4.13 Henkel AG & Co. KGaA
- 6.4.14 Natura Cosmeticos S.A.
- 6.4.15 Revlon Group Holdings LLC
- 6.4.16 Chanel SA
- 6.4.17 LVMH Moet Hennessy Louis Vuitton
- 6.4.18 Clarins Groupe
- 6.4.19 Colorbar Cosmetics Pvt. Ltd.
- 6.4.20 Honasa Consumer Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

