PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187351

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187351
Engineering Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the engineering services market size is estimated at USD 1.81 trillion in 2026 and is projected to be USD 1.89 trillion in 2027, reaching USD 2.34 trillion by 2032, growing at a CAGR of 4.38% from 2027 to 2032.
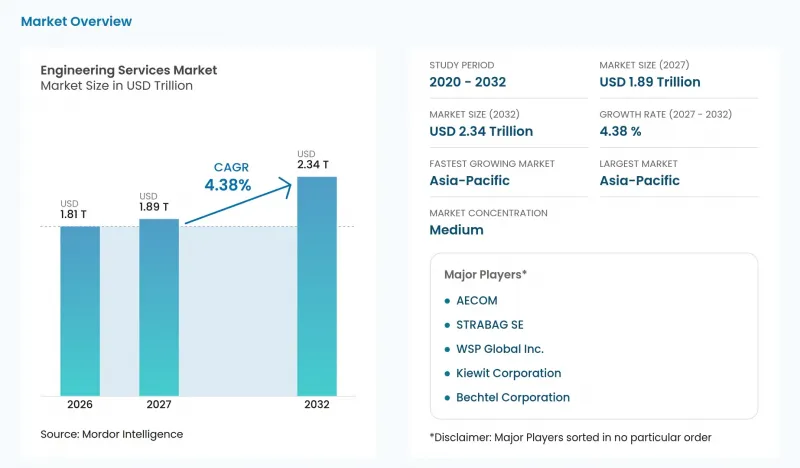
This report is segmented by Engineering Disciplines (Civil, Electrical, and more), Delivery Model (Onsite and Offshore), Services (Product Engineering, Automation Related Services, and more), End-user Industry (Oil and Gas, Transportation, and more), and Geography (Asia-Pacific, North America, and more). The market forecasts are provided in terms of value (USD), based on availability.
Global Engineering Services Market Trends and Insights
Evolution of Industrial IoT and Digital Twin Adoption
Digital engineering demand gains a practical foundation when connected systems become part of production rather than a demonstration. In Bitkom Research's 2026 survey of 555 German industrial companies with at least 100 employees, 45% reported production use of digital twins. The same survey separately recorded 45% using IoT platforms in production. For service providers, production deployment makes the relationship between operational data and engineering models a consequential integration task. Providers with plant-integration skills can address extensions and maintenance of these operating systems, making installed production applications a source of further engineering assignments.
Rapid Urbanization Spurring Civil Infrastructure Demand
Urban infrastructure financing creates engineering work when cities must coordinate several public services within a common development program. On December 15, 2025, the World Bank approved a USD 250 million financing package for municipal infrastructure and services in 16 districts and cities in Uzbekistan. Uzbekistan's Ministry of Economy and Finance and local authorities deliver the program, which responds to urbanization-related planning and service needs. For engineering providers, this combination makes coordination between municipal authorities and individual infrastructure designs commercially relevant. The opportunity extends beyond designing an isolated asset because service improvements must fit the wider urban development program.
Political Instability and Acute Skilled Labor Shortage
Engineering firms can face a growth ceiling even when customers have projects ready to commission. ACEC Research Institute findings reported in July 2026 showed that 84% of US engineering firms had open positions they were struggling to fill. The same findings showed that one-third of US engineering firms reported turning down work because of workforce shortages. This connects the staffing constraint directly to a provider's ability to accept assignments, rather than merely indicating recruitment activity. Stronger project demand cannot guarantee more deliverable work, leaving constrained suppliers exposed to foregone assignments until their staffing capacity expands.
Other drivers and restraints analyzed in the detailed report include:
- Accelerated Product Life-Cycle Driving Outsourced Research and Development
- Energy-Transition Mega-Projects (Hydrogen, CCUS) Requiring EPCM Expertise
- Input Cost and Supply-Chain Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Civil accounted for a 37.68% share of the engineering services market size in 2026, making it the largest segment. In July 2025, AECOM announced 3 architect-engineer indefinite-delivery, indefinite-quantity awards from the US Army Corps of Engineers Honolulu District, combining architectural design, civil design, and environmental planning across the Pacific region. That bundled scope makes civil design part of an infrastructure-planning assignment rather than an isolated drawing task. The buyer consequently needs civil work to fit architectural and environmental requirements within the same modernization program. Civil consultants address a broader commission when their designs resolve interfaces with the buyer's architectural and environmental work.
Electrical is the fastest-growing segment, with a projected CAGR of 5.12% from 2027 to 2032. In June 2025, Ireland's Commission for Regulation of Utilities selected TNEI Ireland Ltd for electricity engineering consultancy, with the contract concluded on July 11, 2025. The activity-based, drawdown contract covers support to Networks, Customer Policy and Protection, and Security of Supply divisions. This arrangement makes specialist engineering available against defined regulatory activities, rather than attaching the entire assignment to one physical development. Electrical consultants have an opening around the regulator's technical decisions, extending demand beyond the design of an individual generating asset.
Onsite was the largest delivery segment, with a 66.55% share in 2026. In 2025, New York City's Department of Design and Construction awarded HNTB New York Engineering and Architecture, P.C. a USD 50 million Type L requirements contract for resident engineering inspection on citywide infrastructure projects. A resident inspection assignment ties the service to physical work at the infrastructure site, giving local delivery a defined technical purpose. The citywide scope can also connect that responsibility to several infrastructure assignments within the same procurement framework. Resident inspection makes local presence part of the contracted engineering output, giving site-based providers an advantage in meeting the buyer's specified scope.
Offshore is the fastest-growing delivery segment, with a projected CAGR of 5.25% from 2027 to 2032. On June 12, 2025, Volvo Cars chose HCLTech as one of its strategic engineering-services suppliers, expanding an established digital and product life-cycle management relationship. Announced support was planned from HCLTech's Gothenburg automotive Center of Excellence and global offshore and nearshore delivery centers. That mixed configuration provides a way to allocate defined technical work across a broader delivery network while retaining a named automotive engineering center. Offshore growth can be embedded in a distributed service arrangement that combines several delivery locations, rather than requiring the wholesale relocation of a vehicle-development program.
Complete Report Scope:
- By Engineering Disciplines
- Civil
- Mechanical
- Electrical
- Piping and Structural
- By Delivery Model
- Offshore
- Onsite
- By Services
- Product Engineering
- Process Engineering
- Automation Related Services
- Asset Management Related Services
- By End-user Industry
- Aerospace and Defense
- Automotive
- Chemical and Petrochemical
- Electric Power Generation
- Municipal Utility Projects
- Mining
- Oil and Gas
- Pharmaceuticals
- Transportation
- Telecommunications
- Nuclear Projects
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Singapore
- Australia
- Malaysia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific held a 39.84% engineering services market share in 2026 and was the largest geography, while its projected CAGR of 5.32% from 2027 to 2032 makes it the fastest-growing geography. India's engineering-services exports rose from USD 1.77 billion in 2014-15 to USD 13.77 billion in 2024-25, a reported 22.8% CAGR from 2014-15 to 2024-25 in RBI data reported by NITI Aayog. In India, this export expansion illustrates a supply base within Asia-Pacific serving clients beyond its domestic economy. Overseas client access matters to providers considering India as a delivery location, since domestic project spending alone would understate their addressable work. Beyond the listed Asia-Pacific markets, Indonesia's PT Lapi Ganeshatama completed engineering services for Consortium Timas - Rekind (JO TR) on the Salak Unit 7 Development Project in 2025, illustrating local supply to consortium-led development.
In North America, Sound Transit selected AECOM in February 2026 for Seattle-area light rail, commuter rail, and bus projects, as design prime and environmental and project-management subconsultant under multiple-award task-order contracts. Europe presents a different public-infrastructure requirement, with the US Army Corps of Engineers Europe District selecting AECOM as prime in July 2025 for military infrastructure architecture and engineering. The 2 contracts covered Military Construction and Non-MILCON work in Germany, Poland, the Benelux region, Czech Republic, Norway, and Denmark. Transit networks and distributed military sites create distinct service requirements around network coordination and geographically dispersed infrastructure delivery.
In South America, thyssenkrupp Polysius secured a front-end engineering design contract from Circlua for an activated-clay plant in Brazil in January 2025. Paraguay's Ministry of Public Works and Communications also awarded consultancy for feasibility studies and final engineering design in 2026, illustrating a public-sector route to preconstruction services. In the Middle East and Africa, Sonatrach awarded Saipem one of 2 competing front-end engineering design contracts for an integrated Algerian phosphate and fertilizer project in June 2025. Its scope combined mining, processing, port facilities, and rail-link design, placing several industrial interfaces within the assignment. After the competing FEED awards, Saipem signed a limited notice to proceed with Sonatrach for phase one on August 12, 2026, permitting detailed engineering, long-lead procurement, and mobilization.
- AECOM
- Bechtel Corporation
- Kiewit Corporation
- WSP Global Inc.
- STRABAG SE
- Fluor Corporation
- Tetra Tech, Inc.
- Arcadis NV
- Stantec Inc.
- AtkinsRealis Group Inc.
- NV5 Global, Inc.
- Black & Veatch Holding Co.
- Balfour Beatty plc
- HDR, Inc.
- John Wood Group Limited
- China Communications Construction Co. Ltd.
- Gilbane Building Company
- Brasfield & Gorrie LLC
- Jacobs Solutions Inc.
- Barton Malow Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Evolution of Industrial IoT and Digital Twin Adoption
- 4.2.2 Rapid Urbanization Spurring Civil Infrastructure Demand
- 4.2.3 Accelerated Product Life-Cycle Driving Outsourced Research and Development
- 4.2.4 Energy-Transition Mega-Projects (Hydrogen, CCUS) Requiring EPCM Expertise
- 4.2.5 Net-Zero Building Retrofit Mandates in OECD Economies
- 4.2.6 Defense Drone and Hypersonic Programs Needing Specialized Engineering
- 4.3 Market Restraints
- 4.3.1 Political Instability and Acute Skilled Labor Shortage
- 4.3.2 Input Cost and Supply-Chain Volatility
- 4.3.3 IP Security Concerns Limiting Defense Outsourcing
- 4.3.4 Slow Permitting for Utility-Scale Renewables
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Assessment of Macro-economic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Engineering Disciplines
- 5.1.1 Civil
- 5.1.2 Mechanical
- 5.1.3 Electrical
- 5.1.4 Piping and Structural
- 5.2 By Delivery Model
- 5.2.1 Offshore
- 5.2.2 Onsite
- 5.3 By Services
- 5.3.1 Product Engineering
- 5.3.2 Process Engineering
- 5.3.3 Automation Related Services
- 5.3.4 Asset Management Related Services
- 5.4 By End-user Industry
- 5.4.1 Aerospace and Defense
- 5.4.2 Automotive
- 5.4.3 Chemical and Petrochemical
- 5.4.4 Electric Power Generation
- 5.4.5 Municipal Utility Projects
- 5.4.6 Mining
- 5.4.7 Oil and Gas
- 5.4.8 Pharmaceuticals
- 5.4.9 Transportation
- 5.4.10 Telecommunications
- 5.4.11 Nuclear Projects
- 5.4.12 Other End-user Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 Singapore
- 5.5.4.5 Australia
- 5.5.4.6 Malaysia
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 AECOM
- 6.4.2 Bechtel Corporation
- 6.4.3 Kiewit Corporation
- 6.4.4 WSP Global Inc.
- 6.4.5 STRABAG SE
- 6.4.6 Fluor Corporation
- 6.4.7 Tetra Tech, Inc.
- 6.4.8 Arcadis NV
- 6.4.9 Stantec Inc.
- 6.4.10 AtkinsRealis Group Inc.
- 6.4.11 NV5 Global, Inc.
- 6.4.12 Black & Veatch Holding Co.
- 6.4.13 Balfour Beatty plc
- 6.4.14 HDR, Inc.
- 6.4.15 John Wood Group Limited
- 6.4.16 China Communications Construction Co. Ltd.
- 6.4.17 Gilbane Building Company
- 6.4.18 Brasfield & Gorrie LLC
- 6.4.19 Jacobs Solutions Inc.
- 6.4.20 Barton Malow Company
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

