PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187412

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187412
Indonesia Coal - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
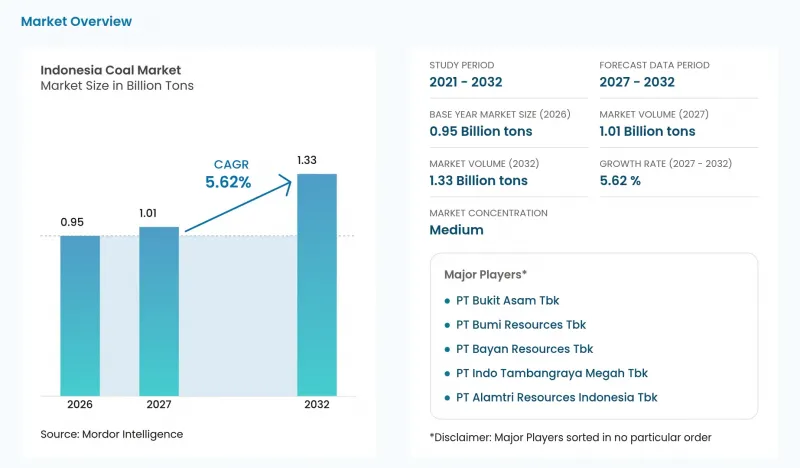
According to Mordor Intelligence, the Indonesia coal market size is expected to increase from 0.95 billion tons in 2026 to 1.01 billion tons in 2027 and reach 1.33 billion tons by 2032, growing at a CAGR of 5.62% over 2027-2032.
This report is segmented by Coal Grade (Sub-bituminous, Bituminous and Coking, and Lignite/Low-Rank) and Application (Power Generation, Iron, Steel, and Metallurgy, and Cement and Other Applications). The market forecasts are provided in terms of volume (tons), based on availability.
Indonesia Coal Market Trends and Insights
Prolonged PLN-led baseload demand for low-CV thermal coal
PT PLN (Persero), Indonesia's state electricity utility known as PLN, can create additional outlets for low-calorific-value coal through changes in its fleet's fuel capability. In July 2026, PLN said a successful retrofit of Suralaya units 6 and 7 allowed the plants to use low-rank coal at about 4,100-4,300 kcal/kg. The modification widens the usable fuel range at those units, giving lower-calorific coal a route into existing generating equipment. Broader coal deliveries to Indonesian power plants rose from 133.5 million metric tons in 2024 to 141.4 million metric tons in 2025. A joint operation of PT Arutmin Indonesia and PT Darma Henwa Tbk has contracted to supply PLN's Suralaya plants with 1.305 million metric tons of low-rank coal annually from 2009 through 2028.
Surge in coal-fired captive power for nickel & EV-battery smelters
Nickel processing connects coal demand to industrial power requirements alongside the utility system. In 2025, Indonesian nickel processing used more than 81 TWh of captive power, with over 94% generated from coal, according to Ember's estimate. Operational captive coal capacity linked to the nickel industry rose from 7.16 GW in 2023 to 15.4 GW in 2025. This larger operating base gives coal suppliers an industrial outlet whose fuel requirements depend on smelter operations, extending demand beyond PLN's purchasing needs. Suppliers can size contracts around operating smelters' fuel needs, with lower utilization reducing offtake even if no generating units close.
Mandatory Domestic Market Obligation (DMO) price caps
The DMO price cap constrains the economics of supplying PLN when mining costs rise. In June 2026, Indonesia's USD 70-per-metric-ton cap on DMO coal supplied to PLN reduced producers' economic incentive to allocate coal domestically as production costs rose. Stripping ratios at some mines rose to between 10 and 12, raising production costs while the price PLN pays stayed capped. The constraint is most acute for the mines with the higher stripping burden. Higher utility fuel needs cannot restore miners' cost recovery when additional regulated deliveries retain the same price ceiling.
Other drivers and restraints analyzed in the detailed report include:
- China-plus-One strategy shifting seaborne demand to Indonesia
- Government "Gasification & DME" incentives for low-rank coal
- Proposed accelerated coal-plant retirement under JETP funding
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Sub-bituminous coal accounted for a 47.15% share of the Indonesia coal market size in 2026, making it the largest segment. PT Arutmin Indonesia, a PT Bumi Resources Tbk subsidiary, produced 8.2 million metric tons of sub-bituminous eco-coal at its Kintap mine in 2025. Arutmin's sub-bituminous eco-coal has very low sulfur and ash content and is used in domestic and overseas steam power plants. Arutmin's Asamasam site in South Kalimantan has capacity of up to 8 million metric tons of sub-bituminous coal annually, giving the operator another substantial site in this grade.
Bituminous and coking coal is forecast to be the fastest-growing segment, with a CAGR of 7.3% over 2027-2032. PT Alamtri Minerals Indonesia Tbk, an Alamtri Resources subsidiary, reported FY2025 total coal output of 7.41 million metric tons, up 12% from FY2024, mostly metallurgical with the remainder low-calorific coal. In 4Q2025, it completed the first 39-kilometer phase of a chip-seal hauling-road upgrade linked to its subsidiary PT Maruwai Coal's hard-coking-coal operations. Designed to support safe all-weather navigation, the upgrade addresses the link between mine output and dependable haulage. Because the upgrade is targeted to cover the entire hauling road surface, the 39-kilometer first phase leaves further work on Maruwai's haul route.
Complete Report Scope:
- By Coal Grade
- Lignite/Low-Rank
- Sub-bituminous
- Bituminous and Coking
- By Application
- Power Generation
- Iron, Steel, and Metallurgy
- Cement and Other Applications
List of Companies Covered in this Report:
- PT Bumi Resources Tbk
- PT Alamtri Resources Indonesia Tbk
- PT Bayan Resources Tbk
- PT Bukit Asam Tbk
- PT Indo Tambangraya Megah Tbk
- PT Kaltim Prima Coal
- PT Arutmin Indonesia
- PT Kideco Jaya Agung
- PT Berau Coal Energy Tbk
- PT Indika Energy Tbk
- Golden Energy & Resources Ltd
- BlackGold Natural Resources
- PT Bhakti Energi Persada
- Bayan International Pte Ltd
- PT Multi Harapan Utama
- Adani Indonesia (Adaro JV)
- Glencore (PT Balangan Coal)
- PT Petrosea Tbk
- PT BUMA Internasional Grup Tbk
- PT Resource Alam Indonesia Tbk
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Prolonged PLN-led baseload demand for low-CV thermal coal
- 4.2.2 Surge in coal-fired captive power for nickel & EV-battery smelters
- 4.2.3 China-plus-One strategy shifting seaborne demand to Indonesia
- 4.2.4 Government "Gasification & DME" incentives for low-rank coal
- 4.2.5 CCUS pilots unlocking high-CV export premiums
- 4.3 Market Restraints
- 4.3.1 Mandatory Domestic Market Obligation (DMO) price caps
- 4.3.2 Proposed accelerated coal-plant retirement under JETP funding
- 4.3.3 Provincial moratoria on new mining permits (Kalimantan, Sumatra)
- 4.3.4 Rising ESG-driven trade financing costs for Indonesian coal
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 PESTLE Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VOLUME)
- 5.1 By Coal Grade
- 5.1.1 Lignite/Low-Rank
- 5.1.2 Sub-bituminous
- 5.1.3 Bituminous and Coking
- 5.2 By Application
- 5.2.1 Power Generation
- 5.2.2 Iron, Steel, and Metallurgy
- 5.2.3 Cement and Other Applications
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 PT Bumi Resources Tbk
- 6.4.2 PT Alamtri Resources Indonesia Tbk
- 6.4.3 PT Bayan Resources Tbk
- 6.4.4 PT Bukit Asam Tbk
- 6.4.5 PT Indo Tambangraya Megah Tbk
- 6.4.6 PT Kaltim Prima Coal
- 6.4.7 PT Arutmin Indonesia
- 6.4.8 PT Kideco Jaya Agung
- 6.4.9 PT Berau Coal Energy Tbk
- 6.4.10 PT Indika Energy Tbk
- 6.4.11 Golden Energy & Resources Ltd
- 6.4.12 BlackGold Natural Resources
- 6.4.13 PT Bhakti Energi Persada
- 6.4.14 Bayan International Pte Ltd
- 6.4.15 PT Multi Harapan Utama
- 6.4.16 Adani Indonesia (Adaro JV)
- 6.4.17 Glencore (PT Balangan Coal)
- 6.4.18 PT Petrosea Tbk
- 6.4.19 PT BUMA Internasional Grup Tbk
- 6.4.20 PT Resource Alam Indonesia Tbk
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

