PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187661

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187661
United States IT Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the United States IT services market size was valued at USD 525.3 billion in 2026 and estimated to grow from USD 562.2 billion in 2027 to reach USD 801.5 billion by 2032, at a CAGR of 7.35% during the forecast period (2027-2032).
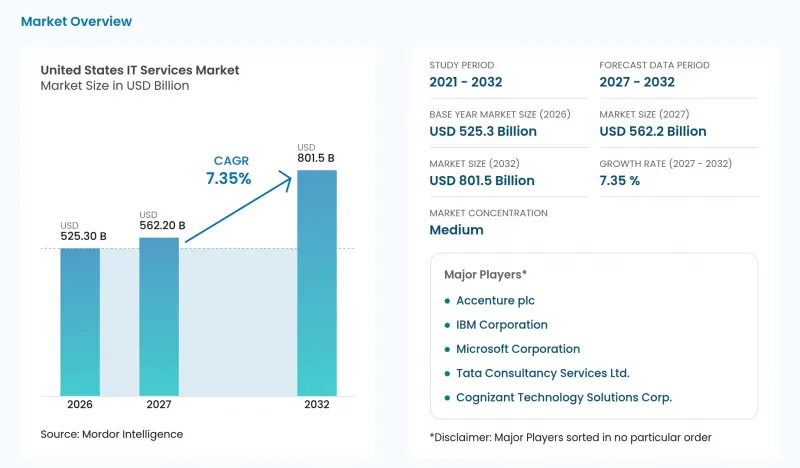
This report is segmented by Service Type (Managed Services and more), Deployment Model (Onshore Delivery and more), Engagement Model (Managed Services / Outcome-based and more), Organization Size (Large Enterprises and more), and End-User Industry (Banking, Financial Services and Insurance and more). The market forecasts are provided in terms of value (USD), based on availability.
United States IT Services Market Trends and Insights
Federal Incentives Accelerating Cloud Migration in US Public Sector
Federal modernization funding can turn cloud migration into a defined systems-replacement engagement for public-sector service providers. In September 2026, USDA began a Technology Modernization Fund-supported replacement of its legacy payroll system with a cloud-based platform, with a total TMF investment of USD 52.32 million. The replacement is intended to consolidate more than 50 applications into a shared environment meeting FedRAMP security requirements. That consolidation creates an integration task alongside the move to cloud infrastructure. Scoping delivery around the shared payroll environment rather than separate application moves favors providers able to combine consolidation with FedRAMP requirements.
Large-Scale Adoption of Generative AI among Fortune 1000
Moving AI into production changes the service requirement from demonstrating a model to sustaining a business workflow. In a 2025 survey of 125 Fortune 1000 and leading global organizations, 23.9% reported AI/generative AI in production at scale, up from 4.9% in 2024. Scaling deployment makes the connection between a model and its surrounding workflow commercially important. Connecting these systems to enterprise data creates demand for integration, testing and operational support. For service providers, the commercial opening extends beyond initial configuration because production workloads must deliver repeatable results. Linking implementation fees to ongoing workflow support gives providers a way to participate in production use after the initial deployment ends.
Scarcity of Senior Cloud and Security Talent
Senior cloud and security talent scarcity constrains the number of engagements a provider can deliver with adequate technical oversight. Cloud migrations and access-control deployments create design and review decisions that need responsibility to sit with experienced specialists. For a provider offering implementation and continuing support, committing those specialists to one engagement reduces the capacity available for another. That trade-off can turn a strong sales pipeline into a sequencing problem where customers need the same senior expertise at overlapping delivery stages. Even when junior staff can perform routine tasks, the remaining architecture and security decisions can keep delivery expensive or delay when work begins.
Other drivers and restraints analyzed in the detailed report include:
- 5G and Edge Roll-out Driving Network Integration Demand
- Zero-Trust Cybersecurity Mandates Boosting Security Services
- Margin Pressure from Outcome-Based Pricing Models
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Managed services accounted for a 27.71% share of the United States IT services market size in 2026. In June 2026, WidePoint announced its selection for DHS's Cellular Wireless Managed Services 3.0 procurement, with an approximately USD 3.1 billion ceiling. The Government Accountability Office later sustained a bid protest and recommended a new award decision. The procurement's scope shows how cellular wireless and mobility support across DHS components can be consolidated with one managed-services provider. Such consolidation concentrates a department-wide service opportunity in a single award, so reopening supplier selection can delay access to the entire program rather than one component's work.
Cybersecurity services are forecast to be the fastest-growing segment, at an 8.72% CAGR during 2027-2032. In December 2025, NASPO ValuePoint announced Idaho's cybersecurity and information security master-agreement awards to 11 suppliers, covering assessment, incident response and related services. Agreements took effect November 1, 2025, or on execution, with use by eligible public entities subject to state procurement approval and local law. The award structure gives eligible buyers a choice among multiple providers within a specified procurement channel. State procurement approval and local law make access to public cybersecurity orders conditional, so an awarded supplier's usable customer base can be narrower than the cooperative's eligible population.
Onshore delivery represented a 54.53% United States IT services market share in 2026, making it the largest segment. CGI operates onshore delivery centers across 6 states, including Alabama, Louisiana, Texas, Tennessee, Virginia and Wisconsin. A multi-state footprint can give a provider room to distribute delivery within the United States. Drawing on several state labor markets can reduce dependence on any single local recruiting pool. For a buyer keeping work onshore, that broader sourcing base is useful only if handoffs between centers preserve continuity.
Nearshore delivery is forecast to be the fastest-growing segment, at a 9.17% CAGR during 2027-2032. During fiscal 2026, Aeries Technology further scaled its Mexico delivery presence for North American clients using nearshore-offshore operating models. That example places nearshore work within a broader delivery structure, making the assignment of functions across locations part of the service proposition. Offshore delivery also serves US buyers, as TTEC's Q2 2026 filing described customer-experience centers across 13 countries serving US and other clients. Aeries's Mexico expansion can support additional assignments inside blended engagements, allowing nearshore providers to pursue a larger delivery role without requiring buyers to replace an entire offshore arrangement.
Complete Report Scope:
- By Service Type
- IT Consulting and Implementation
- Application Development and Maintenance (ADM)
- Infrastructure Services
- Managed Services
- IT Outsourcing (ITO)
- Business Process Outsourcing (BPO)
- Cloud and Platform Services
- Cybersecurity Services
- Digital Transformation and Emerging Tech (AI, IoT, Blockchain)
- By Deployment Model
- Onshore Delivery
- Nearshore Delivery
- Offshore Delivery
- By Engagement Model
- Project-based / Fixed Price
- Staff Augmentation / Time-and-Material
- Managed Services / Outcome-based
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By End-User Industry
- Banking, Financial Services and Insurance (BFSI)
- Manufacturing
- Government and Public Sector
- Healthcare and Life Sciences
- Retail and Consumer Goods
- Telecom and Media
- Transportation and Logistics
- Energy and Utilities
- Other End-User Industries
List of Companies Covered in this Report:
- Accenture plc
- IBM Corporation
- Cognizant Technology Solutions Corp.
- Tata Consultancy Services Ltd.
- Microsoft Corporation
- Infosys Ltd.
- Wipro Ltd.
- Deloitte Consulting LLP
- Capgemini SE
- HCL Technologies Ltd.
- CGI Inc.
- DXC Technology Co.
- Booz Allen Hamilton Inc.
- Leidos Holdings Inc.
- Slalom Inc.
- EPAM Systems Inc.
- NTT DATA Services
- Kyndryl Holdings Inc.
- LTM Ltd.
- Tech Mahindra Ltd.
- Perficient Inc.
- Thoughtworks Inc.
- Persistent Systems Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Federal Incentives Accelerating Cloud Migration in US Public Sector
- 4.2.2 Large-Scale Adoption of Generative AI among Fortune 1000
- 4.2.3 5G and Edge Roll-out Driving Network Integration Demand
- 4.2.4 Zero-Trust Cybersecurity Mandates Boosting Security Services
- 4.2.5 Healthcare Interoperability Rules Fueling EHR Integration Services
- 4.2.6 PE-Backed ERP Modernization Wave in Mid-Market Firms
- 4.3 Market Restraints
- 4.3.1 Scarcity of Senior Cloud and Security Talent
- 4.3.2 Margin Pressure from Outcome-Based Pricing Models
- 4.3.3 Compliance Complexity under CCPA/CPRA Litigation
- 4.3.4 Offshore Wage Inflation Eroding Cost Advantages
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
- 4.9 Comparative Insights - Tier 1 vs Tier 2 Vendors
- 4.10 In-housing vs Outsourcing Analysis
- 4.11 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 IT Consulting and Implementation
- 5.1.2 Application Development and Maintenance (ADM)
- 5.1.3 Infrastructure Services
- 5.1.4 Managed Services
- 5.1.5 IT Outsourcing (ITO)
- 5.1.6 Business Process Outsourcing (BPO)
- 5.1.7 Cloud and Platform Services
- 5.1.8 Cybersecurity Services
- 5.1.9 Digital Transformation and Emerging Tech (AI, IoT, Blockchain)
- 5.2 By Deployment Model
- 5.2.1 Onshore Delivery
- 5.2.2 Nearshore Delivery
- 5.2.3 Offshore Delivery
- 5.3 By Engagement Model
- 5.3.1 Project-based / Fixed Price
- 5.3.2 Staff Augmentation / Time-and-Material
- 5.3.3 Managed Services / Outcome-based
- 5.4 By Organization Size
- 5.4.1 Large Enterprises
- 5.4.2 Small and Medium Enterprises (SMEs)
- 5.5 By End-User Industry
- 5.5.1 Banking, Financial Services and Insurance (BFSI)
- 5.5.2 Manufacturing
- 5.5.3 Government and Public Sector
- 5.5.4 Healthcare and Life Sciences
- 5.5.5 Retail and Consumer Goods
- 5.5.6 Telecom and Media
- 5.5.7 Transportation and Logistics
- 5.5.8 Energy and Utilities
- 5.5.9 Other End-User Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Accenture plc
- 6.4.2 IBM Corporation
- 6.4.3 Cognizant Technology Solutions Corp.
- 6.4.4 Tata Consultancy Services Ltd.
- 6.4.5 Microsoft Corporation
- 6.4.6 Infosys Ltd.
- 6.4.7 Wipro Ltd.
- 6.4.8 Deloitte Consulting LLP
- 6.4.9 Capgemini SE
- 6.4.10 HCL Technologies Ltd.
- 6.4.11 CGI Inc.
- 6.4.12 DXC Technology Co.
- 6.4.13 Booz Allen Hamilton Inc.
- 6.4.14 Leidos Holdings Inc.
- 6.4.15 Slalom Inc.
- 6.4.16 EPAM Systems Inc.
- 6.4.17 NTT DATA Services
- 6.4.18 Kyndryl Holdings Inc.
- 6.4.19 LTM Ltd.
- 6.4.20 Tech Mahindra Ltd.
- 6.4.21 Perficient Inc.
- 6.4.22 Thoughtworks Inc.
- 6.4.23 Persistent Systems Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

