PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187677

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187677
India Road Freight Transport - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
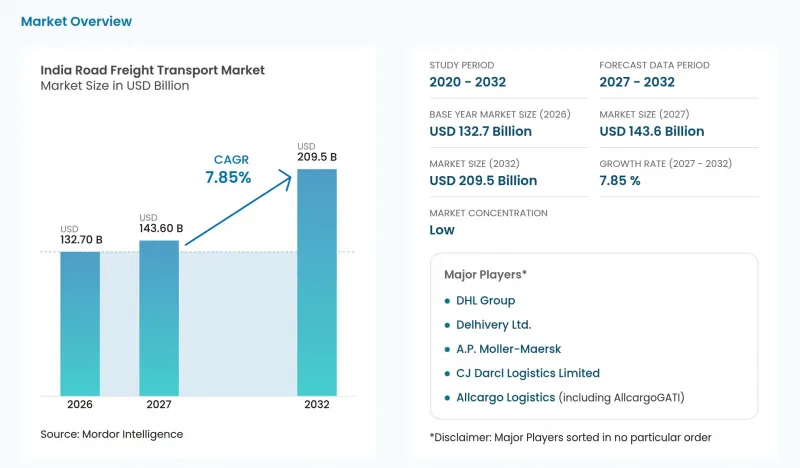
According to Mordor Intelligence, the India road freight transport market size is expected to increase from USD 132.7 billion in 2026 to USD 143.6 billion in 2027 and reach USD 209.5 billion by 2032, growing at a CAGR of 7.85% over 2027-2032.
This report is segmented by End User Industry (Wholesale and Retail Trade and more), Destination (Domestic and more), Truckload Specification (Full-Truck-Load and more), Containerization (Non-Containerized and more), Distance (Long Haul and more), Goods Configuration, and Temperature Control. The market forecasts are provided in terms of value (USD), based on availability.
India Road Freight Transport Market Trends and Insights
Manufacturing Push Under Make in India Initiative
India's manufacturing gross value added at constant prices grew 10.7% in 2025-26, a provisional estimate under the revised series with a 2022-23 base. Expanding real manufacturing activity strengthens the demand case for carriers serving the movement of production inputs and finished goods. A plant raising physical output needs inbound materials and outbound finished-goods movements, creating potential loaded trips on both sides of production. Coordinating those movements where routes align gives a carrier a way to reduce empty repositioning between factory assignments. Additional production can then raise demand for vehicle capacity on established factory lanes, even before manufacturers add new destinations.
Rising FMCG Distribution into Rural & Semi-Urban Markets
Reaching additional consumer outlets creates a freight opportunity whose value depends on distribution coverage as well as shipment size. Hindustan Unilever added approximately 200,000 stores to its total reach during FY 2025-26 while expanding coverage into rural hinterlands. For carriers serving this expansion, the freight requirement extends across a wider delivery footprint as brands reach additional retail outlets. Combining compatible deliveries can make dispersed outlets commercially serviceable without requiring each destination to generate a full truckload. Each added store is a separate delivery point, so the expansion increases the drops to schedule and makes the number combined within a circuit commercially consequential.
Chronic Driver Shortage Across Long-Haul Routes
Driver availability can constrain a freight operation even when cargo and vehicles are ready for dispatch. A 2025 International Transport Workers' Federation study, including April 2024 interviews, reported that unattractive working conditions in India's trucking industry were resulting in driver shortages. In May 2026, a container freight station trailer-driver shortage delayed evacuation of 25,000 import containers at Jawaharlal Nehru Port, India's Ministry of Ports, Shipping and Waterways reported. The commercial consequence is a mismatch between cargo-handling capacity and the workforce needed to release freight into the road network. In February 2026, Allcargo Group launched heavy motor vehicle driver training for women holding light motor vehicle licenses in India's port logistics corridor. Where drivers cannot be assigned to required movements, additional vehicle capacity alone cannot remove the dispatch bottleneck or its associated cargo delay.
Other drivers and restraints analyzed in the detailed report include:
- Growth in Construction & Infrastructure Material Movement
- Warehousing Expansion Across Tier-2 and Tier-3 Cities
- Highly Fragmented Small Fleet Operator Base
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Wholesale and retail trade accounted for a 30.44% share of the India road freight transport market size in 2026. Delhivery's Express Parcel business delivered 1 billion e-commerce parcels in FY 2025-26. That retail-related operating scale provides a substantial stream of individual consignments for transport networks to aggregate into road movements. For the largest segment, the commercial task is to convert numerous separate orders into coordinated capacity without treating every destination as a dedicated truck assignment. A large parcel base supports shared road departures, but committing more trucks becomes worthwhile only when orders combine into viable loads on particular lanes.
Manufacturing is the fastest-growing segment, with a forecast CAGR of 9.95% over 2027-2032. CG Semi began commercial production at its G1 semiconductor assembly, packaging and test facility in Sanand in July 2026. The facility has peak capacity of 300 million units per year, and CG Power and Industrial Solutions is the venture's majority partner. India's manufacturing industrial production grew 9% year over year in August 2026, according to the Ministry of Statistics and Programme Implementation's quick estimate. Output growth increases the inputs and finished goods requiring transport, creating a larger potential haulage task for carriers serving factory dispatches.
Domestic transport represented a 62.82% India road freight transport market share in 2026. VRL Logistics reported more than 1 million customers across India in FY 2025-26, based on GST identification numbers in its system, and stated that all its business operations were in India. Its customers included corporate businesses, clearing and forwarding agents, wholesalers and retailers. With customers ranging from corporate businesses to wholesalers and retailers, a domestic carrier's volume can depend on serving many shippers on shared lanes rather than on any single account.
International transport is the fastest-growing segment, with a forecast CAGR of 8.85% over 2027-2032. Petrapole Land Port recorded 111,210 cargo movements in FY 2025-26 at the India-Bangladesh border. That operating base places part of the international freight opportunity at land crossings, where the road movement and its border interface form a connected service. Carriers can organize capacity around these established cross-border flows, with commercial performance depending on the continuity of cargo handoffs across the journey. If a border handoff stalls, the assigned truck remains committed beyond the domestic leg, increasing the capacity tied up in each international delivery.
Full-truck-load (FTL) was the largest segment, accounting for 79.84% of road freight service value in 2026. In Safe & Secure Logistics' Indian booking register, FTL represented 24% of consignments but 85.3% of charged tonnage from August 2025 to March 2026. The format can therefore carry substantial freight weight without accounting for the same number of individual orders. For shippers with enough cargo to use a complete vehicle, the service packages capacity around a consignment rather than a shared departure. The buyer commits to a vehicle movement for its load, so the operator earns from deploying truck capacity to that consignment.
Less than-truck-load (LTL) is the fastest-growing segment, with a forecast CAGR of 9.85% over 2027-2032. Delhivery's part-truck-load (PTL) freight tonnage reached 542,000 metric tons in the first quarter of FY 2026-27, up 18.4% from the first quarter of FY 2025-26. Shared capacity gives smaller consignments access to line-haul transport without a shipper needing to fill an entire truck. That model makes aggregation at departure points central to the business because individual orders have to form a viable combined movement. As PTL tonnage increases, fuller departures spread movement costs across more freight, while additional departures create a different requirement for vehicles and terminal capacity.
Complete Report Scope:
- By End User Industry
- Agriculture, Fishing, and Forestry
- Construction
- Manufacturing
- Oil and Gas, Mining and Quarrying
- Wholesale and Retail Trade
- Others
- By Destination
- Domestic
- International
- By Truckload Specification
- Full-Truck-Load (FTL)
- Less than-Truck-Load (LTL)
- By Containerization
- Containerized
- Non-Containerized
- By Distance
- Long Haul
- Short Haul
- By Goods Configuration
- Fluid Goods
- Solid Goods
- By Temperature Control
- Non-Temperature Controlled
- Temperature Controlled
List of Companies Covered in this Report:
- A.P. Moller-Maersk
- Allcargo Logistics (including AllcargoGATI)
- CJ Darcl Logistics Limited
- Delhivery Ltd.
- DHL Group
- Expeditors International of Washington, Inc.
- GEODIS
- Mahindra Logistics
- Nippon Express Holdings
- Transport Corporation of India (TCI)
- V-Trans
- Varuna Group
- VRL Logistics Ltd.
- Safexpress
- Shree Tirupati Logistics
- Xpressbees
- Om Logistics Supply Chain
- CKB Group
- Glottis
- SAR Logistics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Manufacturing Push Under Make in India Initiative
- 4.2.2 Rising FMCG Distribution into Rural & Semi-Urban Markets
- 4.2.3 Growth in Construction & Infrastructure Material Movement
- 4.2.4 Warehousing Expansion Across Tier-2 and Tier-3 Cities
- 4.2.5 Dedicated Freight Corridors Supporting Multimodal Integration
- 4.2.6 Growth of Quick Commerce & Hyperlocal Delivery Models
- 4.3 Market Restraints
- 4.3.1 Chronic Driver Shortage Across Long-Haul Routes
- 4.3.2 Highly Fragmented Small Fleet Operator Base
- 4.3.3 Diesel Price Volatility Impacting Margins
- 4.3.4 Urban Congestion & First/Last-Mile Inefficiencies
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By End User Industry
- 5.1.1 Agriculture, Fishing, and Forestry
- 5.1.2 Construction
- 5.1.3 Manufacturing
- 5.1.4 Oil and Gas, Mining and Quarrying
- 5.1.5 Wholesale and Retail Trade
- 5.1.6 Others
- 5.2 By Destination
- 5.2.1 Domestic
- 5.2.2 International
- 5.3 By Truckload Specification
- 5.3.1 Full-Truck-Load (FTL)
- 5.3.2 Less than-Truck-Load (LTL)
- 5.4 By Containerization
- 5.4.1 Containerized
- 5.4.2 Non-Containerized
- 5.5 By Distance
- 5.5.1 Long Haul
- 5.5.2 Short Haul
- 5.6 By Goods Configuration
- 5.6.1 Fluid Goods
- 5.6.2 Solid Goods
- 5.7 By Temperature Control
- 5.7.1 Non-Temperature Controlled
- 5.7.2 Temperature Controlled
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 A.P. Moller-Maersk
- 6.4.2 Allcargo Logistics (including AllcargoGATI)
- 6.4.3 CJ Darcl Logistics Limited
- 6.4.4 Delhivery Ltd.
- 6.4.5 DHL Group
- 6.4.6 Expeditors International of Washington, Inc.
- 6.4.7 GEODIS
- 6.4.8 Mahindra Logistics
- 6.4.9 Nippon Express Holdings
- 6.4.10 Transport Corporation of India (TCI)
- 6.4.11 V-Trans
- 6.4.12 Varuna Group
- 6.4.13 VRL Logistics Ltd.
- 6.4.14 Safexpress
- 6.4.15 Shree Tirupati Logistics
- 6.4.16 Xpressbees
- 6.4.17 Om Logistics Supply Chain
- 6.4.18 CKB Group
- 6.4.19 Glottis
- 6.4.20 SAR Logistics
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

