PUBLISHER: Roots Analysis | PRODUCT CODE: 2132676

PUBLISHER: Roots Analysis | PRODUCT CODE: 2132676
France Radiopharmaceuticals and Theranostics Market by Type of Radioisotope, Type of Product, Application, End User and Distribution Channel - Trends and Forecast, Till 2035
FRANCE RADIOPHARMACEUTICALS AND THERANOSTICS MARKET: OVERVIEW
The France radiopharmaceuticals and theranostics market is estimated at USD 447 million in the current year and is projected to reach USD 1,032.8 million by 2035, registering a CAGR of approximately 9.8% across the forecast period.
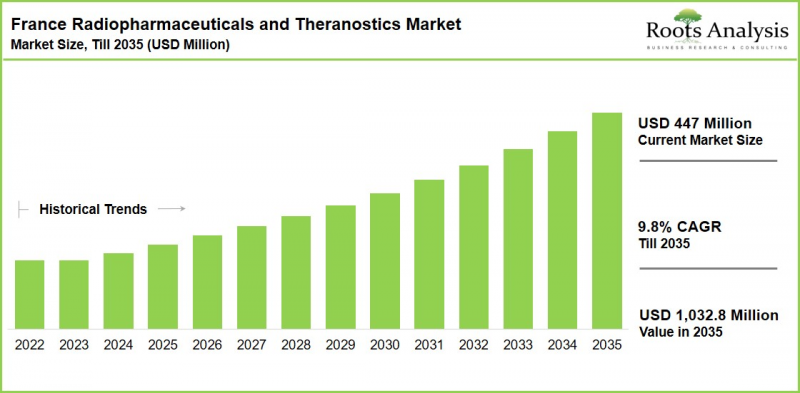
France Radiopharmaceuticals and Theranostics Market: Growth and Trends
Radiopharmaceuticals and theranostic agents' pair molecular imaging with targeted radionuclide therapy. These agents allow clinicians to diagnose, select and monitor cancer treatment on a single biological pathway. France has emerged as one of Europe's leading radiopharmaceuticals and theranostics markets, supported by a dense hospital-based nuclear medicine network, strong academic radiochemistry research, and manufacturing capacity built around the legacy of the French Atomic Energy Commission (CEA).
Domestic and multinational manufacturers are scaling French production capacity to meet growing regional demand for radioligand therapy. Curium is investing over €32 million in a new lutetium-177 PSMA-I&T production line at its historic Saclay site, adding to more than €50 million deployed across its 13 French production sites over the past five years. In addition, Orano Med is constructing a €250 million Advanced Thorium Extraction Facility (ATEF) in Bessines-sur-Gartempe to secure lead-212 supply for targeted alpha therapy, alongside a dedicated ATLab under construction in Onnaing near Valenciennes for commercial-scale 212Pb radioligand production. These moves position France as a key hub in Europe's theranostics supply chain, with growing implications for distributors, cold-chain logistics providers, and hospital-facing partners.
Growth Drivers: Factors Fueling Market Expansion
Growth in the France radiopharmaceuticals and theranostics market is being driven by the rising incidence of prostate cancer and neuroendocrine tumors, both of which are increasingly managed using PSMA and somatostatin receptor-targeted theranostic pairs.
Expanding reimbursement pathways for radioligand therapies, combined with France's structured regulatory framework administered by the Agence Nationale de Securite du Medicament (ANSM) and the Autorite de Surete Nucleaire (ASN), are creating predictable market-entry conditions for novel radiopharmaceuticals.
Continued investment in domestic isotope production, including lutetium-177, gallium-68 and lead-212, is reducing France's historical reliance on imported radioisotopes and shortening the short half-life supply chain that constrains this category. Additionally, the growing installed base of PET / SPECT imaging systems across French university hospitals and private diagnostic centers is expanding the addressable patient population for both diagnostic and therapeutic radiopharmaceuticals.
Market Challenges: Critical Barriers Hindering Progress
Despite strong momentum, the France radiopharmaceuticals and theranostics market faces structural challenges that may impede the market growth. Short radioisotope half-lives require fast, temperature-controlled distribution from production sites to hospital nuclear medicine units, leaving little room for logistical delays.
Capital intensity and specialized radiation-handling infrastructure raise barriers for smaller distributors seeking to enter the therapeutic radiopharmaceutical segment. Reimbursement and pricing negotiations in France can delay market access for newly approved theranostic agents.
Reliance on a few reactor and cyclotron-based isotope producers creates supply-chain risks during planned or unexpected outages.
France Radiopharmaceuticals and Theranostics Market: Key Insights
The report examines the current state of the France radiopharmaceuticals and theranostics market and identifies actionable opportunities for distributors, channel intermediaries and hospital-facing logistics partners. Some key findings include:
- Domestic isotope production build-out, led by Curium's Saclay expansion and Orano Med's Bessines-sur-Gartempe and Onnaing facilities, is shifting France from an import-dependent to a production-anchored market, creating new regional distribution and cold-chain contracting opportunities.
- The forecast shift toward therapeutic radioligand therapies as the fastest-growing product category is opening a distinct channel opportunity for distributors that can support time-critical, radiation-compliant last-mile delivery to hospital nuclear medicine departments.
- Prostate cancer-focused PSMA theranostics and neuroendocrine tumor-focused somatostatin receptor agents together account for the majority of near-term commercial demand, giving distributors with oncology-center relationships a clear entry point.
- Regulatory oversight split between ANSM (medicinal product approval) and ASN (radiation safety and handling) creates a compliance-intensive entry pathway; distributors that can navigate both frameworks hold a differentiation advantage over generalist pharmaceutical logistics providers.
- Capacity concentration in the Ile-de-France region around the CEA-Saclay ecosystem is increasing demand for regional distribution partners capable of extending time-sensitive delivery into secondary hospital markets outside Paris.
- Continued capital deployment by originator-scale players, including Curium and Orano Med, alongside European Investment Bank-backed financing, is raising barriers to entry for smaller developers while creating outsourcing openings for specialized third-party logistics and distribution partners.
- Growing use of gallium-68 and fluorine-18 diagnostic tracers alongside therapeutic radioisotopes is pushing distributors toward dual diagnostic-therapeutic (theranostic) portfolios rather than single-modality product lines.
Recent Deal Activity Signalling Investor Momentum
- Capacity Expansion: Curium's €32 million investment in a new lutetium-177 PSMA-I&T production line at its Saclay facility, part of over €50 million deployed across its 13 French sites over five years.
- Industrial Infrastructure: Orano Med's €250 million Advanced Thorium Extraction Facility (ATEF) in Bessines-sur-Gartempe, designed to boost lead-212 precursor output roughly tenfold and expected onstream in 2027.
- Financing Momentum: A €125 million European Investment Bank credit line to Orano Med to accelerate targeted alpha therapy manufacturing and industrial platform development in France.
- Manufacturing Build-Out: Construction of Orano Med's ATLab in Onnaing, near Valenciennes, to begin commercial-scale lead-212 radioligand production and European distribution from 2026.
France Radiopharmaceuticals and Theranostics Market Segments
The market sizing and opportunity analysis has been segmented across the following parameters:
By Type of Product
- Diagnostic Radiopharmaceuticals
- Therapeutic Radiopharmaceuticals (Radioligand Therapy)
By Type of Radioisotope
- Lutetium-177 (177Lu)
- Gallium-68 (68Ga)
- Fluorine-18 (18F)
- Iodine-131 (131I)
- Yttrium-90 (9°Y)
- Actinium-225 / Lead-212 (Targeted Alpha Therapy Isotopes)
- Other Radioisotopes
By Application
- Oncology
- Prostate Cancer
- Neuroendocrine Tumors
- Others
- Cardiology
- Neurology
- Other Applications
By End User
- Hospitals and University Medical Centers
- Private Diagnostic Imaging Centers
- Academic and Research Institutes
By Distribution Channel
- Direct-to-Hospital Supply
- Third-Party Distributors and Radiopharmacy Networks
France Radiopharmaceuticals and Theranostics Market: Key Segments
Diagnostic Radiopharmaceuticals Lead, Therapeutic Segment to Register Higher CAGR
Diagnostic radiopharmaceuticals currently account for the largest share of the France radiopharmaceuticals and theranostics market. This highest share is supported by the broad, established use of fluorine-18 and gallium-68 tracers across routine PET oncology imaging. Looking ahead, therapeutic radiopharmaceuticals are projected to register the higher CAGR through 2035. This lucrative growth is driven by expanding clinical and reimbursement pathways for lutetium-177 and lead-212 based radioligand therapies in prostate cancer and neuroendocrine tumors.
Oncology Applications Dominate the Market
Oncology applications hold the highest share of the France radiopharmaceuticals and theranostics market. This highest share reflects the key role of theranostic pairs in prostate cancer and neuroendocrine tumor management. Cardiology applications are expected to grow at a comparatively higher CAGR. This unprecedented growth is driven by increasing use of myocardial perfusion imaging agents in an aging population with rising cardiovascular disease burden.
Hospitals and University Medical Centers Hold the Highest Share
Hospitals and university medical centers hold the highest end-user share. This dominance is owing to their integrated nuclear medicine departments, radiation-handling infrastructure and direct access to oncology referral pathways. Private diagnostic imaging centers are expected to expand at a higher CAGR during the forecast period. This unprecedented growth is driven by the growing decentralized PET/SPECT capacity outside major academic hubs which is widening the addressable base for third-party distributors.
Example Players in France Radiopharmaceuticals and Theranostics Market
- Advanced Accelerator Applications (Novartis)
- CIS bio international
- Curium
- Cardinal Health
- Eckert & Ziegler
- Guerbet
- Ion Beam Applications (IBA)
- ITM Isotope Technologies Munich
- Orano Med
- SOFIE
- Telix Pharmaceuticals
- Zionexa
FRANCE RADIOPHARMACEUTICALS AND THERANOSTICS MARKET: RESEARCH COVERAGE
- Market Sizing and Opportunity Analysis: An in-depth analysis of the France radiopharmaceuticals and theranostics market across product type, radioisotope, application, end user and distribution channel.
- Manufacturer Landscape: A detailed assessment of companies producing and distributing radiopharmaceuticals in France, based on year of establishment, production footprint and portfolio breadth.
- Company Profiles: In-depth profiles of prominent players engaged in the development, production and commercialization of radiopharmaceuticals and theranostics in France.
- Big Pharma Initiatives: An analysis of big pharma initiatives related to radiopharmaceuticals and theranostics in France, based on several relevant parameters, such as year of initiative, type of initiative, type of partnership, type of expansion, radioisotope, application and company, along with a benchmarking assessment of major big pharma players based on their respective initiatives.
- Start-Up Ecosystem Analysis: An analysis of start-ups focused on radiopharmaceuticals and theranostics in France, based on several relevant parameters, such as headquarters location, company strength, pipeline maturity, pipeline strength, financial support, investor strength and partnership activity, along with a benchmarking assessment and comprehensive start-up health indexing analysis.
- Clinical Trial Analysis: An analysis of clinical trials related to radiopharmaceuticals and theranostics in France, based on several relevant parameters, such as trial registration year, patient enrollment, trial phase, trial status, study design, sponsor / collaborator type, product type, radioisotope, application, therapeutic area and geography, including France-based trials and European trials involving French clinical centers.
- Partnerships and Collaborations Analysis: A comprehensive assessment of partnership activity among radiopharmaceutical developers, distributors and hospital networks in France.
- Market Impact Analysis: The report analyzes drivers, restraints, opportunities and challenges shaping market growth, including the impact of isotope supply concentration on distribution planning.
Key Questions Answered in this Report
- How large is the France radiopharmaceuticals and theranostics market today, and how large will it be by 2035?
- Which product types, radioisotopes and applications are gaining or losing share?
- Which companies are best positioned across the diagnostic and therapeutic segments, and how deep is their production pipeline?
- How will the shift toward therapeutic radioligand therapy reshape distribution and cold-chain logistics economics?
- Which regions and end-user segments offer the strongest near-term revenue and long-term growth combination?
- What is the realistic impact of isotope supply concentration on distributor risk and inventory planning?
Reasons to Buy this Report
This report is designed to give distributors, channel partners, and investors a decisive analytical edge in a fast-consolidating market. Its core differentiators include:
- Granular Market Forecasting: Access detailed market forecasts across radioisotopes, emitters, diagnostic and therapeutic applications, production methods, end users and regions to identify high-growth opportunities.
- Competitive & Strategic Intelligence: A detailed analysis of leading radiopharmaceutical companies, recent investments, partnerships, pipeline developments and production expansion initiatives to support competitive positioning and strategic planning.
- Supply & Production Landscape: Evaluate production methods, isotope availability and capacity expansion trends to understand emerging supply-side opportunities and potential market constraints.
- Regional Opportunity Assessment: Compare market attractiveness across North America, Europe, Asia-Pacific, MENA and Latin America to identify priority markets for expansion and investment.
- Primary Research-Backed Insights: Detailed triangulated data analysis with product approvals, pipeline progress, sales trends, regional access conditions and industry stakeholder interviews.
- Ready-to-Use Business Intelligence: Receive complementary Excel data packs covering market landscape, partnerships and collaborations, clinical trials, and market size and opportunity analysis, alongside a PowerPoint summary.
Additional Benefits
- Complementary PPT Insights Pack
- Complementary Excel Data Packs for all Analytical Modules in the Report
- 15% Free Content Customization
- Detailed Report Walkthrough Session with Research Team
- Free Updated report if the report is 6-12 months old or older
TABLE OF CONTENTS
1. PREFACE
- 1.1. Introduction
- 1.2. Market Share Insights
- 1.3. Key Market Insights
- 1.4. Report Coverage
- 1.5. Key Questions Answered
- 1.6. Chapter Outlines
2. RESEARCH METHODOLOGY
- 2.1. Chapter Overview
- 2.2. Research Assumptions
- 2.2.1. Market Landscape and Market Trends
- 2.2.2. Market Forecast and Opportunity Analysis
- 2.2.3. Comparative Analysis
- 2.3. Database Building
- 2.3.1. Data Collection
- 2.3.2. Data Validation
- 2.3.3. Data Analysis
- 2.4. Project Methodology
- 2.4.1. Secondary Research
- 2.4.1.1. Annual Reports
- 2.4.1.2. Academic Research Papers
- 2.4.1.3. Company Websites
- 2.4.1.4. Investor Presentations
- 2.4.1.5. Regulatory Filings
- 2.4.1.6. White Papers
- 2.4.1.7. Industry Publications
- 2.4.1.8. Conferences and Seminars
- 2.4.1.9. Government and Regulatory Portals
- 2.4.1.10. Media and Press Releases
- 2.4.1.11. Clinical Trial Registries
- 2.4.1.12. Industry Databases
- 2.4.1.13. Roots Proprietary Databases
- 2.4.1.14. Paid Databases and Sources
- 2.4.1.15. Social Media Portals
- 2.4.1.16. Other Secondary Sources
- 2.4.2. Primary Research
- 2.4.2.1. Types of Primary Research
- 2.4.2.1.1. Qualitative Research
- 2.4.2.1.2. Quantitative Research
- 2.4.2.1.3. Hybrid Approach
- 2.4.2.2. Advantages of Primary Research
- 2.4.2.3. Techniques for Primary Research
- 2.4.2.3.1. Interviews
- 2.4.2.3.2. Surveys
- 2.4.2.3.3. Focus Groups
- 2.4.2.3.4. Observational Research
- 2.4.2.3.5. Social Media Interactions
- 2.4.2.4. Key Opinion Leaders Considered in Primary Research
- 2.4.2.4.1. Company Executives
- 2.4.2.4.2. Research and Development Heads
- 2.4.2.4.3. Technical Experts
- 2.4.2.4.4. Subject Matter Experts
- 2.4.2.4.5. Scientists
- 2.4.2.4.6. Physicians and Healthcare Providers
- 2.4.2.5. Ethics and Integrity
- 2.4.2.5.1. Research Ethics
- 2.4.2.5.2. Data Integrity
- 2.4.2.1. Types of Primary Research
- 2.4.3. Analytical Tools and Databases
- 2.4.1. Secondary Research
- 2.5. Robust Quality Control
3. MARKET DYNAMICS
- 3.1. Chapter Overview
- 3.2. Forecast Methodology
- 3.2.1. Top-down Approach
- 3.2.2. Bottom-up Approach
- 3.2.3. Hybrid Approach
- 3.3. Market Assessment Framework
- 3.3.1. Total Addressable Market
- 3.3.2. Serviceable Addressable Market
- 3.3.3. Serviceable Obtainable Market
- 3.3.4. Currently Acquired Market
- 3.4. Forecasting Tools and Techniques
- 3.4.1. Qualitative Forecasting
- 3.4.2. Correlation
- 3.4.3. Regression
- 3.4.4. Extrapolation
- 3.4.5. Convergence
- 3.4.6. Sensitivity Analysis
- 3.4.7. Scenario Planning
- 3.4.8. Data Visualization
- 3.4.9. Time Series Analysis
- 3.4.10. Forecast Error Analysis
- 3.5. Key Considerations
- 3.5.1. Disease Epidemiology
- 3.5.2. Radiopharmaceutical Production Capacity
- 3.5.3. Radioisotope Availability
- 3.5.4. Regulatory Environment
- 3.5.5. Reimbursement and Pricing
- 3.5.6. Nuclear Medicine Infrastructure
- 3.5.7. Hospital and Imaging Center Capacity
- 3.5.8. Radioisotope Supply Chain
- 3.5.9. Radiopharmacy Infrastructure
- 3.6. Limitations
4. MACRO-ECONOMIC INDICATORS
- 4.1. Chapter Overview
- 4.2. Market Dynamics
- 4.2.1. Time Period
- 4.2.1.1. Historical Trends
- 4.2.1.2. Current and Forecasted Estimates
- 4.2.2. Currency Coverage
- 4.2.2.1. Major Currencies Affecting the Market
- 4.2.2.2. Factors Affecting Currency Fluctuations
- 4.2.2.3. Impact of Currency Fluctuations on the Market
- 4.2.3. Foreign Currency Exchange Rate
- 4.2.3.1. Impact of Foreign Exchange Rate Volatility
- 4.2.3.2. Strategies for Mitigating Foreign Exchange Risk
- 4.2.4. Recession
- 4.2.4.1. Assessment of Current Economic Conditions
- 4.2.4.2. Historical Analysis of Past Recessions
- 4.2.5. Inflation
- 4.2.5.1. Measurement and Analysis of Inflationary Pressures
- 4.2.5.2. Potential Impact on Market Evolution
- 4.2.6. Interest Rates
- 4.2.6.1. Interest Rates and Their Impact on the Market
- 4.2.6.2. Strategies for Managing Interest Rate Risk
- 4.2.7. Healthcare Expenditure
- 4.2.8. Nuclear Medicine Infrastructure Investment
- 4.2.9. Pharmaceutical and Life Sciences Investment
- 4.2.10. Other Macroeconomic Indicators
- 4.2.10.1. Gross Domestic Product
- 4.2.10.2. Employment
- 4.2.10.3. Government Spending
- 4.2.10.4. Taxes
- 4.2.1. Time Period
- 4.3. Conclusion
5. EXECUTIVE SUMMARY
6. INTRODUCTION
- 6.1. Chapter Overview
- 6.2. Radiopharmaceuticals
- 6.2.1. Definition and Classification
- 6.2.2. Components of Radiopharmaceuticals
- 6.2.3. Diagnostic Radiopharmaceuticals
- 6.2.4. Therapeutic Radiopharmaceuticals
- 6.3. Theranostics
- 6.3.1. Concept of Theranostics
- 6.3.2. Diagnostic-Therapeutic Pairing
- 6.3.3. Patient Selection and Companion Imaging
- 6.4. Radioisotopes
- 6.4.1. Lutetium-177
- 6.4.2. Gallium-68
- 6.4.3. Fluorine-18
- 6.4.4. Iodine-131
- 6.4.5. Yttrium-90
- 6.4.6. Actinium-225 and Lead-212
- 6.4.7. Other Radioisotopes
- 6.5. Radiopharmaceutical Manufacturing and Supply Chain
- 6.6. Radiopharmaceutical Distribution
- 6.7. Applications of Radiopharmaceuticals
- 6.7.1. Oncology
- 6.7.2. Cardiology
- 6.7.3. Neurology
- 6.7.4. Other Applications
- 6.8. Key Advantages and Limitations
- 6.9. Future Perspectives
7. MARKET LANDSCAPE
- 7.1. Chapter Overview
- 7.2. France Radiopharmaceuticals and Theranostics: Overall Market Landscape
- 7.2.1. Analysis by Product Type
- 7.2.2. Analysis by Type of Radioisotope
- 7.2.3. Analysis by Application
- 7.2.4. Analysis by End User
- 7.2.5. Analysis by Distribution Channel
- 7.2.6. Analysis by Region
- 7.3. Radiopharmaceutical Developer and Manufacturer Landscape
- 7.3.1. Analysis by Company Type
- 7.3.2. Analysis by Product Portfolio
- 7.3.3. Analysis by Radioisotope
- 7.3.4. Analysis by Application
- 7.3.5. Analysis by Manufacturing Capabilities
- 7.3.6. Analysis by Headquarters Location
- 7.3.7. Most Active Players: Analysis by Product Portfolio
8. COMPANY COMPETITIVENESS ANALYSIS
- 8.1. Chapter Overview
- 8.2. Assumptions and Key Parameters
- 8.3. Methodology
- 8.4. Overview of Peer Groups Based in France
9. COMPANY PROFILES: KEY MARKET PLAYERS
- 9.1. Chapter Overview
- 9.2. Advanced Accelerator Applications (Novartis)
- 9.2.1. Company Overview
- 9.2.2. Radiopharmaceutical Portfolio
- 9.2.3. Theranostics Portfolio
- 9.2.4. Manufacturing and Distribution Capabilities
- 9.2.5. Recent Developments
- Similar details are presented for other below mentioned players based on information in the public domain
- 9.3. CIS bio international
- 9.4. Curium
- 9.5. Cardinal Health
- 9.6. Eckert & Ziegler
- 9.7. Guerbet
- 9.8. Ion Beam Applications (IBA)
- 9.9. ITM Isotope Technologies Munich
- 9.10. Orano Med
- 9.11. SOFIE
- 9.12. Telix Pharmaceuticals
- 9.13. Zionexa
10. PARTNERSHIPS AND COLLABORATIONS
- 10.1. Chapter Overview
- 10.2. Partnership Models
- 10.3. France Radiopharmaceuticals and Theranostics: Partnerships and Collaborations
- 10.3.1. Analysis by Year of Partnership
- 10.3.2. Analysis by Type of Partnership
- 10.3.3. Analysis by Year and Type of Partnership
- 10.3.4. Analysis by Product Type
- 10.3.5. Analysis by Radioisotope
- 10.3.6. Analysis by Application
- 10.3.7. Most Active Players: Analysis by Number of Partnerships
- 10.3.8. Analysis by Geography
- 10.3.8.1. Domestic Partnerships
- 10.3.8.2. International Partnerships
- 10.3.8.3. Cross-Border Supply Chain Partnerships
11. FUNDING AND INVESTMENTS
- 11.1. Chapter Overview
- 11.2. Funding Models
- 11.3. France Radiopharmaceuticals and Theranostics: Funding and Investment Analysis
- 11.3.1. Analysis by Year of Funding
- 11.3.1.1. Cumulative Year-wise Trend of Funding Instances
- 11.3.1.2. Cumulative Year-wise Trend of Amount Invested
- 11.3.2. Analysis by Type of Funding
- 11.3.2.1. Analysis of Funding Instances
- 11.3.2.2. Analysis of Amount Invested
- 11.3.3. Analysis by Year and Type of Funding
- 11.3.4. Analysis by Amount Raised by Year and Type of Funding
- 11.3.5. Analysis by Product Type
- 11.3.6. Analysis by Radioisotope
- 11.3.7. Analysis by Geography
- 11.3.8. Most Active Players: Analysis by Number of Funding Instances
- 11.3.9. Most Active Players: Analysis by Amount Raised
- 11.3.1. Analysis by Year of Funding
- 11.4. Summary of Funding and Investments
12. MEGA TRENDS
- 12.1. Chapter Overview
- 12.2. Singapore RNA Therapeutics Manufacturing: Key Megatrends
13. MARKET IMPACT ANALYSIS
- 13.1. Chapter Overview
- 13.2. Market Drivers
- 13.3. Market Restraints
- 13.4. Market Opportunities
- 13.5. Market Challenges
- 13.6. Conclusion
14. FRANCE RADIOPHARMACEUTICALS AND THERANOSTICS MARKET
- 14.1. Chapter Overview
- 14.2. Assumptions and Methodology
- 14.3. France Radiopharmaceuticals and Theranostics Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 14.4. Scenario Analysis
- 14.4.1. Conservative Scenario
- 14.4.2. Base Scenario
- 14.4.3. Optimistic Scenario
- 14.5. Key Market Segmentations
- 14.5.1. By Product Type
- 14.5.2. By Type of Radioisotope
- 14.5.3. By Application
- 14.5.4. By End User
- 14.5.5. By Distribution Channel
- 14.5.6. By Region within France
15. FRANCE RADIOPHARMACEUTICALS AND THERANOSTICS MARKET, BY TYPE OF PRODUCT
- 15.1. Chapter Overview
- 15.2. Key Assumptions and Methodology
- 15.3. France Radiopharmaceuticals and Theranostics Market: Distribution by Product Type
- 15.3.1. Diagnostic Radiopharmaceuticals Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 15.3.2. Therapeutic Radiopharmaceuticals (Radioligand Therapy) Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 15.4. Data Triangulation and Validation
16. FRANCE RADIOPHARMACEUTICALS AND THERANOSTICS MARKET, BY TYPE OF RADIOISOTOPE
- 16.1. Chapter Overview
- 16.2. Key Assumptions and Methodology
- 16.3. France Radiopharmaceuticals and Theranostics Market: Distribution by Type of Radioisotope
- 16.3.1. Lutetium-177 (177Lu) Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 16.3.2. Gallium-68 (68Ga) Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 16.3.3. Fluorine-18 (18F) Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 16.3.4. Iodine-131 (131I) Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 16.3.5. Yttrium-90 (9°Y) Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 16.3.6. Actinium-225 / Lead-212 Targeted Alpha Therapy Isotopes Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 16.3.7. Other Radioisotopes Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 16.4. Data Triangulation and Validation
17. FRANCE RADIOPHARMACEUTICALS AND THERANOSTICS MARKET, BY APPLICATION
- 17.1. Chapter Overview
- 17.2. Key Assumptions and Methodology
- 17.3. France Radiopharmaceuticals and Theranostics Market: Distribution by Application
- 17.3.1. Oncology Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 17.3.1.1. Prostate Cancer
- 17.3.1.2. Neuroendocrine Tumors
- 17.3.1.3. Other Oncology Applications
- 17.3.2. Cardiology Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 17.3.3. Neurology Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 17.3.4. Other Applications Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 17.3.1. Oncology Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 17.4. Data Triangulation and Validation
18. FRANCE RADIOPHARMACEUTICALS AND THERANOSTICS MARKET, BY END USER
- 18.1. Chapter Overview
- 18.2. Key Assumptions and Methodology
- 18.3. France Radiopharmaceuticals and Theranostics Market: Distribution by End User
- 18.3.1. Hospitals and University Medical Centers Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 18.3.2. Private Diagnostic Imaging Centers Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 18.3.3. Academic and Research Institutes Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 18.4. Data Triangulation and Validation
19. FRANCE RADIOPHARMACEUTICALS AND THERANOSTICS MARKET, BY DISTRIBUTION CHANNEL
- 19.1. Chapter Overview
- 19.2. Key Assumptions and Methodology
- 19.3. France Radiopharmaceuticals and Theranostics Market: Distribution by Distribution Channel
- 19.3.1. Direct-to-Hospital Supply Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 19.3.2. Third-Party Distributors and Radiopharmacy Networks Market, Historic Trend (Since 2022) and Forecasted Estimates (Till 2035)
- 19.4. Data Triangulation and Validation
20. CONCLUSION AND FUTURE PERSPECTIVES
21. APPENDIX I: TABULATED DATA
22. APPENDIX II: LIST OF COMPANIES AND ORGANIZATIONS

