PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2121176

PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2121176
IoT in Construction Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
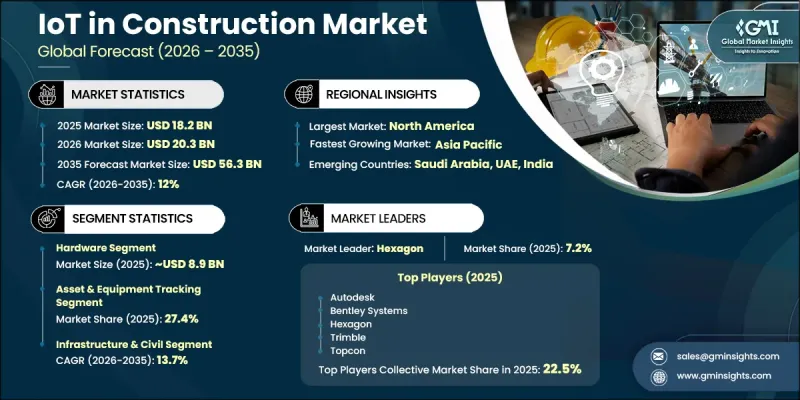
The Global IoT in Construction Market was valued at USD 18.2 billion in 2025 and is estimated to grow at a CAGR of 12% to reach USD 56.3 billion by 2035.
The global IoT in construction market is experiencing momentum as construction companies increasingly replace disconnected manual workflows with intelligent, connected ecosystems that improve operational visibility and decision-making. The widespread adoption of sensor-enabled infrastructure, cloud-based platforms, real-time analytics, and artificial intelligence is reshaping how projects are managed, monitored, and executed across the construction industry. As digital transformation accelerates, IoT technologies are becoming an integral part of construction operations by enabling continuous asset monitoring, workforce visibility, and more efficient project management. Advances in hardware miniaturization, cloud computing, and intelligent data processing are further strengthening market growth by allowing organizations to deploy scalable connected solutions across construction sites. Regulatory emphasis on workplace safety and risk management also encourages broader implementation of IoT-enabled monitoring systems capable of generating continuous, real-time operational data that supports compliance requirements. At the same time, predictive maintenance powered by AI and IoT continues to gain importance by helping construction companies reduce unexpected equipment downtime, improve operational efficiency, extend asset life cycles, and lower long-term maintenance costs.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $18.2 Billion |
| Forecast Value | $56.3 Billion |
| CAGR | 12% |
The hardware segment held a 48.9% share, generating USD 8.9 billion in 2025. Hardware remains the foundation of connected construction environments, supporting data collection, communication, and real-time monitoring across project sites. The segment includes a broad range of connected devices, monitoring equipment, positioning technologies, identification systems, edge computing infrastructure, communication modules, and industrial-grade wearable technologies designed to operate reliably under demanding construction site conditions. Continuous demand for durable, high-performance connected hardware continues to strengthen this segment's leadership within the market.
The asset & equipment tracking segment held a 27.4% share in 2025. This application area continues to maintain the largest share because efficient equipment utilization and real-time asset visibility remain critical priorities across construction projects. Organizations are increasingly deploying connected tracking solutions to improve operational efficiency, optimize equipment allocation, minimize asset losses, and enhance project productivity while reducing unnecessary operating costs.
North America IoT in Construction Market held a 38.6% share in 2025. Regional market leadership is supported by a well-established construction technology ecosystem, ongoing investment in digital transformation, and increasing adoption of connected construction platforms. Growing regulatory focus on workplace safety and compliance is encouraging construction companies to implement advanced IoT-enabled monitoring solutions that improve operational transparency, strengthen risk management practices, and support safer project execution. Continued investments in digital infrastructure and intelligent construction technologies are expected to reinforce regional market growth over the coming years.
Major companies operating in Global IoT in construction market include Trimble, Caterpillar, Autodesk, Bentley Systems, Hexagon, Komatsu, Procore Technologies, PTC, Topcon, and Trackunit. Leading companies in the IoT in construction market are strengthening their market position by investing in advanced IoT platforms, artificial intelligence, cloud-based construction management solutions, and connected hardware technologies. Businesses continue to expand research and development efforts to improve real-time analytics, predictive maintenance capabilities, and intelligent project management solutions. Strategic collaborations with technology providers, equipment manufacturers, and construction firms are accelerating product innovation and market penetration. Companies are also enhancing software interoperability, integrating connected ecosystems, and developing scalable platforms that simplify deployment across projects of varying sizes.
Table of Contents
Chapter 1 Research Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Offering
- 2.2.3 Application
- 2.2.4 Project
- 2.2.5 Enterprise Size
- 2.3 TAM analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Stringent Worker Safety Regulations
- 3.2.1.2 Expansion of Connected Construction Equipment
- 3.2.1.3 Government Initiatives Supporting Digital Construction
- 3.2.1.4 Increasing Demand for Real-Time Project Monitoring
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High Upfront Capital Costs of IoT Hardware Deployment & Integration
- 3.2.2.2 Cybersecurity Vulnerabilities & Data Privacy Concerns
- 3.2.3 Market opportunities
- 3.2.3.1 Growing Adoption of Digital Twins & BIM-IoT Integration
- 3.2.3.2 Growing Adoption of AI-Enabled IoT Solutions
- 3.2.3.3 Expansion of Autonomous and Connected Construction Machinery
- 3.2.1 Growth drivers
- 3.3 Technology and innovation landscape
- 3.3.1 Current technological trends
- 3.3.1.1 IoT Sensors & Smart Monitoring Devices
- 3.3.1.2 GPS-Based Equipment Tracking Systems
- 3.3.1.3 Cloud-Based Construction Management Platforms
- 3.3.2 Emerging technologies
- 3.3.2.1 Connected Wearable Safety Devices
- 3.3.2.2 Digital Twin Technology
- 3.3.2.3 Autonomous Construction Equipment
- 3.3.1 Current technological trends
- 3.4 Growth potential analysis
- 3.5 Pricing Analysis (Driven by Primary Research)
- 3.5.1 Historical Price Trend Analysis, 2022-2025
- 3.5.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.5.3 Pricing Models by IoT Offering
- 3.5.4 Hardware, Software, Connectivity & Services Pricing
- 3.6 Regulatory landscape
- 3.6.1 North America
- 3.6.1.1 FCC Radio Frequency and IoT Device Requirements – U.S.
- 3.6.1.2 OSHA Construction Safety and Wearable/Connected Worker Requirements – U.S.
- 3.6.1.3 Innovation, Science and Economic Development (ISED) Radio Equipment Requirements – Canada
- 3.6.2 Europe
- 3.6.2.1 EU Radio Equipment Directive (RED)
- 3.6.2.2 EU Cyber Resilience Act (CRA)
- 3.6.2.3 General Data Protection Regulation (GDPR)
- 3.6.2.4 EU Data Act
- 3.6.2.5 Product Security and Telecommunications Infrastructure (PSTI) Act 2022
- 3.6.2.6 IT Security Act 2.0
- 3.6.2.7 German Federal Data Protection Act (BDSG)
- 3.6.3 Asia Pacific
- 3.6.3.1 Chinese Ministry of Industry and Information Technology (MIIT)
- 3.6.3.2 Telecommunications Regulatory Authority of India (TRAI)
- 3.6.3.3 Radio Act (Japan)
- 3.6.3.4 Act on the Protection of Personal Information (APPI) (Japan)
- 3.6.4 LATAM
- 3.6.4.1 ANATEL (Brazil)
- 3.6.4.2 Instituto Federal de Telecomunicaciones (IFT) (Mexico)
- 3.6.5 MEA
- 3.6.5.1 Telecommunications and Digital Government Regulatory Authority (UAE)
- 3.6.5.2 Communications, Space and Technology Commission (Saudi Arabia)
- 3.6.1 North America
- 3.7 Porter’s analysis
- 3.8 PESTEL analysis
- 3.9 Cost breakdown analysis, 2025
- 3.10 Patent analysis (Driven by Primary Research)
- 3.11 Use Cases
- 3.12 Digital Transformation Readiness in Construction, 2022-2035
- 3.12.1 Digital Maturity Assessment Framework by Region & Enterprise Size
- 3.12.2 Barriers to Digital Adoption in the Construction Sector
- 3.12.3 Readiness Index by Project Type, 2022-2035
- 3.13 Impact of AI & generative AI on the market
- 3.13.1 AI-driven disruption of existing business models
- 3.13.2 GenAI use cases & adoption roadmap by segment
- 3.13.3 Risks, limitations & regulatory considerations
- 3.14 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.14.1 Base Case- Key Macro & Industry Variables Driving CAGR
- 3.14.2 Optimistic Scenarios- Favorable macro and industry tailwinds
- 3.14.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis, 2022-2025
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates and Forecast, By Offering, 2022 – 2035 ($ Mn, Units)
- 5.1 Key trends
- 5.2 Hardware
- 5.2.1 Sensors
- 5.2.2 Wearables
- 5.2.3 RFID Tags & Readers
- 5.2.4 GPS/GNSS Trackers
- 5.2.5 Telematics Units
- 5.2.6 Cameras & Drones
- 5.2.7 Others
- 5.3 Software
- 5.3.1 Project Management & Site Intelligence Platforms
- 5.3.2 Asset Tracking & Equipment Management Software
- 5.3.3 Safety & Compliance Management Software
- 5.3.4 Predictive Analytics & AI/ML Platforms
- 5.3.5 Others
- 5.4 Services
- 5.4.1 Professional Services
- 5.4.1.1 Consulting & Advisory
- 5.4.1.2 System Integration & Deployment
- 5.4.1.3 Training
- 5.4.2 Managed Services
- 5.4.1 Professional Services
Chapter 6 Market Estimates and Forecast, By Application, 2022 – 2035 ($ Mn)
- 6.1 Key trends
- 6.2 Safety & Worker Management
- 6.3 Asset & Equipment Tracking
- 6.4 Remote Equipment Control & Automation
- 6.5 Predictive Maintenance
- 6.6 Structural Health Monitoring
- 6.7 Environmental & Compliance Monitoring
- 6.8 Others
Chapter 7 Market Estimates and Forecast, By Project, 2022 – 2035 ($ Mn)
- 7.1 Key trends
- 7.2 Commercial
- 7.3 Residential
- 7.4 Infrastructure & Civil
- 7.5 Industrial
Chapter 8 Market Estimates and Forecast, By Enterprise Size, 2022 – 2035 ($ Mn)
- 8.1 Key trends
- 8.2 Large Enterprises
- 8.3 SMEs
Chapter 9 Market Estimates & Forecast, By Region, 2022 - 2035 ($Mn, Units)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 US
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Italy
- 9.3.5 Spain
- 9.3.6 Russia
- 9.3.7 Netherlands
- 9.3.8 Sweden
- 9.3.9 Norway
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 South Korea
- 9.4.5 Australia
- 9.4.6 Singapore
- 9.4.7 New Zealand
- 9.4.8 Indonesia
- 9.4.9 Thailand
- 9.4.10 Vietnam
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Chile
- 9.6 MEA
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global players
- 10.1.1 Trimble
- 10.1.2 Topcon
- 10.1.3 Hexagon
- 10.1.4 Trackunit
- 10.1.5 Caterpillar
- 10.1.6 Komatsu
- 10.1.7 Hitachi Construction Machinery
- 10.1.8 Volvo CE
- 10.1.9 Microsoft
- 10.1.10 PTC
- 10.1.11 Bentley Systems
- 10.1.12 Oracle
- 10.2 Regional players
- 10.2.1 WorldSensing
- 10.2.2 WakeCap
- 10.2.3 DroneDeploy
- 10.2.4 36Zero
- 10.2.5 Procore Technologies
- 10.3 Emerging players
- 10.3.1 Buildots
- 10.3.2 Versatile
- 10.3.3 Kwant.ai

