PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2152959

PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2152959
Aseptic Packaging Market by Material (Plastic, Metal, Glass, Paper & Paperboard), Type (Cartons, Bottles & Cans, Bags & Pouches, Vial, Ampoules and Prefillable Syringes), Application (Beverage, Food, Pharmaceutical), & Region - Global Forecast to 2031
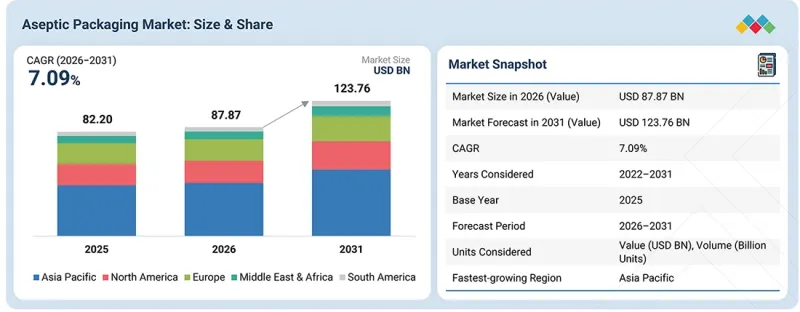
The aseptic packaging market is projected to reach USD 123.76 billion in 2031 from USD 87.87 billion in 2026, at a CAGR of 7.09% from 2026 to 2031.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2022-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million) / Volume (Billion Units) |
| Segments | Material, Type, Application, and Region |
| Regions covered | North America, Asia Pacific, Europe, the Middle East & Africa, and South America |
The aseptic packaging market is driven by extensive food loss across supply chains, beverage category diversification, rising demand for portion-controlled formats, and increasing sterile pharmaceutical product activity.
"The paper & paperboard segment is projected to be the second largest during the forecast period."
The paper & paperboard segment is expected to be second largest segment as one of the main materials in the global aseptic packaging market. This high profile can be attributed to the scale and nature of the production of liquid cartons for dairy products, vegetable milk alternatives, juices, and other liquid foods. Paperboard is considered to be the essential structural component of multi-laminate system of packaging material combining the necessary characteristics of rigidity and thickness and the high-quality printing surface. The huge share of paperboard in the market is supported by the food and agriculture industries that strive to shift from bulky packaging to space-saving packaging in the shape of block cartons, which optimize shipping efficiency. Furthermore, since paperboard is manufactured from renewable wood fibers, this usage largely matches the corporate sustainability efforts aimed at decreasing carbon footprint. Finally, the latest developments in bio-based protective coatings that keep food sterile without excessive usage of plastics guarantee the place of the paperboard segment in the second position in global sales.
"The bottles & cans segment is projected to be the second largest during the forecast period."
The bottles & cans segment is anticipated to be the second-largest segment within the global aseptic packaging industry. The reason behind this major share in the market is due to increasing market demand for high-end ready-to-drink beverages, clinical nutritional liquids, and specialty dairy products. Usage of aseptic filling technology for plastic bottles (like PET and HDPE) and aluminum cans protects delicate liquids in completely sterile environments, helping maintain freshness, flavor, and aroma without the need for preservatives. Bottles and cans are especially popular amongst brands in the consumer packaged goods (CPG) industry because of the unique properties of their rigid structures that provide a remarkable level of safety and protection when being transported across long distances. Moreover, dynamic innovations in dry forming technologies and lightweight technologies have caused a dramatic drop in both material and water consumption in these formats. All those features assure Bottles & Cans sector is the second most important segment in the market.
"Food segment projected to be the second largest during the forecast period."
The food segment is projected to be the second largest application segment in the global aseptic packaging market. The substantial volume of aseptic packaging is attributed to the mass production of perishable food products, such as liquid egg, soups, broths, baby food, tomato paste, and ready meals. In the aseptic treatment process, food products undergo flash sterilization away from the container, preventing any loss of natural flavors, colors, textures, and vitamins, and using no chemicals or refrigeration. This effectively equips producers with the ability to distribute their products across complicated supply chains unburdened by various problems, including the unreliability of cold supply chains. The design also has certain robustness, which allows for the shipment of materials safely. At the same time, the demand for shelf-stable, ready-to-eat, and easy-to-read products continues to grow, thereby ensuring a secure second place for the food segment.
"In terms of value, the North America region is projected to be the second-largest segment during the forecast period."
The North America region is anticipated to be the second leading geographic segment in the global aseptic packaging industry. This significant position in the market is mainly attributed to the overall development of the food and beverage and the pharmaceutical industry in the United States and Canada. In North America, the growing preference of consumers for convenience-related products leads to the growing demand for premium ready-to-drink functional beverages, organic clean-label dairy alternatives, and portion-controlled single-serve meals. Moreover, the biopharmaceutical industry in North America, as well as biotechnological advancements, depends on aseptic technologies designed to secure therapeutic agents, biologics, and vaccines against microbial contamination. The presence of strict regional regulations requiring companies to follow aseptic manufacturing norms, the availability of developed delivery systems for e-commerce, and companies striving to develop environmentally-friendly packaging formats have contributed to achieving the second position among other regions in the market.
By Company Type: Tier 1: 25%, Tier 2: 42%, and Tier 3: 33%
By Designation: C-level Executives: 20%, Directors: 30%, and Other Designations: 50%
By Region: North America: 20%, Europe: 10%, Asia Pacific: 40%, South America: 10%, and Middle East & Africa 20%
Notes: Other designations include sales, marketing, and product managers.
Tier 1: >USD 1 Billion; Tier 2: USD 500 million-1 Billion; and Tier 3: <USD 500 million
Companies Covered: Amcor plc (Switzerland), Mondi plc (UK), Smurfit Westrock plc (Ireland), TOPPAN Holdings Inc. (Japan), Graphic Packaging Holding Company (US), Nippon Paper Industries Co., Ltd. (Japan), Dai Nippon Printing Co., Ltd. (DNP) (Japan), Huhtamaki Oyj (Finland), Stora Enso Oyj (Finland), Tetra Pak International S.A. (Switzerland), among others, are covered in the report.
The study includes an in-depth competitive analysis of these key players in the aseptic packaging market, with their company profiles, recent developments, and key market strategies.
Research Coverage
This research report categorizes the aseptic packaging market based on material (plastic, metal, glass, paper & paperboard, others), type (cartons, bottles & cans, bags & pouches, vials, ampoules and prefillable syringes, others), application (beverage, food, pharmaceutical, others), and region (North America, Europe, Asia Pacific, Middle East & Africa, and South America). The report's scope covers detailed information regarding the drivers, restraints, challenges, and opportunities influencing the growth of the aseptic packaging market. A detailed analysis of the key industry players has been done to provide insights into their business overview, products offered, and key strategies, such as partnerships, collaborations, product launches, expansions, and acquisitions, associated with the aseptic packaging market. This report covers a competitive analysis of upcoming startups in the aseptic packaging market ecosystem.
Reasons to Buy the Report
The report will offer market leaders/new entrants with information on the closest approximations of the revenue numbers for the overall aseptic packaging market and the subsegments. This report will help stakeholders understand the competitive landscape, gain more insights into positioning their businesses better, and plan suitable go-to-market strategies. The report will help stakeholders understand the pulse of the market and provide them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following points:
Analysis of key drivers (extensive food loss across supply chains, beverage category diversification beyond traditional milk, increasing demand for portion-controlled food formats, increasing sterile pharmaceutical product activity), restraints (high capital requirements for aseptic production, high pharmaceutical packaging qualification requirements), opportunities (expansion of processed food export activity, pharmaceutical prefilled syringe and injectable packaging, growth of plant-based dairy alternatives), and challenges (variations in environmental mandates across regions, cost-to-benefit ratio a concern to small manufacturers).
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and product & service launches in the aseptic packaging market.
- Market Development: Comprehensive information about profitable markets - the report analyzes the aseptic packaging market across varied regions.
Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the aseptic packaging market.
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players: Amcor plc (Switzerland), Mondi plc (UK), Smurfit Westrock plc (Ireland), TOPPAN Holdings Inc. (Japan), Graphic Packaging Holding Company (US), Nippon Paper Industries Co., Ltd. (Japan), Dai Nippon Printing Co., Ltd. (DNP) (Japan), Huhtamaki Oyj (Finland), Stora Enso Oyj (Finland), Tetra Pak International S.A. (Switzerland).
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED & REGIONAL SCOPE
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.3.4 CURRENCY CONSIDERED
- 1.3.5 UNIT CONSIDERED
- 1.3.6 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING THE MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN ASEPTIC PACKAGING MARKET
- 3.2 ASEPTIC PACKAGING MARKET, BY MATERIAL AND TYPE
- 3.3 ASEPTIC PACKAGING MARKET, BY APPLICATION
- 3.4 ASEPTIC PACKAGING MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Extensive food loss across supply chains
- 4.2.1.2 Beverage category diversification beyond traditional milk
- 4.2.1.3 Increasing demand for portion-controlled food formats
- 4.2.1.4 Increasing sterile pharmaceutical product activity
- 4.2.2 RESTRAINTS
- 4.2.2.1 High capital requirements for aseptic production
- 4.2.2.2 High pharmaceutical packaging qualification requirements
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Expansion of processed food export activity
- 4.2.3.2 Pharmaceutical prefilled syringe and injectable packaging
- 4.2.3.3 Growth of plant-based dairy alternatives
- 4.2.4 CHALLENGES
- 4.2.4.1 Variations in environmental mandates across regions
- 4.2.4.2 Cost-to-benefit ratio concern of small manufacturers
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS
- 4.3.1.1 High-barrier aseptic packaging with lower material complexity and improved recyclability
- 4.3.1.2 Flexible aseptic formats support complex food formulations and portion sizes
- 4.3.2 WHITE SPACES
- 4.3.2.1 Low-carbon aseptic packaging with verified product-level environmental performance
- 4.3.2.2 Intelligent aseptic packaging for real-time product and supply-chain monitoring
- 4.3.1 UNMET NEEDS
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC ANALYSIS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECASTS
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE TREND AMONG KEY PLAYERS, BY APPLICATION, 2025
- 5.5.2 AVERAGE SELLING PRICE TREND, BY REGION, 2022-2025
- 5.6 TRADE ANALYSIS
- 5.6.1 EXPORT DATA FOR HS CODE 392310
- 5.6.2 IMPORT DATA FOR HS CODE 392310
- 5.6.3 EXPORT DATA FOR HS CODE 4819
- 5.6.4 IMPORT DATA FOR HS CODE 4819
- 5.7 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.8 TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 LASSONDE WINE PACKAGING TRANSFORMATION: REPLACING GLASS WITH ASEPTIC CARTONS
- 5.10.2 HOCHWALD SUSTAINABLE ASEPTIC MILK PACKAGING: ELIMINATING ALUMINUM FROM ASEPTIC CARTONS
- 5.10.3 MENGNIU FLAVORED MILK PACKAGING INNOVATION: DIFFERENTIATING FLAVORED MILK THROUGH ASEPTIC PACKAGING
- 5.11 IMPACT OF 2025 US TARIFF ON ASEPTIC PACKAGING MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 PRICE IMPACT ANALYSIS
- 5.11.3 KEY IMPACT ON VARIOUS REGIONS
- 5.11.3.1 US
- 5.11.3.2 Europe
- 5.11.3.3 Asia Pacific
- 5.11.4 END-USE SECTOR IMPACT
6 STRATEGIC DISRUPTION THROUGH TECHNOLOGY, PATENTS, DIGITAL, AND AI ADOPTIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 ASEPTIC FILLING AND SEALING TECHNOLOGY
- 6.1.2 ELECTRON BEAM STERILIZATION TECHNOLOGY
- 6.1.3 HIGH BARRIER MULTILAYER ASEPTIC PACKAGING TECHNOLOGY
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 ASEPTIC CLOSURE AND SPOUT TECHNOLOGY
- 6.2.2 IN-LINE ASEPTIC PACKAGING INSPECTION TECHNOLOGY
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 RETORT PACKAGING TECHNOLOGY
- 6.3.2 MODIFIED ATMOSPHERE PACKAGING (MAP) TECHNOLOGY
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 SHORT-TERM (2025-2027) | BARRIER OPTIMIZATION & STERILIZATION EFFICIENCY PHASE
- 6.4.2 MID-TERM (2027-2030): SMART FILLING & ADVANCED MATERIALS PHASE
- 6.4.3 LONG-TERM (2030-2035+): INTELLIGENT CIRCULAR ASEPTIC PACKAGING PHASE
- 6.5 PATENT ANALYSIS
- 6.5.1 INTRODUCTION
- 6.5.2 APPROACH
- 6.5.3 TOP APPLICANTS
- 6.5.4 JURISDICTION ANALYSIS
- 6.6 FUTURE APPLICATIONS
- 6.6.1 ASEPTIC PACKAGING FOR PRECISION FERMENTATION INGREDIENTS
- 6.6.2 ASEPTIC PACKAGING FOR CULTIVATED MEAT CULTURE MEDIA
- 6.6.3 ASEPTIC PACKAGING FOR ENZYME-BASED FOOD PROCESSING SYSTEMS
- 6.6.4 ASEPTIC PACKAGING FOR LAB-GROWN BIOLOGICAL REAGENTS
- 6.6.5 SELF-MONITORING ASEPTIC PACKAGES FOR STERILITY ASSURANCE
- 6.7 IMPACT OF AI/GEN AI ON ASEPTIC PACKAGING MARKET
- 6.7.1 TOP USE CASES AND MARKET POTENTIAL
- 6.7.2 BEST PRACTICES FOLLOWED BY MANUFACTURERS/OEMS IN ASEPTIC PACKAGING
- 6.7.3 CASE STUDIES OF AI IMPLEMENTATION IN ASEPTIC PACKAGING MARKET
- 6.7.4 INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.7.5 CLIENTS' READINESS TO ADAPT AI-INTEGRATED ASEPTIC PACKAGING
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 CARBON IMPACT REDUCTION INITIATIVES
- 7.2.1.1 Replacing Aluminum With Lower Carbon Barrier Structures
- 7.2.1.2 Increasing Renewable and Responsibly Sourced Materials
- 7.2.1.3 Lightweighting and Material-Efficient Package Design
- 7.2.2 ECO APPLICATIONS IN ASEPTIC PACKAGING
- 7.2.2.1 Renewable Material Aseptic Cartons
- 7.2.2.2 Aseptic Packaging Designed for Recycling
- 7.2.2.3 Circular Polymer Aseptic Packaging
- 7.2.1 CARBON IMPACT REDUCTION INITIATIVES
- 7.3 IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, ECO-STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USES
- 8.5 MARKET PROFITABILITY
- 8.5.1 REVENUE POTENTIAL
- 8.5.2 COST DYNAMICS
- 8.6 MARGIN OPPORTUNITIES, BY APPLICATIONS
- 8.6.1 FOOD
- 8.6.2 BEVERAGES
- 8.6.3 PHARMACEUTICALS
- 8.6.4 OTHER APPLICATIONS
9 ASEPTIC PACKAGING MARKET, BY MATERIAL
- 9.1 INTRODUCTION
- 9.2 PLASTIC
- 9.2.1 PLASTIC PACKAGING ENABLES FLEXIBLE ASEPTIC FORMATS ACROSS DIVERSE APPLICATIONS
- 9.3 PAPER AND PAPERBOARD
- 9.3.1 PAPER AND PAPERBOARD REMAIN CENTRAL TO LIGHTWEIGHT ASEPTIC CARTON CONSTRUCTION
- 9.4 METAL
- 9.4.1 METAL PACKAGING PROVIDES HIGH BARRIER PROTECTION FOR SPECIALIZED ASEPTIC APPLICATIONS
- 9.5 GLASS
- 9.5.1 GLASS SUPPORTS STERILE PHARMACEUTICAL PACKAGING THROUGH CHEMICAL STABILITY AND BARRIER PERFORMANCE
- 9.6 OTHER MATERIALS
10 ASEPTIC PACKAGING MARKET, BY TYPE
- 10.1 INTRODUCTION
- 10.2 CARTONS
- 10.2.1 CARTONS COMBINE LIGHTWEIGHT STRUCTURES WITH HIGH BARRIER PROTECTION
- 10.3 BOTTLES & CANS
- 10.3.1 BOTTLES AND CANS EXTEND ASEPTIC PACKAGING INTO RIGID CONTAINER APPLICATIONS
- 10.4 BAGS & POUCHES
- 10.4.1 BAGS AND POUCHES IMPROVE MATERIAL EFFICIENCY THROUGH FLEXIBLE ASEPTIC DESIGNS
- 10.5 VIALS, AMPOULES AND PREFILLABLE SYRINGES
- 10.5.1 VIALS, AMPOULES, AND PREFILLABLE SYRINGES SUPPORT HIGH INTEGRITY STERILE DRUG DELIVERY
- 10.6 OTHER TYPES
11 ASEPTIC PACKAGING MARKET, BY APPLICATION
- 11.1 INTRODUCTION
- 11.2 BEVERAGE
- 11.2.1 BEVERAGE APPLICATIONS DRIVE ASEPTIC PACKAGING THROUGH AMBIENT DISTRIBUTION AND PRODUCT DIVERSIFICATION
- 11.3 FOOD
- 11.3.1 FOOD APPLICATIONS EXPAND ASEPTIC PACKAGING BEYOND LIQUID DAIRY AND JUICES
- 11.4 PHARMACEUTICAL
- 11.4.1 PHARMACEUTICAL APPLICATIONS REQUIRE VALIDATED STERILE CONTAINMENT AND DELIVERY COMPATIBILITY
- 11.5 OTHER APPLICATIONS
12 ASEPTIC PACKAGING MARKET, BY REGION
- 12.1 INTRODUCTION
- 12.2 ASIA PACIFIC
- 12.2.1 CHINA
- 12.2.1.1 Expanding food and pharmaceutical industries support aseptic packaging demand
- 12.2.2 INDIA
- 12.2.2.1 Food processing expansion and pharmaceutical scale support aseptic packaging demand
- 12.2.3 JAPAN
- 12.2.3.1 Export growth and pharmaceutical base sustain aseptic packaging demand
- 12.2.4 SOUTH KOREA
- 12.2.4.1 Food export expansion and pharmaceutical output support aseptic packaging demand
- 12.2.5 AUSTRALIA
- 12.2.5.1 Food export strength and pharmaceutical manufacturing support aseptic packaging demand
- 12.2.6 REST OF ASIA PACIFIC
- 12.2.1 CHINA
- 12.3 NORTH AMERICA
- 12.3.1 US
- 12.3.1.1 Consumer activity and manufacturing scale strengthen aseptic packaging demand
- 12.3.2 CANADA
- 12.3.2.1 Food, beverage, and pharmaceutical sectors support aseptic packaging demand
- 12.3.3 MEXICO
- 12.3.3.1 Food manufacturing and pharmaceutical base supports aseptic packaging demand
- 12.3.1 US
- 12.4 EUROPE
- 12.4.1 GERMANY
- 12.4.1.1 Food production scale and technology growth sustain aseptic packaging demand
- 12.4.2 UK
- 12.4.2.1 UK food consumption and pharmaceutical production support aseptic packaging demand
- 12.4.3 FRANCE
- 12.4.3.1 Food manufacturing scale and pharmaceutical stability sustain aseptic packaging demand
- 12.4.4 SPAIN
- 12.4.4.1 Food manufacturing scale and pharmaceutical investment sustain aseptic packaging demand
- 12.4.5 ITALY
- 12.4.5.1 Italy's food manufacturing base and pharmaceutical output sustain aseptic packaging demand
- 12.4.6 REST OF EUROPE
- 12.4.1 GERMANY
- 12.5 MIDDLE EAST & AFRICA
- 12.5.1 GCC COUNTRIES
- 12.5.2 SAUDI ARABIA
- 12.5.2.1 Food and pharmaceutical infrastructure supports aseptic packaging demand
- 12.5.3 UAE
- 12.5.3.1 Food manufacturing expansion and economic diversification support aseptic packaging demand
- 12.5.4 REST OF GCC COUNTRIES
- 12.5.5 SOUTH AFRICA
- 12.5.5.1 Food processing and pharmaceutical base supports aseptic packaging demand
- 12.5.6 REST OF MIDDLE EAST & AFRICA
- 12.6 SOUTH AMERICA
- 12.6.1 BRAZIL
- 12.6.1.1 Brazil's agribusiness and manufacturing expansion supports aseptic packaging demand
- 12.6.2 ARGENTINA
- 12.6.2.1 Food and pharmaceutical sectors support aseptic packaging demand
- 12.6.3 REST OF SOUTH AMERICA
- 12.6.1 BRAZIL
13 COMPETITIVE LANDSCAPE
- 13.1 OVERVIEW
- 13.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 13.3 REVENUE ANALYSIS, 2021-2025
- 13.4 MARKET SHARE ANALYSIS, 2025
- 13.5 BRAND COMPARISON
- 13.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 13.6.1 STARS
- 13.6.2 EMERGING LEADERS
- 13.6.3 PERVASIVE PLAYERS
- 13.6.4 PARTICIPANTS
- 13.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2026
- 13.6.5.1 Company footprint
- 13.6.5.2 Region footprint
- 13.6.5.3 Material footprint
- 13.6.5.4 Type footprint
- 13.6.5.5 Application footprint
- 13.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 13.7.1 PROGRESSIVE COMPANIES
- 13.7.2 RESPONSIVE COMPANIES
- 13.7.3 DYNAMIC COMPANIES
- 13.7.4 STARTING BLOCKS
- 13.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 13.7.5.1 List of key startups/SMEs
- 13.7.5.2 Competitive benchmarking of key startups/SMEs
- 13.8 COMPANY VALUATION AND FINANCIAL METRICS
- 13.8.1 COMPANY VALUATION
- 13.8.2 FINANCIAL METRICS
- 13.9 COMPETITIVE SCENARIO
- 13.9.1 PRODUCT LAUNCHES
- 13.9.2 DEALS
- 13.9.3 EXPANSIONS
- 13.9.4 OTHER DEVELOPMENTS
14 COMPANY PROFILES
- 14.1 KEY PLAYERS
- 14.1.1 AMCOR PLC
- 14.1.1.1 Business overview
- 14.1.1.2 Products offered
- 14.1.1.3 Recent developments
- 14.1.1.3.1 Deals
- 14.1.1.3.2 Expansions
- 14.1.1.3.3 Other Developments
- 14.1.1.4 MnM view
- 14.1.1.4.1 Right to win
- 14.1.1.4.2 Strategic choices
- 14.1.1.4.3 Weakness and competitive threats
- 14.1.2 MONDI PLC
- 14.1.2.1 Business overview
- 14.1.2.2 Products offered
- 14.1.2.3 Recent developments
- 14.1.2.3.1 Product launches
- 14.1.2.4 MnM view
- 14.1.2.4.1 Right to win
- 14.1.2.4.2 Strategic choices
- 14.1.2.4.3 Weakness and competitive threats
- 14.1.3 SMURFIT WESTROCK PLC
- 14.1.3.1 Business overview
- 14.1.3.2 Products offered
- 14.1.3.3 Recent developments
- 14.1.3.3.1 Deals
- 14.1.3.3.2 Expansions
- 14.1.3.3.3 Other Developments
- 14.1.3.4 MnM view
- 14.1.3.4.1 Right to win
- 14.1.3.4.2 Strategic choices
- 14.1.3.4.3 Weakness and competitive threats
- 14.1.4 TOPPAN HOLDINGS INC.
- 14.1.4.1 Business overview
- 14.1.4.2 Products offered
- 14.1.4.3 Recent developments
- 14.1.4.3.1 Product launches
- 14.1.4.3.2 Deals
- 14.1.4.3.3 Expansions
- 14.1.4.4 MnM view
- 14.1.4.4.1 Right to win
- 14.1.4.4.2 Strategic choices
- 14.1.4.4.3 Weakness and competitive threats
- 14.1.5 GRAPHIC PACKAGING HOLDING COMPANY
- 14.1.5.1 Business overview
- 14.1.5.2 Products offered
- 14.1.5.3 Recent developments
- 14.1.5.3.1 Product launches
- 14.1.5.3.2 Deals
- 14.1.5.3.3 Expansions
- 14.1.5.4 MnM view
- 14.1.5.4.1 Right to win
- 14.1.5.4.2 Strategic choices
- 14.1.5.4.3 Weakness and competitive threats
- 14.1.6 NIPPON PAPER INDUSTRIES CO., LTD.
- 14.1.6.1 Business overview
- 14.1.6.2 Products offered
- 14.1.6.3 Recent developments
- 14.1.6.3.1 Product launches
- 14.1.6.4 MnM view
- 14.1.7 DAI NIPPON PRINTING CO., LTD. (DNP)
- 14.1.7.1 Business overview
- 14.1.7.2 Products offered
- 14.1.7.3 Recent developments
- 14.1.7.3.1 Product launches
- 14.1.7.3.2 Deals
- 14.1.7.3.3 Expansions
- 14.1.7.4 MnM view
- 14.1.8 HUHTAMAKI OYJ
- 14.1.8.1 Business overview
- 14.1.8.2 Products offered
- 14.1.8.3 Recent developments
- 14.1.8.3.1 Product launches
- 14.1.8.3.2 Deals
- 14.1.8.3.3 Expansions
- 14.1.8.4 MnM view
- 14.1.9 STORA ENSO OYJ
- 14.1.9.1 Business overview
- 14.1.9.2 Products offered
- 14.1.9.3 Recent developments
- 14.1.9.3.1 Product launches
- 14.1.9.3.2 Deals
- 14.1.9.3.3 Expansions
- 14.1.9.4 MnM view
- 14.1.10 TETRA PAK INTERNATIONAL S.A.
- 14.1.10.1 Business overview
- 14.1.10.2 Products offered
- 14.1.10.3 Recent developments
- 14.1.10.3.1 Product launches
- 14.1.10.3.2 Deals
- 14.1.10.3.3 Expansions
- 14.1.10.4 MnM view
- 14.1.1 AMCOR PLC
- 14.2 OTHER PLAYERS
- 14.2.1 SIG GROUP AG
- 14.2.2 UFLEX LIMITED
- 14.2.3 ELOPAK ASA
- 14.2.4 GREATVIEW ASEPTIC PACKAGING CO., LTD.
- 14.2.5 NAMPAK LIMITED
- 14.2.6 GOGLIO S.P.A.
- 14.2.7 PRINTPACK, INC.
- 14.2.8 ECOLEAN AB
- 14.2.9 ARAN GROUP
- 14.2.10 DIZAYN PACK
- 14.2.11 POSETSAN AMBALAJ SANAYI VE TICARET A.S.
- 14.2.12 LAMIPAK
- 14.2.13 POLYOAK PACKAGING
- 14.2.14 AMERICAN PACKAGING CORPORATION
- 14.2.15 HANSIN PACKING
15 RESEARCH METHODOLOGY
- 15.1 RESEARCH DATA
- 15.2 SECONDARY DATA
- 15.2.1 KEY DATA FROM SECONDARY SOURCES
- 15.3 PRIMARY DATA
- 15.3.1 KEY DATA FROM PRIMARY SOURCES
- 15.3.2 KEY INDUSTRY INSIGHTS
- 15.3.3 BREAKDOWN OF INTERVIEWS WITH EXPERTS
- 15.4 MARKET SIZE ESTIMATION
- 15.5 GROWTH FORECAST
- 15.6 DATA TRIANGULATION
- 15.7 RESEARCH ASSUMPTIONS
- 15.8 RISK ASSESSMENT
- 15.9 FACTOR ANALYSIS
- 15.10 RESEARCH LIMITATIONS
16 APPENDIX
- 16.1 DISCUSSION GUIDE
- 16.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 16.3 CUSTOMIZATION OPTIONS
- 16.4 RELATED REPORTS
- 16.5 AUTHOR DETAILS
List of Tables
- TABLE 1 INTERCONNECTED MARKETS
- TABLE 2 CROSS- SECTOR OPPORTUNITIES
- TABLE 3 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS: KEY MOVES AND STRATEGIC FOCUS
- TABLE 4 PORTER'S FIVE FORCES ANALYSIS
- TABLE 5 WORLD REAL GDP (ANNUAL PERCENTAGE CHANGE) OF DIFFERENT REGIONS, 2024-2026
- TABLE 6 WORLD REAL GDP (ANNUAL PERCENTAGE CHANGE) OF TOP COUNTRIES, 2024-2026
- TABLE 7 ROLES OF COMPANIES IN ASEPTIC PACKAGING ECOSYSTEM
- TABLE 8 AVERAGE SELLING PRICE TREND OF ASEPTIC PACKAGING OFFERED BY KEY PLAYERS, BY APPLICATION, 2025 (USD/TONS)
- TABLE 9 AVERAGE SELLING PRICE TREND OF ASEPTIC PACKAGING, BY REGION, 2022-2025 (USD/TONS)
- TABLE 10 EXPORT DATA FOR HS CODE 392310, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 11 IMPORT DATA FOR HS CODE 392310, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 12 EXPORT DATA FOR HS CODE 4819, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 13 IMPORT DATA FOR HS CODE 4819, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 14 ASEPTIC PACKAGING: KEY CONFERENCES AND EVENTS, 2026-2027
- TABLE 15 US TARIFF TABLE - ASEPTIC PACKAGING (HTS 4811.59/4819.20)
- TABLE 16 END-USE INDUSTRY IMPACT
- TABLE 17 KEY PATENTS, 2025
- TABLE 18 TOP USE CASES AND MARKET POTENTIAL
- TABLE 19 BEST PRACTICES: COMPANIES IMPLEMENTING USE CASES
- TABLE 20 ASEPTIC PACKAGING MARKET: CASE STUDIES RELATED TO GEN AI IMPLEMENTATION
- TABLE 21 NORTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 22 EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 23 ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 24 SOUTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 25 MIDDLE EAST & AFRICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 26 GLOBAL INDUSTRY STANDARDS IN ASEPTIC PACKAGING MARKET
- TABLE 27 CERTIFICATIONS, LABELING, ECO-STANDARDS IN ASEPTIC PACKAGING MARKET
- TABLE 28 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP 3 APPLICATIONS
- TABLE 29 KEY BUYING CRITERIA FOR TOP 3 APPLICATIONS
- TABLE 30 UNMET NEEDS IN ASEPTIC PACKAGING MARKET BY APPLICATIONS
- TABLE 31 ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 32 ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 33 ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 34 ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 35 ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 36 ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 37 ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 38 ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 39 ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 40 ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 41 ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 42 ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 43 ASEPTIC PACKAGING MARKET, BY REGION, 2022-2024 (USD MILLION)
- TABLE 44 ASEPTIC PACKAGING MARKET, BY REGION, 2025-2031 (USD MILLION)
- TABLE 45 ASEPTIC PACKAGING MARKET, BY REGION, 2022-2024 (BILLION UNITS)
- TABLE 46 ASEPTIC PACKAGING MARKET, BY REGION, 2025-2031 (BILLION UNITS)
- TABLE 47 ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2022-2024 (USD MILLION)
- TABLE 48 ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2025-2031 (USD MILLION)
- TABLE 49 ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2022-2024 (BILLION UNITS)
- TABLE 50 ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2025-2031 (BILLION UNITS)
- TABLE 51 ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 52 ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 53 ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 54 ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 55 ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 56 ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 57 ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 58 ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 59 ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 60 ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 61 ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 62 ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 63 CHINA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 64 CHINA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 65 CHINA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 66 CHINA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 67 CHINA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 68 CHINA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 69 CHINA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 70 CHINA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 71 CHINA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 72 CHINA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 73 CHINA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 74 CHINA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 75 INDIA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 76 INDIA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 77 INDIA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 78 INDIA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 79 INDIA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 80 INDIA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 81 INDIA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 82 INDIA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 83 INDIA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 84 INDIA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 85 INDIA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 86 INDIA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 87 JAPAN: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 88 JAPAN: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 89 JAPAN: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 90 JAPAN: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 91 JAPAN: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 92 JAPAN: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 93 JAPAN: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 94 JAPAN: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 95 JAPAN: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 96 JAPAN: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 97 JAPAN: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 98 JAPAN: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 99 SOUTH KOREA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 100 SOUTH KOREA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 101 SOUTH KOREA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 102 SOUTH KOREA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 103 SOUTH KOREA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 104 SOUTH KOREA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 105 SOUTH KOREA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 106 SOUTH KOREA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 107 SOUTH KOREA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 108 SOUTH KOREA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 109 SOUTH KOREA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 110 SOUTH KOREA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 111 AUSTRALIA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 112 AUSTRALIA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 113 AUSTRALIA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 114 AUSTRALIA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 115 AUSTRALIA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 116 AUSTRALIA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 117 AUSTRALIA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 118 AUSTRALIA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 119 AUSTRALIA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 120 AUSTRALIA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 121 AUSTRALIA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 122 AUSTRALIA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 123 REST OF ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 124 REST OF ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 125 REST OF ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 126 REST OF ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 127 REST OF ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 128 REST OF ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 129 REST OF ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 130 REST OF ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 131 REST OF ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 132 REST OF ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 133 REST OF ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 134 REST OF ASIA PACIFIC: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 135 NORTH AMERICA: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2022-2024 (USD MILLION)
- TABLE 136 NORTH AMERICA: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2025-2031 (USD MILLION)
- TABLE 137 NORTH AMERICA: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2022-2024 (BILLION UNITS)
- TABLE 138 NORTH AMERICA: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2025-2031 (BILLION UNITS)
- TABLE 139 NORTH AMERICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 140 NORTH AMERICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 141 NORTH AMERICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 142 NORTH AMERICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 143 NORTH AMERICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 144 NORTH AMERICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 145 NORTH AMERICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 146 NORTH AMERICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 147 NORTH AMERICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 148 NORTH AMERICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 149 NORTH AMERICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 150 NORTH AMERICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 151 US: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 152 US: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 153 US: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 154 US: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 155 US: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 156 US: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 157 US: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 158 US: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 159 US: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 160 US: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 161 US: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 162 US: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 163 CANADA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 164 CANADA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 165 CANADA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 166 CANADA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 167 CANADA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 168 CANADA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 169 CANADA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 170 CANADA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 171 CANADA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 172 CANADA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 173 CANADA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 174 CANADA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 175 MEXICO: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 176 MEXICO: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 177 MEXICO: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 178 MEXICO: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 179 MEXICO: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 180 MEXICO: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 181 MEXICO: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 182 MEXICO: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 183 MEXICO: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 184 MEXICO: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 185 MEXICO: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 186 MEXICO: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 187 EUROPE: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2022-2024 (USD MILLION)
- TABLE 188 EUROPE: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2025-2031 (USD MILLION)
- TABLE 189 EUROPE: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2022-2024 (BILLION UNITS)
- TABLE 190 EUROPE: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2025-2031 (BILLION UNITS)
- TABLE 191 EUROPE: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 192 EUROPE: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 193 EUROPE: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 194 EUROPE: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 195 EUROPE: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 196 EUROPE: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 197 EUROPE: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 198 EUROPE: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 199 EUROPE: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 200 EUROPE: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 201 EUROPE: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 202 EUROPE: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 203 GERMANY: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 204 GERMANY: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 205 GERMANY: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 206 GERMANY: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 207 GERMANY: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 208 GERMANY: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 209 GERMANY: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 210 GERMANY: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 211 GERMANY: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 212 GERMANY: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 213 GERMANY: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 214 GERMANY: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 215 UK: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 216 UK: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 217 UK: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 218 UK: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 219 UK: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 220 UK: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 221 UK: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 222 UK: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 223 UK: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 224 UK: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 225 UK: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 226 UK: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 227 FRANCE: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 228 FRANCE: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 229 FRANCE: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 230 FRANCE: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 231 FRANCE: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 232 FRANCE: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 233 FRANCE: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 234 FRANCE: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 235 FRANCE: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 236 FRANCE: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 237 FRANCE: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 238 FRANCE: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 239 SPAIN: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 240 SPAIN: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 241 SPAIN: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 242 SPAIN: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 243 SPAIN: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 244 SPAIN: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 245 SPAIN: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 246 SPAIN: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 247 SPAIN: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 248 SPAIN: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 249 SPAIN: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 250 SPAIN: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 251 ITALY: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 252 ITALY: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 253 ITALY: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 254 ITALY: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 255 ITALY: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 256 ITALY: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 257 ITALY: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 258 ITALY: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 259 ITALY: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 260 ITALY: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 261 ITALY: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 262 ITALY: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 263 REST OF EUROPE: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 264 REST OF EUROPE: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 265 REST OF EUROPE: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 266 REST OF EUROPE: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 267 REST OF EUROPE: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 268 REST OF EUROPE: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 269 REST OF EUROPE: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 270 REST OF EUROPE: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 271 REST OF EUROPE: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 272 REST OF EUROPE: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 273 REST OF EUROPE: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 274 REST OF EUROPE: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 275 MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2022-2024 (USD MILLION)
- TABLE 276 MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2025-2031 (USD MILLION)
- TABLE 277 MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2022-2024 (BILLION UNITS)
- TABLE 278 MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2025-2031 (BILLION UNITS)
- TABLE 279 MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 280 MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 281 MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 282 MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 283 MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 284 MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 285 MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 286 MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 287 MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 288 MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 289 MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 290 MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 291 GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 292 GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 293 GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 294 GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 295 GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 296 GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 297 GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 298 GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 299 GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 300 GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 301 GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 302 GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 303 SAUDI ARABIA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 304 SAUDI ARABIA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 305 SAUDI ARABIA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 306 SAUDI ARABIA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 307 SAUDI ARABIA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 308 SAUDI ARABIA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 309 SAUDI ARABIA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 310 SAUDI ARABIA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 311 SAUDI ARABIA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 312 SAUDI ARABIA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 313 SAUDI ARABIA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 314 SAUDI ARABIA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 315 UAE: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 316 UAE: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 317 UAE: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 318 UAE: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 319 UAE: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 320 UAE: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 321 UAE: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 322 UAE: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 323 UAE: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 324 UAE: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 325 UAE: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 326 UAE: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 327 REST OF GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 328 REST OF GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 329 REST OF GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 330 REST OF GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 331 REST OF GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 332 REST OF GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 333 REST OF GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 334 REST OF GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 335 REST OF GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 336 REST OF GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 337 REST OF GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 338 REST OF GCC COUNTRIES: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 339 SOUTH AFRICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 340 SOUTH AFRICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 341 SOUTH AFRICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 342 SOUTH AFRICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 343 SOUTH AFRICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 344 SOUTH AFRICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 345 SOUTH AFRICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 346 SOUTH AFRICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 347 SOUTH AFRICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 348 SOUTH AFRICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 349 SOUTH AFRICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 350 SOUTH AFRICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 351 REST OF MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 352 REST OF MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 353 REST OF MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 354 REST OF MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 355 REST OF MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 356 REST OF MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 357 REST OF MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 358 REST OF MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 359 REST OF MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 360 REST OF MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 361 REST OF MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 362 REST OF MIDDLE EAST & AFRICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 363 SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2022-2024 (USD MILLION)
- TABLE 364 SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2025-2031 (USD MILLION)
- TABLE 365 SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2022-2024 (BILLION UNITS)
- TABLE 366 SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY COUNTRY, 2025-2031 (BILLION UNITS)
- TABLE 367 SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 368 SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 369 SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 370 SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 371 SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 372 SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 373 SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 374 SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 375 SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 376 SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 377 SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 378 SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 379 BRAZIL: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 380 BRAZIL: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 381 BRAZIL: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 382 BRAZIL: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 383 BRAZIL: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 384 BRAZIL: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 385 BRAZIL: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 386 BRAZIL: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 387 BRAZIL: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 388 BRAZIL: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 389 BRAZIL: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 390 BRAZIL: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 391 ARGENTINA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 392 ARGENTINA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 393 ARGENTINA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 394 ARGENTINA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 395 ARGENTINA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 396 ARGENTINA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 397 ARGENTINA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 398 ARGENTINA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 399 ARGENTINA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 400 ARGENTINA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 401 ARGENTINA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 402 ARGENTINA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 403 REST OF SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (USD MILLION)
- TABLE 404 REST OF SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (USD MILLION)
- TABLE 405 REST OF SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2022-2024 (BILLION UNITS)
- TABLE 406 REST OF SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY MATERIAL, 2025-2031 (BILLION UNITS)
- TABLE 407 REST OF SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (USD MILLION)
- TABLE 408 REST OF SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (USD MILLION)
- TABLE 409 REST OF SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2022-2024 (BILLION UNITS)
- TABLE 410 REST OF SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY TYPE, 2025-2031 (BILLION UNITS)
- TABLE 411 REST OF SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (USD MILLION)
- TABLE 412 REST OF SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 413 REST OF SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2022-2024 (BILLION UNITS)
- TABLE 414 REST OF SOUTH AMERICA: ASEPTIC PACKAGING MARKET, BY APPLICATION, 2025-2031 (BILLION UNITS)
- TABLE 415 ASEPTIC PACKAGING MARKET: OVERVIEW OF STRATEGIES ADOPTED BY MARKET PLAYERS, JANUARY 2024-JULY 2026
- TABLE 416 ASEPTIC PACKAGING: DEGREE OF COMPETITION
- TABLE 417 ASEPTIC PACKAGING MARKET: REGION FOOTPRINT
- TABLE 418 ASEPTIC PACKAGING MARKET: MATERIAL FOOTPRINT
- TABLE 419 ASEPTIC PACKAGING MARKET: TYPE FOOTPRINT
- TABLE 420 ASEPTIC PACKAGING MARKET: APPLICATION FOOTPRINT
- TABLE 421 ASEPTIC PACKAGING MARKET: KEY STARTUPS/SMES
- TABLE 422 ASEPTIC PACKAGING MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- TABLE 423 ASEPTIC PACKAGING MARKET: PRODUCT LAUNCHES, JANUARY 2024- JULY 2026
- TABLE 424 ASEPTIC PACKAGING MARKET: DEALS, JANUARY 2024- JULY 2026
- TABLE 425 ASEPTIC PACKAGING MARKET: EXPANSIONS, JANUARY 2024- JULY 2026
- TABLE 426 TABLE 8 ASEPTIC PACKAGING: OTHER DEVELOPMENTS, JANUARY 2024-JULY 2026
- TABLE 427 AMCOR PLC: COMPANY OVERVIEW
- TABLE 428 AMCOR PLC: PRODUCTS OFFERED
- TABLE 429 AMCOR PLC: DEALS, JANUARY 2024- JULY 2026
- TABLE 430 AMCOR PLC: EXPANSIONS, JANUARY 2024-JULY 2026
- TABLE 431 TABLE 5 AMCOR PLC.: OTHER DEVELOPMENTS, JANUARY 2024-JULY 2026
- TABLE 432 MONDI PLC: COMPANY OVERVIEW
- TABLE 433 MONDI PLC: PRODUCTS OFFERED
- TABLE 434 MONDI PLC: PRODUCT LAUNCHES, JANUARY 2024-JULY 2026
- TABLE 435 SMURFIT WESTROCK PLC: COMPANY OVERVIEW
- TABLE 436 SMURFIT WESTROCK PLC: PRODUCTS OFFERED
- TABLE 437 SMURFIT WESTROCK PLC: DEALS, JANUARY 2024- JULY 2026
- TABLE 438 SMURFIT WESTROCK PLC: EXPANSIONS, JANUARY 2024-JULY 2026
- TABLE 439 SMURFIT WESTROCK PLC.: OTHER DEVELOPMENTS, JANUARY 2024-JULY 2026
- TABLE 440 TOPPAN HOLDINGS INC.: COMPANY OVERVIEW
- TABLE 441 TOPPAN HOLDINGS INC.: PRODUCTS OFFERED
- TABLE 442 TOPPAN HOLDINGS INC.: PRODUCT LAUNCHES, JANUARY 2024-JULY 2026
- TABLE 443 TOPPAN HOLDINGS INC.: DEALS, JANUARY 2024- JULY 2026
- TABLE 444 TOPPAN HOLDINGS INC.: EXPANSIONS, JANUARY 2024-JULY 2026
- TABLE 445 GRAPHIC PACKAGING HOLDING COMPANY: COMPANY OVERVIEW
- TABLE 446 GRAPHIC PACKAGING HOLDING COMPANY: PRODUCTS OFFERED
- TABLE 447 GRAPHIC PACKAGING HOLDING COMPANY: PRODUCT LAUNCHES, JANUARY 2024-JULY 2026
- TABLE 448 GRAPHIC PACKAGING HOLDING COMPANY: DEALS, JANUARY 2024- JULY 2026
- TABLE 449 GRAPHIC PACKAGING HOLDING COMPANY: EXPANSIONS, JANUARY 2024-JULY 2026
- TABLE 450 NIPPON PAPER INDUSTRIES CO., LTD.: COMPANY OVERVIEW
- TABLE 451 NIPPON PAPER INDUSTRIES CO., LTD.: PRODUCTS OFFERED
- TABLE 452 NIPPON PAPER INDUSTRIES CO., LTD.: PRODUCT LAUNCHES, JANUARY 2024-JULY 2026
- TABLE 453 DAI NIPPON PRINTING CO., LTD. (DNP): COMPANY OVERVIEW
- TABLE 454 DAI NIPPON PRINTING CO., LTD. (DNP): PRODUCTS OFFERED
- TABLE 455 DAI NIPPON PRINTING CO., LTD. (DNP): PRODUCT LAUNCHES, JANUARY 2024-JULY 2026
- TABLE 456 DAI NIPPON PRINTING CO., LTD. (DNP): DEALS, JANUARY 2024- JULY 2026
- TABLE 457 DAI NIPPON PRINTING CO., LTD. (DNP): EXPANSIONS, JANUARY 2024-JULY 2026
- TABLE 458 HUHTAMAKI OYJ: COMPANY OVERVIEW
- TABLE 459 HUHTAMAKI OYJ: PRODUCTS OFFERED
- TABLE 460 HUHTAMAKI OYJ: PRODUCT LAUNCHES, JANUARY 2024-JULY 2026
- TABLE 461 HUHTAMAKI OYJ: DEALS, JANUARY 2024- JULY 2026
- TABLE 462 HUHTAMAKI OYJ: EXPANSIONS, JANUARY 2024-JULY 2026
- TABLE 463 STORA ENSO OYJ: COMPANY OVERVIEW
- TABLE 464 STORA ENSO OYJ: PRODUCTS OFFERED
- TABLE 465 STORA ENSO OYJ: PRODUCT LAUNCHES, JANUARY 2024-JULY 2026
- TABLE 466 STORA ENSO OYJ: DEALS, JANUARY 2024- JULY 2026
- TABLE 467 STORA ENSO OYJ: EXPANSIONS, JANUARY 2024-JULY 2026
- TABLE 468 TETRA PAK INTERNATIONAL S.A.: COMPANY OVERVIEW
- TABLE 469 TETRA PAK INTERNATIONAL S.A.: PRODUCTS OFFERED
- TABLE 470 TETRA PAK INTERNATIONAL S.A.: PRODUCT LAUNCHES, JANUARY 2024-JULY 2026
- TABLE 471 TETRA PAK INTERNATIONAL S.A.: DEALS, JANUARY 2024- JULY 2026
- TABLE 472 TETRA PAK INTERNATIONAL S.A.: EXPANSIONS, JANUARY 2024-JULY 2026
- TABLE 473 SIG GROUP AG: COMPANY OVERVIEW
- TABLE 474 UFLEX LIMITED: COMPANY OVERVIEW
- TABLE 475 ELOPAK ASA: COMPANY OVERVIEW
- TABLE 476 GREATVIEW ASEPTIC PACKAGING CO., LTD.: COMPANY OVERVIEW
- TABLE 477 NAMPAK LIMITED: COMPANY OVERVIEW
- TABLE 478 GOGLIO S.P.A.: COMPANY OVERVIEW
- TABLE 479 PRINTPACK, INC.: COMPANY OVERVIEW
- TABLE 480 ECOLEAN AB: COMPANY OVERVIEW
- TABLE 481 ARAN GROUP: COMPANY OVERVIEW
- TABLE 482 DIZAYN PACK: COMPANY OVERVIEW
- TABLE 483 POSETSAN AMBALAJ SANAYI VE TICARET A.S.: COMPANY OVERVIEW
- TABLE 484 LAMIPAK: COMPANY OVERVIEW
- TABLE 485 POLYOAK PACKAGING: COMPANY OVERVIEW
- TABLE 486 AMERICAN PACKAGING CORPORATION: COMPANY OVERVIEW
- TABLE 487 HANSIN PACKING: COMPANY OVERVIEW
List of Figures
- FIGURE 1 ASEPTIC PACKAGING MARKET: SEGMENTATION & REGIONAL SCOPE
- FIGURE 2 KEY INSIGHTS AND MARKET HIGHLIGHTS
- FIGURE 3 GLOBAL ASEPTIC PACKAGING MARKET, 2022-2031
- FIGURE 4 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN ASEPTIC PACKAGING MARKET (2021-2025)
- FIGURE 5 DISRUPTIVE TRENDS IMPACTING THE GROWTH OF ASEPTIC PACKAGING MARKET DURING THE FORECAST PERIOD
- FIGURE 6 HIGH-GROWTH SEGMENTS AND EMERGING FRONTIERS IN THE ASEPTIC PACKAGING MARKET, 2026-2031
- FIGURE 7 ASIA PACIFIC TO BE THE LARGEST MARKET DURING FORECAST PERIOD
- FIGURE 8 HIGH DEMAND FOR ASEPTIC PACKAGING TO CREATE LUCRATIVE OPPORTUNITIES FOR MARKET PLAYERS
- FIGURE 9 PAPER & PAPERBOARD SEGMENT & CARTONS SEGMENT ACCOUNTED FOR LARGEST MARKET SHARES IN 2025
- FIGURE 10 PHARMACEUTICALS SEGMENT DOMINATED ASEPTIC PACKAGING MARKET IN 2025
- FIGURE 11 INDIA TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 12 ASEPTIC PACKAGING MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 13 GLOBAL SUPPLY CHAIN WASTE COST BREAKDOWN, 2026 (USD BILLION)
- FIGURE 14 ASEPTIC PACKAGING MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 15 ASEPTIC PACKAGING VALUE CHAIN
- FIGURE 16 ASEPTIC PACKAGING ECOSYSTEM
- FIGURE 17 AVERAGE SELLING PRICE TREND OF ASEPTIC PACKAGING OFFERED BY KEY PLAYERS, BY APPLICATION, 2025
- FIGURE 18 AVERAGE SELLING PRICE TREND OF ASEPTIC PACKAGING, BY REGION, 2022-2025
- FIGURE 19 EXPORT DATA FOR HS CODE 392310, BY COUNTRY, 2021-2025 (USD THOUSAND)
- FIGURE 20 IMPORT DATA FOR HS CODE 392310, BY COUNTRY, 2021-2025 (USD THOUSAND)
- FIGURE 21 EXPORT DATA FOR HS CODE 4819, BY COUNTRY, 2021-2025 (USD THOUSAND)
- FIGURE 22 IMPORT DATA FOR HS CODE 4819, BY COUNTRY, 2021-2025 (USD THOUSAND)
- FIGURE 23 TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- FIGURE 24 INVESTMENT AND FUNDING SCENARIO, 2021-2025
- FIGURE 25 LIST OF MAJOR PATENTS RELATED TO ASEPTIC PACKAGING, 2016-2025
- FIGURE 26 JURISDICTION OF CHINA REGISTERED HIGHEST PERCENTAGE OF PATENTS, 2016-2025
- FIGURE 27 ASEPTIC PACKAGING MARKET: DECISION-MAKING FACTORS
- FIGURE 28 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP 3 APPLICATIONS
- FIGURE 29 KEY BUYING CRITERIA FOR TOP 3 APPLICATIONS
- FIGURE 30 ADOPTION BARRIERS & INTERNAL CHALLENGES
- FIGURE 31 PAPER & PAPERBOARD SEGMENT TO WITNESS FASTEST GROWTH DURING FORECAST PERIOD
- FIGURE 32 CARTONS SEGMENT TO BE LARGEST TYPE SEGMENT DURING FORECAST PERIOD
- FIGURE 33 BEVERAGES TO BE LARGEST PRODUCT SEGMENT DURING FORECAST PERIOD
- FIGURE 34 INDIA TO BE FASTEST-GROWING MARKET DURING FORECAST PERIOD
- FIGURE 35 ASIA PACIFIC DOMINATED ASEPTIC PACKAGING MARKET IN 2025
- FIGURE 36 ASIA PACIFIC: ASEPTIC PACKAGING MARKET SNAPSHOT
- FIGURE 37 NORTH AMERICA: ASEPTIC PACKAGING MARKET SNAPSHOT
- FIGURE 38 ASEPTIC PACKAGING MARKET: REVENUE ANALYSIS OF KEY PLAYERS, 2021-2025 (USD BILLION)
- FIGURE 39 ASEPTIC PACKAGING MARKET SHARE ANALYSIS, 2025
- FIGURE 40 ASEPTIC PACKAGING MARKET: BRAND COMPARISON
- FIGURE 41 ASEPTIC PACKAGING MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 42 ASEPTIC PACKAGING MARKET: COMPANY FOOTPRINT, 2026
- FIGURE 43 ASEPTIC PACKAGING MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 44 COMPANY VALUATION (USD BILLION), 2026
- FIGURE 45 FINANCIAL METRICS: EV/EBITDA RATIO, 2026
- FIGURE 46 YEAR-TO-DATE PRICE AND FIVE-YEAR STOCK BETA, 2026
- FIGURE 47 AMCOR PLC: COMPANY SNAPSHOT
- FIGURE 48 MONDI PLC: COMPANY SNAPSHOT
- FIGURE 49 SMURFIT WESTROCK PLC: COMPANY SNAPSHOT
- FIGURE 50 TOPPAN HOLDINGS INC.: COMPANY SNAPSHOT
- FIGURE 51 GRAPHIC PACKAGING HOLDING COMPANY: COMPANY SNAPSHOT
- FIGURE 52 NIPPON PAPER INDUSTRIES CO., LTD.: COMPANY SNAPSHOT
- FIGURE 53 DAI NIPPON PRINTING CO., LTD. (DNP): COMPANY SNAPSHOT
- FIGURE 54 HUHTAMAKI OYJ: COMPANY SNAPSHOT
- FIGURE 55 STORA ENSO OYJ: COMPANY SNAPSHOT
- FIGURE 56 ASEPTIC PACKAGING MARKET: RESEARCH DESIGN
- FIGURE 57 MARKET SIZE ESTIMATION: BOTTOM-UP APPROACH
- FIGURE 58 MARKET SIZE ESTIMATION: TOP-DOWN APPROACH
- FIGURE 59 MARKET SIZE ESTIMATION: SUPPLY SIDE
- FIGURE 60 ASEPTIC PACKAGING MARKET: DATA TRIANGULATION

