PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2063778

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2063778
Malaysia Folding Carton - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the malaysia folding carton market size is projected to expand from USD 481.04 million in 2025 and USD 506.91 million in 2026 to USD 662.94 million by 2031, registering a CAGR of 5.51% between 2026 to 2031.
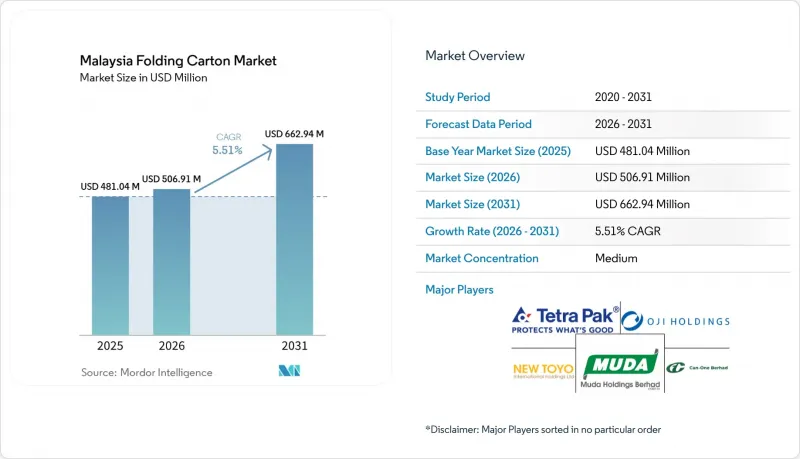
This report is Segmented by Material Type (Solid Bleached Sulfate, Folding Boxboard, Coated Unbleached Kraft, and More), Printing Technology (Lithographic, Flexographic, Digital, Gravure, and More), End-User Industry (Food and Beverage, Healthcare/Pharmaceuticals, Personal Care and Cosmetics, Electrical and Electronics, and More). The Market Forecasts are Provided in Terms of Value (USD).
Malaysia Folding Carton Market Trends and Insights
Growing Adoption of Premium Packaged Goods
Demand for premium cosmetics, confectionery, and healthcare SKUs is reshaping substrate specifications as brand owners insist on cartons that accept embossing, metallic inks, and tactile varnishes. Nestle Malaysia's ready-to-drink KitKat beverages and portable Maggi bowls exemplify the shift toward grease-resistant coatings that preserve brand imagery under high-speed filling lines. Urban consumers, 60-70% of survey respondents, now favor brands that publish recyclability information, even when price sensitivity remains high. Solid bleached sulfate board, priced at a 15-20% premium to folding boxboard, is therefore holding share in luxury goods despite cost headwinds. The Ministry of Domestic Trade's 2026 advertising code compels clear labeling of recyclability, accelerating the exit of non-certified converters. Collectively, prestige positioning and regulatory nudges are expanding the value pool available to converters capable of delivering high-definition graphics on certified substrates, reinforcing upward momentum in the Malaysian folding carton market.
Government Push for Sustainable Packaging Standards
Malaysia's Circular Economy Blueprint 2025-2035 transitions from voluntary to mandatory extended producer responsibility by 2030, requiring converters to track sourcing, energy intensity, and recycling outcomes, or face MYR 50,000 (USD 12,337) in fines per violation. Lazada and Shopee magnified the pressure by levying a 3% surcharge on non-compliant packaging starting July 2026, instantly raising the entry bar for uncertified suppliers. Box-Pak Malaysia pre-empted the rule change by certifying chain-of-custody systems across three countries, giving the group pole position for multinational FMCG tenders. Ink sludge re-classification under the 2025 scheduled-waste rules is further motivating investments in closed-loop water treatment. In combination, these measures channel volume toward large, well-capitalized firms and cement sustainability as a non-negotiable qualifier within the Malaysian folding carton market.
Volatile Recovered Paper Import Prices
Mixed-paper grades traded between USD 180 and USD 260 per tonne in 2025, a 44% spread that erased 3-5 percentage-point margins for converters locked into quarterly contracts. U.S. shipments to Southeast Asia fell from 1.8 million tonnes in 2023 to 1.2 million tonnes in 2025 as domestic mills hoarded fiber. Spot OCC prices spiked 28% in Q1 2025 before retreating, complicating inventory valuation for converters on 60-day terms. While Jingxing's new mill eases virgin-fiber tightness, most white-lined chipboard still relies on imported recovered paper. Until additional domestic furnish arrives, price turbulence will continue to cap upside in the Malaysia folding carton market.
Other drivers and restraints analyzed in the detailed report include:
- Surge in Quick-Commerce Grocery Delivery
- Capacity Expansion by Domestic Paper Mills
- Shortage of Skilled Press Operators
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Folding boxboard retained 41.71% of Malaysia's folding carton market share in 2025 on the back of its stiffness and print fidelity for branded food, pharma, and cosmetic lines. Yet white-lined chipboard, built from 100% recycled fiber, is on track for a 6.41% CAGR as cost-conscious household-goods brands and e-commerce shippers embrace its 20-25% unit-price advantage. The Malaysian folding carton market for white-lined chipboard is poised to expand sharply once Nextgreen IOI's palm-fiber pulp is blended into grades that comply with ISO 22002-4:2025 migration norms. Solid bleached sulfate remains the substrate of choice for prestige cosmetics, sustaining premium positioning even though import dependency from Scandinavia and North America inflates landed cost. Coated unbleached kraft is capturing ambient grocery items where its natural brown look aligns with sustainability messaging and trims freight weight by up to 10%. Hybrid micro-flute laminates, although niche, are carving a share in electronics where drop resistance trumps price.
Converters are mixing virgin and recycled furnish to hit brand-mandated barriers on odor, migration, and brightness while juggling cost. Lazada's 2026 FSC-certification rule cements recycled-content demand but simultaneously weeds out mills lacking chain-of-custody audits, concentrating volume with ISO 14001 holders. Over the forecast window, domestic pulp additions should narrow the cost gap between folding boxboard and white-lined chipboard, softening the latter's price edge yet cementing recycled substrates as the structural growth engine of the Malaysian folding carton market.
List of Companies Covered in this Report:
- Muda Holdings Berhad
- Oji Holdings Corporation
- Can-One Berhad
- Tetra Pak Malaysia Sdn Bhd
- New Toyo International Holdings Ltd
- Orient Press Sdn Bhd
- KYM Holdings Berhad
- Ornapaper Industry (M) Sdn Bhd
- Rengo Co., Ltd.
- Tat Seng Packaging Group Ltd
- Kian Joo Can Factory Berhad
- Box-Pak (Malaysia) Bhd
- Lamipak (Malaysia) Sdn Bhd
- Paper-Based Packaging Sdn Bhd
- Mondi plc
- SCG Packaging Public Company Limited
- Hexachase Packaging Sdn Bhd
- Printpack Asia Sdn Bhd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Adoption of Premium Packaged Goods
- 4.2.2 Government Push for Sustainable Packaging Standards
- 4.2.3 Surge in Quick-Commerce Grocery Delivery
- 4.2.4 Capacity Expansion by Domestic Paper Mills
- 4.2.5 AI-Enabled Quality Inspection Systems
- 4.2.6 Near-Shoring of Regional Consumer-Goods Production
- 4.3 Market Restraints
- 4.3.1 Volatile Recovered Paper Import Prices
- 4.3.2 Shortage of Skilled Press Operators
- 4.3.3 Rising Popularity of Flexible Pouches for Beverage
- 4.3.4 Logistic Bottlenecks at Port Klang
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Solid Bleached Sulfate
- 5.1.2 Folding Boxboard
- 5.1.3 Coated Unbleached Kraft
- 5.1.4 White Line Chipboard
- 5.1.5 Other Material Types
- 5.2 By Printing Technology
- 5.2.1 Lithographic Printing
- 5.2.2 Flexographic Printing
- 5.2.3 Digital Printing
- 5.2.4 Gravure Printing
- 5.2.5 Other Printing Technologies
- 5.3 By End-User Industry
- 5.3.1 Food and Beverage
- 5.3.2 Healthcare/Pharmaceuticals
- 5.3.3 Personal Care and Cosmetics
- 5.3.4 Electrical and Electronics
- 5.3.5 Household and Industrial Goods
- 5.3.6 Tobacco
- 5.3.7 E-Commerce and Retail-Ready Packaging
- 5.3.8 Other End-User Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Muda Holdings Berhad
- 6.4.2 Oji Holdings Corporation
- 6.4.3 Can-One Berhad
- 6.4.4 Tetra Pak Malaysia Sdn Bhd
- 6.4.5 New Toyo International Holdings Ltd
- 6.4.6 Orient Press Sdn Bhd
- 6.4.7 KYM Holdings Berhad
- 6.4.8 Ornapaper Industry (M) Sdn Bhd
- 6.4.9 Rengo Co., Ltd.
- 6.4.10 Tat Seng Packaging Group Ltd
- 6.4.11 Kian Joo Can Factory Berhad
- 6.4.12 Box-Pak (Malaysia) Bhd
- 6.4.13 Lamipak (Malaysia) Sdn Bhd
- 6.4.14 Paper-Based Packaging Sdn Bhd
- 6.4.15 Mondi plc
- 6.4.16 SCG Packaging Public Company Limited
- 6.4.17 Hexachase Packaging Sdn Bhd
- 6.4.18 Printpack Asia Sdn Bhd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

