PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117507

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117507
Medical and Pharmaceutical Static Sealing Solutions - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the medical and pharmaceutical static sealing solutions market is expected to grow from USD 224.03 million in 2025 to reach USD 233.52 million in 2026 and is forecasted to reach USD 291.39 million by 2031, growing at a CAGR of 4.53% from 2026 to 2031.
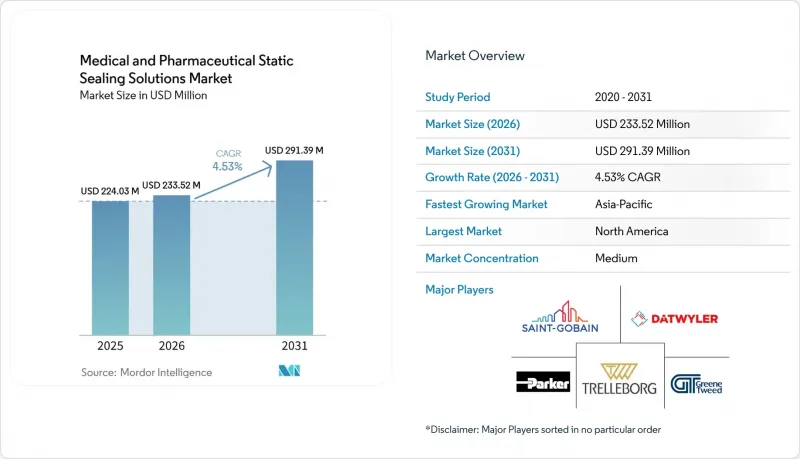
This report is Segmented by Material (Elastomers, Silicone, and Others), Product Type (O-Rings, Gaskets, and Others), Application (Processing Equipment, and Others), End-User (Pharmaceutical Manufacturing Plants, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Medical and Pharmaceutical Static Sealing Solutions Market Trends and Insights
Rising Biologics, Biosimilars, and Sterile Drug Output
The shift toward biologic therapies is changing sealing requirements across the medical and pharmaceutical static sealing solutions market, because these products need tighter control over purity, compatibility, and process stability. Each new biologic or biosimilar line adds many validated sealing points across upstream bioreactors, downstream purification trains, and aseptic filling systems, which raises total component demand beyond the installed equipment count. Drug substances such as monoclonal antibodies, recombinant proteins, and cell-based therapies are more sensitive to trace leachables, so standard industrial materials are less suitable in these settings. Biosimilar facilities also need to mirror reference product manufacturing conditions more closely, which expands the number of qualified seals that must be documented at the process level. The United States had more than 60 biosimilar approvals through mid 2025, which supports broader manufacturing activity tied to validated container closure and process sealing frameworks.This pattern benefits suppliers in the medical and pharmaceutical static sealing solutions market that already hold application matched libraries and supporting documentation, rather than suppliers that compete mainly on volume pricing.
Tightened Extractables and Leachables Qualification Expectations
Extractables and leachables rules have become a stronger growth force in the medical and pharmaceutical static sealing solutions market, because qualification is moving from simple material acceptance toward full system performance review. USP General Chapter <382> became an official requirement on December 1, 2025, and it places more attention on the assembled elastomeric sealing system rather than only the individual material grade. That change means historical USP Class VI data is no longer enough by itself for many regulated applications, and manufacturers now need additional testing for products already in use. The ICH Q3E Guideline for Extractables and Leachables, endorsed in August 2025 and published by the FDA in December 2025, adds harmonized risk based expectations across regulators and reinforces the same direction of travel.As a result, the medical and pharmaceutical static sealing solutions market is seeing stronger pull toward suppliers that can provide pre validated components, deeper dossiers, and faster support for qualification packages. This also narrows the qualified supplier pool, because smaller participants often struggle to sustain repeated testing and documentation updates across multiple product families.
Long Validation and Requalification Cycles Delay New Product Adoption
Long validation timelines remain one of the clearest limits on faster expansion in the medical and pharmaceutical static sealing solutions market, because new components must move through several layers of technical and regulatory review. Qualification can run from material selection through extractables work, biocompatibility review, functional assessment, and stability testing before a seal is accepted for a regulated product or process. When testing frameworks are updated, legacy data often cannot be carried forward without more work, which means even unchanged materials may need fresh studies before continued use. Smaller biopharma firms and many CDMOs are affected more sharply, because they often have less internal quality capacity to run several qualification programs at the same time.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Single-Use and Disposable Bioprocess Assemblies
- Growth in CIP, SIP, and High-Validation Maintenance Cycles
- High Cost of Pharma-Grade Polymers, Metals, and Documentation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Elastomers held 51.11% of the medical and pharmaceutical static sealing solutions market share in 2025, and that lead reflected long standing use in cleaning and sterilization heavy production settings. Their position has been built over many years of validated performance in CIP and SIP environments, where repeatability matters more than experimentation with less proven compounds. Silicone is expected to be the fastest growing material, with a 6.18% CAGR through 2031, and that rise is tied to its biocompatibility profile and its fit with sterile processing and single use applications. Platinum cured liquid silicone rubber is gaining traction in bioreactor interfaces and other sensitive contact points, because low particulate behavior and sterilization compatibility support cleaner qualification paths.
Metals, largely in reinforced gasket designs for high pressure process connections, continue to serve a narrower set of conventional line requirements within the medical and pharmaceutical static sealing solutions market. The more important material shift is that scrutiny around fluorocarbon alternatives is making formulation choice more strategic, which raises interest in silicone where qualification risk looks lower over time. In practice, suppliers are strongest when they can offer both material performance and documentation depth, because customers in the medical and pharmaceutical static sealing solutions market are buying the qualification package along with the physical component.
O-rings accounted for 48.27% of product demand in 2025, which kept them at the center of the medical and pharmaceutical static sealing solutions market across vessels, valves, flanged connections, and equipment penetrations. Their geometry is widely standardized, and that reduces design complexity, eases compatibility review, and supports multi supplier benchmarking when manufacturers qualify a line or retrofit an asset. This standardization also helps procurement teams maintain supply continuity without restarting every part of the qualification process when they review alternatives.
Lip seals are expected to be the fastest-growing product type, and the medical and pharmaceutical static sealing solutions market size for this segment is projected to rise at a 5.25% CAGR through 2031. Their growth comes from more precision filling lines, prefilled syringe assemblies, and closed system transfer devices that need functional reliability in compact drug delivery settings. Diaphragms move closely with sterile valve and pump isolation demand in bioprocessing suites, especially where membrane valve volumes rise with integrated process islands. The remaining product group, which includes PTFE seals, high end gaskets, and septum related formats, serves more specialized programs where low extractables and sterilization stability justify higher prices within the medical and pharmaceutical static sealing solutions market.
Complete Report Scope:
- By Material
- Elastomers
- Silicone
- Metals
- Others
- By Product Type
- O-Rings
- Gaskets
- Lip Seals
- Diaphragms
- Others
- By Application
- Processing Equipment
- Bioreactors
- Filling Systems
- Sterile Processing Equipment
- Medical Devices
- Other Applications
- By End-User
- Pharmaceutical Manufacturing Plants
- Biotechnology Companies
- Contract Manufacturing Organizations
- Medical Device Manufacturers
- Other End-Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 40.60% of the medical and pharmaceutical static sealing solutions market share in 2025, which made it the largest regional base for validated static seals in regulated pharmaceutical and bioprocessing applications. The region benefits from a dense mix of biopharmaceutical innovators, contract manufacturers, and large-scale sterile production assets that need qualified sealing across upstream and downstream operations. New fill finish lines, biologics capacity, and upstream bioreactor investments continue to require validated sealing from the first equipment specification stage onward. North America also acts as the earliest procurement response zone when standards change, since suppliers and manufacturers in the region often move first on requalification, change control, and documentation updates.
Europe held the second-largest regional position in 2025, and its demand pattern remains shaped by layered regulatory expectations and a strong installed base in pharmaceutical production. Germany, France, and the United Kingdom anchor most of the established volume, with Germany's contract manufacturing network creating concentrated demand for elastomeric seals used in bioreactor and sterile transfer environments. European buyers also tend to maintain strict attention to container closure integrity and sterile manufacturing performance, which sustains preference for higher specification sealing materials and established suppliers. Italy, Spain, and production sites across Central and Eastern Europe are adding to regional depth as contract manufacturing capacity broadens and more facilities serve cross border pharmaceutical supply chains.
Asia-Pacific is projected to be the fastest-growing regional segment, and the medical and pharmaceutical static sealing solutions market is projected to expand there at a 6.47% CAGR through 2031. China and India are driving most of that momentum through new biosimilar, vaccine, and CDMO capacity that increases demand for qualified static seals across single use and conventional lines. Japan and South Korea remain established manufacturing centers, and Japan's 2025 emphasis on Liveo medical silicone materials for biopharma applications points to continued regional work in compliant formulation development. Middle East and Africa remain smaller in current revenue terms, but healthcare and pharmaceutical capacity investment in the GCC is creating a firmer local base for regulated production support. South America, led by Brazil and Argentina, is also becoming more active as local manufacturers expand domestic supply and increase procurement of validated components for higher quality pharmaceutical output.
- APM Hexseal Corporation
- Apple Rubber Products, Inc.
- Bal Seal Engineering, Inc.
- Datwyler Holding Inc.
- Dichtomatik GmbH
- EagleBurgmann GmbH and Co. KG
- Freudenberg Sealing Technologies GmbH and Co. KG
- Garlock Sealing Technologies LLC
- Greene, Tweed and Co.
- IDEX
- James Walker and Co. Ltd.
- Marco Rubber and Plastics, LLC
- Minnesota Rubber and Plastics, Inc.
- Morgan Advanced Materials plc
- Parker Hannifin
- Precision Associates, Inc.
- Saint-Gobain
- Sealmatic India Pvt. Ltd.
- SKF AB
- Technetics Group
- Trelleborg AB
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Biologics, Biosimilars, and Sterile Drug Output
- 4.2.2 Tightened Extractables and Leachables Qualification Expectations
- 4.2.3 Expansion of Single-Use and Disposable Bioprocess Assemblies
- 4.2.4 Cleanroom Traceability Demand Across Multi-Site Pharma Networks
- 4.2.5 Growth in CIP, SIP, and High-Validation Maintenance Cycles
- 4.2.6 Supplier Qualification Burden Favors Deeply Certified Sealing Partners
- 4.3 Market Restraints
- 4.3.1 Long Validation and Requalification Cycles Delay New Product Adoption
- 4.3.2 High Cost of Pharma-Grade Polymers, Metals, and Documentation
- 4.3.3 Compatibility Gaps with Aggressive Sterilization and Cleaning Regimes
- 4.3.4 Production Fragmentation Across Device Formats Raises Customization Cost
- 4.4 Supply/Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Material
- 5.1.1 Elastomers
- 5.1.2 Silicone
- 5.1.3 Metals
- 5.1.4 Others
- 5.2 By Product Type
- 5.2.1 O-Rings
- 5.2.2 Gaskets
- 5.2.3 Lip Seals
- 5.2.4 Diaphragms
- 5.2.5 Others
- 5.3 By Application
- 5.3.1 Processing Equipment
- 5.3.2 Bioreactors
- 5.3.3 Filling Systems
- 5.3.4 Sterile Processing Equipment
- 5.3.5 Medical Devices
- 5.3.6 Other Applications
- 5.4 By End-User
- 5.4.1 Pharmaceutical Manufacturing Plants
- 5.4.2 Biotechnology Companies
- 5.4.3 Contract Manufacturing Organizations
- 5.4.4 Medical Device Manufacturers
- 5.4.5 Other End-Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, Recent Developments)
- 6.3.1 APM Hexseal Corporation
- 6.3.2 Apple Rubber Products, Inc.
- 6.3.3 Bal Seal Engineering, Inc.
- 6.3.4 Datwyler Holding Inc.
- 6.3.5 Dichtomatik GmbH
- 6.3.6 EagleBurgmann GmbH and Co. KG
- 6.3.7 Freudenberg Sealing Technologies GmbH and Co. KG
- 6.3.8 Garlock Sealing Technologies LLC
- 6.3.9 Greene, Tweed and Co.
- 6.3.10 IDEX Corporation
- 6.3.11 James Walker and Co. Ltd.
- 6.3.12 Marco Rubber and Plastics, LLC
- 6.3.13 Minnesota Rubber and Plastics, Inc.
- 6.3.14 Morgan Advanced Materials plc
- 6.3.15 Parker Hannifin Corporation
- 6.3.16 Precision Associates, Inc.
- 6.3.17 Saint-Gobain S.A.
- 6.3.18 Sealmatic India Pvt. Ltd.
- 6.3.19 SKF AB
- 6.3.20 Technetics Group
- 6.3.21 Trelleborg AB
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

