PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2118193

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2118193
Europe Wheat Seed Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Europe wheat seed treatment market size is projected to grow from USD 1.53 million in 2025 to USD 1.59 million in 2026 and is forecast to reach USD 1.95 million by 2031 at 4.14% CAGR over 2026-2031.
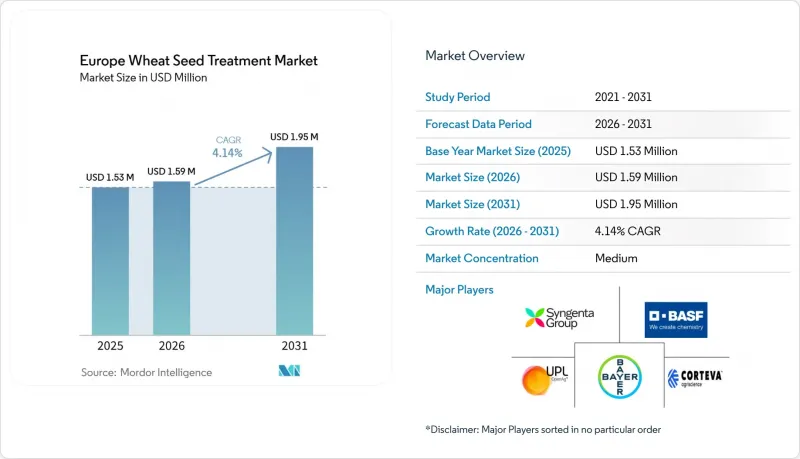
This report is Segmented by Product Type (Insecticides, Fungicides, Nematicides, and More), and by Geography (Germany, United Kingdom, France, Italy, Spain, Russia, and Rest of Europe). The Market Forecasts are Provided in Terms of Value (USD).
Europe Wheat Seed Treatment Market Trends and Insights
Rising Wheat Fungal Disease Pressure
The Europe wheat seed treatment market is seeing firmer demand because fungal pressure has become harder to manage with standard foliar programs alone. Research published in 2025 showed that warm and moist winter conditions in the 2024 season supported early disease development in winter wheat and changed how growers assessed protection needs at sowing. A second 2025 study also reported resistance-breaking stem rust races across multiple European locations, which raised the value of stronger fungicidal protection before crop emergence. This matters because seed treatment helps limit seed-borne and soil-borne infection before in-season spray timing becomes critical. It also supports demand for broader, multi-active combinations that growers view as more dependable in years with unstable disease pressure.
Regulatory Shift Away From High-Risk Chemical Actives
The Europe wheat seed treatment market is also being pushed forward by regulation, even though the same process creates short-term disruption for existing products. The most important recent example is the November 2024 classification of fludioxonil as an endocrine disruptor, which affected a very large share of cereal seed treatment portfolios and brought attention to replacement needs ahead of the September 2026 approval expiry. Wageningen University and Research showed in 2024 that approval costs carry a heavy weight in investment decisions for new low-risk substances, which means reformulation is easier for large suppliers than for smaller entrants. That pressure is reducing room for older chemistry while raising the commercial value of compliant alternatives. As a result, suppliers are shifting more capital, lower-risk actives, and new coating systems that can stay on the market longer.
Tight EU Re-Approval and Residue Compliance Burden
The Europe wheat seed treatment market still faces a major drag from the time and cost of product re-approval. The fludioxonil decision showed how one regulatory change can affect many cereal seed treatments at the same time and leave growers with fewer short-term substitutes. Wageningen University and Research also found that dossier costs remain one of the largest barriers for new low-risk products, which weighs most heavily on smaller developers. This slows portfolio renewal even when agronomic demand is strong. It also reinforces the advantage of large companies that can spread compliance cost across broader product ranges.
Other drivers and restraints analyzed in the detailed report include:
- Carbon-Linked Agronomy Incentives for Lower-Input Crop Protection
- Seed Treatment Use in Precision Seeding and Variable-Rate Farming
- Higher Cost of Advanced Treatment Formulations and Application Lines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Insecticides were the largest product type in the Europe wheat seed treatment market share, with 50.4% share in 2025. This part of the Europe wheat seed treatment industry remains rooted in long-established commercial routines that target soil insects and virus-carrying pests before emergence. Growers continue to value seed-stage control because it offers a clear application window and protects early stand establishment. Restrictions on some legacy chemistries have not reduced demand, as they have shifted buyers toward higher-value replacement products.
Fungicides are the fastest product type in the Europe wheat seed treatment market size and are projected to grow at 4.7% through 2031. The main reason is the heavier pressure from Fusarium, rust, smut, and related diseases across important wheat belts. The fludioxonil review has added urgency to reformulation work, which is pushing suppliers toward new multi-active combinations and lower-risk options. This part of the Europe wheat seed treatment industry is therefore growing through value mix change as much as through area treated.
Complete Report Scope:
- By Product Type
- Insecticides
- Fungicides
- Nematicides
- Other Types
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
List of Companies Covered in this Report:
- Bayer AG
- Corteva Agriscience
- Syngenta Group
- UPL Limited
- Sumitomo Chemical Co., Ltd.
- BASF SE
- Albaugh LLC
- FMC Corporation
- Incotec Group B.V.
- Croda International Plc
- Koppert B.V.
- Nufarm Limited
- PI Industries Ltd.
- Rovensa Group
- Sipcam Oxon S.p.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising wheat fungal disease pressure
- 4.2.2 Regulatory shift away from high-risk chemical actives
- 4.2.3 Carbon-linked agronomy incentives for lower-input crop protection
- 4.2.4 Seed treatment use in precision seeding and variable-rate farming
- 4.2.5 Increase in area under cultivation of wheat
- 4.2.6 Cold-chain and shelf-life advances in seed coatings
- 4.3 Market Restraints
- 4.3.1 Tight EU re-approval and residue compliance burden
- 4.3.2 Higher cost of advanced treatment formulations and application lines
- 4.3.3 Limited efficacy consistency across variable climates
- 4.3.4 Brexit-linked approval fragmentation
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Insecticides
- 5.1.2 Fungicides
- 5.1.3 Nematicides
- 5.1.4 Other Types
- 5.2 Europe
- 5.2.1 Germany
- 5.2.2 United Kingdom
- 5.2.3 France
- 5.2.4 Italy
- 5.2.5 Spain
- 5.2.6 Russia
- 5.2.7 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Bayer AG
- 6.4.2 Corteva Agriscience
- 6.4.3 Syngenta Group
- 6.4.4 UPL Limited
- 6.4.5 Sumitomo Chemical Co., Ltd.
- 6.4.6 BASF SE
- 6.4.7 Albaugh LLC
- 6.4.8 FMC Corporation
- 6.4.9 Incotec Group B.V.
- 6.4.10 Croda International Plc
- 6.4.11 Koppert B.V.
- 6.4.12 Nufarm Limited
- 6.4.13 PI Industries Ltd.
- 6.4.14 Rovensa Group
- 6.4.15 Sipcam Oxon S.p.A.
7 Market Opportunities and Future Outlook

