PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119276

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119276
Industrial Robot Intelligence Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the industrial robot intelligence software market size is projected to expand from USD 1.83 billion in 2025 and USD 2.04 billion in 2026 to USD 3.26 billion by 2031, registering a CAGR of 9.83% between 2026 to 2031.
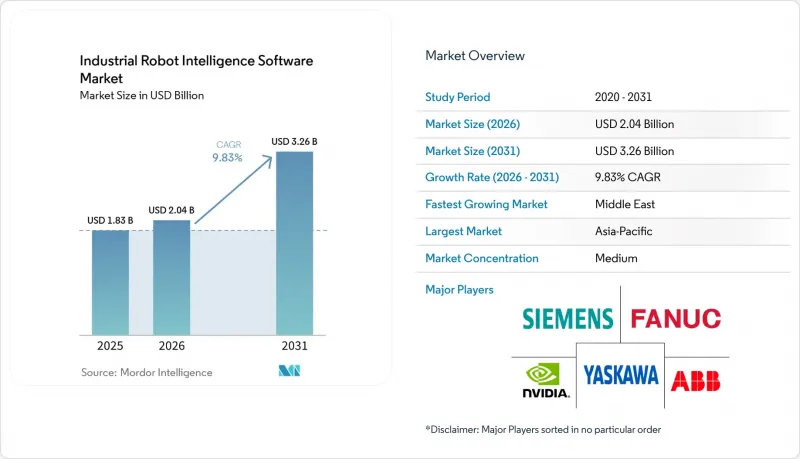
This report is Segmented by Software Function (Robot Programming and Offline Programming, and More), Deployment Model (On-Premise, and More), Application (Material Handling and Packaging, and More), End-User Industry (Automotive, and More), Enterprise Size (Large Enterprises, and Small and Medium-Sized Enterprises) and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Industrial Robot Intelligence Software Market Trends and Insights
AI-Enabled Adaptive Robot Execution
Foundation models for physical AI are changing the economics of industrial robotics. Manufacturers can train broad policies and adapt them to individual cells, rather than programming every action separately. This approach can lower the software effort for applications that previously required extensive custom work. FANUC deepened its ROBOGUIDE integration with NVIDIA Isaac Sim in May 2026 so simulation and physical robots use the same control algorithms, addressing trajectory differences between the two settings. ABB planned RobotStudio HyperReality for release in the second half of 2026, using NVIDIA Omniverse to support a claimed 99% correlation between virtual and physical robot behavior. A 2026 Nature Communications study found that combining precision perception with language-model reasoning improved results on complex, fault-tolerant manufacturing tasks. These developments support continued spending on the industrial robot intelligence software market as hardware costs decline and software capabilities expand.
Factory Labor Scarcity and Reshoring Economics
Labor shortages are making automation decisions less dependent on short-term capital cycles. Manufacturing employers need systems that can perform tasks with less reliance on scarce specialist labor. The International Federation of Robotics reported that U.S. robot installations rose 11% to 38,000 units in 2025, the third strongest result on record. The Federal Reserve Bank of San Francisco found that firms facing trade-policy uncertainty increased their use of industrial robots, linking policy risk with automation activity. This creates demand for software upgrades in existing fleets as well as new robot projects. AI-guided execution becomes more relevant where manufacturers must sustain output while controlling labor and relocation costs. The industrial robot intelligence software market, therefore, benefits when reshoring programs require flexible, repeatable production methods.
High Integration and Validation Cost
Deploying intelligence software in established factories requires coordination with programmable logic controllers, safety controls, vision systems, and manufacturing execution systems. This work can cost more than the software license in complex, multi-supplier cells. ABB's estimate of up to 80% lower commissioning time for RobotStudio HyperReality indicates the scale of existing commissioning effort, though a new software stack still requires upfront investment. Researchers at the University of Southern Denmark found that reconfiguration and programming were the leading barriers to robot adoption in small-batch European manufacturing settings. Validation can lengthen projects where multiple brands, safety interlocks, and legacy systems are involved. Pre-certified modules and common integration layers can reduce the burden, but they do not eliminate the need for site-specific testing. This slows adoption in the industrial robot intelligence software market among organizations with smaller budgets or limited integrator support.
Other drivers and restraints analyzed in the detailed report include:
- Digital Twins and Virtual Commissioning Requirements
- Low-Code Programming for High-Mix Production
- Cybersecurity and Functional-Safety Exposure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Robot Programming and Offline Programming accounted for 24.78% of the industrial robot intelligence software market in 2025, making it the largest software-function category. Its position reflects long-running investment in OEM programming environments and the large installed base of teach-pendant workflows. ABB RobotStudio, FANUC ROBOGUIDE, and KUKA iiQWorks support planning, programming, and validation tasks that remain essential in production cells. Perception and Vision Guidance is projected to expand at a 12.16% CAGR through 2031, the fastest rate among software functions. AI-native vision tools can locate parts from CAD reference frames without dedicated fixtures. That capability reduces setup work for lower-volume applications and supports a wider set of production conditions. A 2025 study reported a mean average precision of 98.40% for a detection model trained on synthetic data on real industrial inspection images. The result shows how CAD models and physics-based image generation can reduce the data-collection effort for industrial perception.
Simulation and Digital Twin software link programming and perception, allowing engineers to validate vision-guided tasks in a virtual environment. FANUC and NVIDIA strengthened their integration in May 2026 to address differences between simulated and physical robot behavior. Motion Planning and control are also gaining value in applications where multiple robots must coordinate their movements and avoid collisions in shared workspaces. Realtime Robotics addresses this requirement with motion-planning software that operates above controller firmware. Predictive Maintenance and Diagnostics, along with Data Management and Analytics, expand as manufacturers use robot telemetry as a production input. KUKA's iiQWorks.Copilot combines AI assistance with simulation workflows. This brings programming, simulation, and AI support closer together in a single workflow. The industrial robot intelligence software market is consequently shifting from separate functional tools toward more integrated engineering platforms.
On-Premises deployment accounted for 60.59% of the market in 2025. This lead reflects the need for local control in motion-sensitive production operations. Closed-loop servo control operates at cycle times below 4 milliseconds and cannot depend on cloud round-trip latency. Automotive, aerospace, and defense supply chains also apply strict data-control requirements to production software. These factors keep execution-layer functions close to the robot controller. On-premises environments continue to support the high reliability needed for safety-critical operations. They also allow manufacturers to manage local validation and plant-specific configurations. This structural role limits the speed at which cloud services can replace locally deployed control software.
Cloud-Based deployment is projected to expand at a 13.02% CAGR through 2031. The model supports large-scale AI training, synthetic-data generation, and collaboration across locations. NVIDIA OSMO supports orchestration of Isaac Sim workflows across distributed compute environments. ABB's RobotStudio HyperReality can export parameterized robot stations to NVIDIA Omniverse for cloud-based model training before hardware commissioning. Robotics-as-a-Service contracts combine hardware, software, connectivity, and maintenance into recurring operating expenses. Workr has used cloud-trained physical AI with ABB robots to serve smaller manufacturers. Hybrid architectures combine local execution with cloud-based updates and fleet analytics. This approach gives multi-site manufacturers centralized intelligence management without compromising real-time performance at the cell level.
Complete Report Scope:
- By Software Function
- Robot Programming and Offline Programming
- Perception and Vision Guidance
- Simulation and Digital Twin
- Motion Planning and Control
- Other Software Functions (Predictive Maintenance and Diagnostics, Data Management and Analytics)
- By Deployment Model
- On-Premises
- Cloud-Based
- Hybrid
- By Application
- Material Handling and Packaging
- Assembly and Joining
- Welding and Surface Treatment
- Quality Inspection and Metrology
- Machine Tending and Processing
- Other Applications (Picking, Kitting, and Order Fulfillment, Intralogistics and Mobile Manipulation, Hazardous-Environment Operations)
- By End-User Industry
- Automotive and Mobility
- Electronics and Semiconductors
- General Manufacturing
- Food and Beverage
- Pharmaceuticals and Medical Devices
- Other End-User Industries (Metals and Machinery, Logistics and Warehousing, Aerospace and Defense)
- By Enterprise Size
- Large Enterprises
- Small and Medium-Sized Enterprises
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- Italy
- France
- United Kingdom
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific held 48.62% of the market in 2025. China installed 295,000 industrial robots in 2024, accounting for 54% of global annual installations, and had an operational stock of 2,027,200 units, creating ongoing demand for programming, AI upgrades, and connected operations. Samsung announced KRW 19 trillion (USD 13.77 billion) for humanoid robot mass production and AI-centered manufacturing in Gumi in July 2026, while Hyundai Wia announced KRW 400 billion (USD 289.9 million) for robotics investments, including stakes in AI and software startups. Config raised a USD 27 million seed round in May 2026 for robot-foundation-model data collection and a cloud-based robot-as-a-service platform. Japan and South Korea have large installed bases of robots that require periodic software upgrades, while India and Australia offer faster-growing opportunities for newer software stacks.
North America and Europe together provide the next largest combined contribution to the industrial robot intelligence software market. The United States installed 38,000 robots in 2025, an 11% increase from the prior year, with food-sector automation, reshoring programs, and AI infrastructure contributing to demand. NVIDIA's Isaac ecosystem supports simulation, synthetic-data generation, and edge deployment for developers and manufacturers. Western Europe recorded a robot density of 267 units per 10,000 manufacturing employees in 2024, with Germany, Switzerland, the Netherlands, and Italy leading regional adoption. European customers place particular weight on virtual commissioning, safety standards, and cybersecurity requirements, while South America remains an emerging area centered on automotive assembly and programming tools.
The Middle East is projected to expand at 13.06% CAGR through 2031, the fastest geographic rate in the industrial robot intelligence software market. Saudi Vision 2030 and the United Arab Emirates Operation 300bn connect robotics deployment with wider diversification plans. ADNOC deployed a heavy-duty autonomous operator robot at Taweelah in 2026, with full operation targeted by year-end. Lianhe Sowell International Group signed a USD 132.5 million financing framework in October 2025 for an AI-powered robot manufacturing and research base in the United Arab Emirates, while Micropolis AI Robotics signed a USD 1.2 million deployment agreement with EMSTEEL in May 2026 for 4 autonomous logistics robots. These activities show commercial deployments emerging alongside state-backed pilots, while Africa remains the smallest geographic segment, with early demand in South Africa and Nigeria focused on extractives, logistics, and food processing.
- ABB Ltd.
- FANUC Corporation
- Siemens AG
- NVIDIA Corporation
- Yaskawa Electric Corporation
- KUKA Aktiengesellschaft
- Rockwell Automation, Inc.
- Mitsubishi Electric Corporation
- Omron Corporation
- Universal Robots A/S
- Robert Bosch GmbH
- Dassault Systemes SE
- PTC Inc.
- Microsoft Corporation
- Amazon Web Services, Inc.
- Inbolt SAS
- Augmentus Pte. Ltd.
- Palladyne AI Corp.
- Fizyr B.V.
- Brain Corporation
- Realtime Robotics, Inc.
- Visual Components Oy
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AI-Enabled Adaptive Robot Execution
- 4.2.2 Factory Labor Scarcity and Reshoring Economics
- 4.2.3 Digital Twins and Virtual Commissioning Requirements
- 4.2.4 Low-Code Programming for High-Mix Production
- 4.2.5 CAD-Trained Perception for Fixture-Light Automation
- 4.2.6 Synthetic Data and Sim-to-Real Training Pipelines
- 4.3 Market Restraints
- 4.3.1 High Integration and Validation Cost
- 4.3.2 Cybersecurity and Functional-Safety Exposure
- 4.3.3 Sim-to-Real Transfer Risk in Variable Cells
- 4.3.4 Scarcity of Safety-Certified Robotics Software Talent
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Software Function
- 5.1.1 Robot Programming and Offline Programming
- 5.1.2 Perception and Vision Guidance
- 5.1.3 Simulation and Digital Twin
- 5.1.4 Motion Planning and Control
- 5.1.5 Other Software Functions (Predictive Maintenance and Diagnostics, Data Management and Analytics)
- 5.2 By Deployment Model
- 5.2.1 On-Premises
- 5.2.2 Cloud-Based
- 5.2.3 Hybrid
- 5.3 By Application
- 5.3.1 Material Handling and Packaging
- 5.3.2 Assembly and Joining
- 5.3.3 Welding and Surface Treatment
- 5.3.4 Quality Inspection and Metrology
- 5.3.5 Machine Tending and Processing
- 5.3.6 Other Applications (Picking, Kitting, and Order Fulfillment, Intralogistics and Mobile Manipulation, Hazardous-Environment Operations)
- 5.4 By End-User Industry
- 5.4.1 Automotive and Mobility
- 5.4.2 Electronics and Semiconductors
- 5.4.3 General Manufacturing
- 5.4.4 Food and Beverage
- 5.4.5 Pharmaceuticals and Medical Devices
- 5.4.6 Other End-User Industries (Metals and Machinery, Logistics and Warehousing, Aerospace and Defense)
- 5.5 By Enterprise Size
- 5.5.1 Large Enterprises
- 5.5.2 Small and Medium-Sized Enterprises
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 Italy
- 5.6.3.3 France
- 5.6.3.4 United Kingdom
- 5.6.3.5 Russia
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Turkey
- 5.6.5.4 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Nigeria
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 FANUC Corporation
- 6.4.3 Siemens AG
- 6.4.4 NVIDIA Corporation
- 6.4.5 Yaskawa Electric Corporation
- 6.4.6 KUKA Aktiengesellschaft
- 6.4.7 Rockwell Automation, Inc.
- 6.4.8 Mitsubishi Electric Corporation
- 6.4.9 Omron Corporation
- 6.4.10 Universal Robots A/S
- 6.4.11 Robert Bosch GmbH
- 6.4.12 Dassault Systemes SE
- 6.4.13 PTC Inc.
- 6.4.14 Microsoft Corporation
- 6.4.15 Amazon Web Services, Inc.
- 6.4.16 Inbolt SAS
- 6.4.17 Augmentus Pte. Ltd.
- 6.4.18 Palladyne AI Corp.
- 6.4.19 Fizyr B.V.
- 6.4.20 Brain Corporation
- 6.4.21 Realtime Robotics, Inc.
- 6.4.22 Visual Components Oy
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

