PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120582

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120582
United States Wind Energy - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the United States wind energy market size was valued at 161.20 gigawatt in 2025 and estimated to grow from 167.92 gigawatt in 2026 to reach 205.93 gigawatt by 2031, at a CAGR of 4.17% during the forecast period (2026-2031).
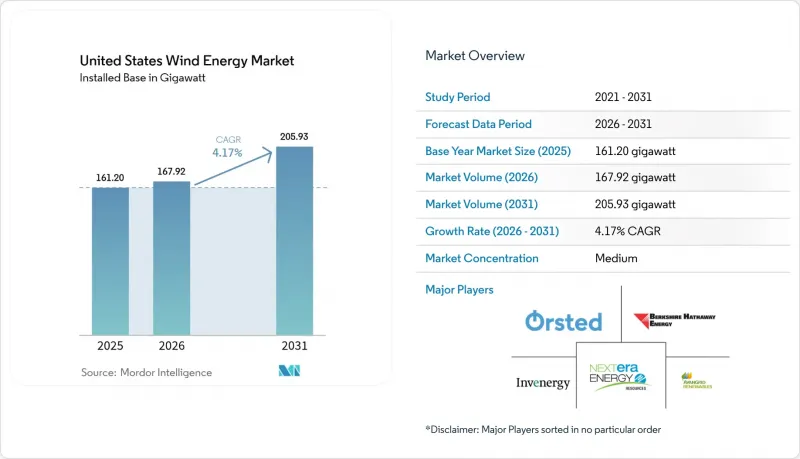
This report is Segmented by Location (Onshore and Offshore), Turbine Capacity (Less Than 3 MW, 3 To 6 MW, and Above 6 MW), and Application (Utility-Scale, Commercial and Industrial, and Community Projects). The Market Size and Forecasts are Provided in Terms of Installed Capacity (GW).
United States Wind Energy Market Trends and Insights
IRA Tax Credits and PTC Extensions
The IRA's 10-year extension of production tax credits through 2032, plus a 10-percentage-point domestic-content adder, lifted post-tax project returns from 6.5% to 8.2%. Announcements for 18 GW of new capacity entered development pipelines during 2024 after the legislation was passed. The law mandates that, by 2025, 40% of steel and 55% of manufactured components originate domestically, steering orders toward Iowa and Colorado factories. Internal Revenue Service audits in late 2024 disqualified 1.2 GW for foreign-origin bearings, spotlighting traceability gaps. Developers in ERCOT now opt for the IRA's 30% investment tax credit to monetize value upfront when volatile basis risk deters long-term PPAs.
Falling LCOE from Taller Turbines
National Renewable Energy Laboratory data show the onshore LCOE sliding to USD 26 per MWh in 2024 as rotor diameters hit 170 m and hub heights 110 m. GE Vernova and Vestas platforms above 6 MW are harvesting 52% capacity factors at Class 4 sites in Arkansas and Tennessee, regions once uneconomical for wind. Thermoplastic composite blades reduce weight by 12% and cut balance-of-system spending by USD 80,000 per turbine. Cost compression has pushed eight gigawatts of gas-fired generation into early retirement during 2024, a pivotal inflection for the United States wind energy market.
Transmission and Interconnection Bottlenecks
Regional transmission queues reached 2,600 GW in December 2024, with wind accounting for 950 GW, and average study times stretched to 5.2 years. MISO alone holds 180 GW awaiting USD 48 billion in network upgrades, 60% of which need new 345-kV lines that require seven years to permit. FERC Order 2023 moves to a first-ready, first-served regime, but only CAISO has fully implemented it by mid-2024, so most developers still face serial processing. Disputes over how to share USD 6 billion of transmission costs halted five projects last year.
Other drivers and restraints analyzed in the detailed report include:
- Corporate PPAs Momentum
- Repowering Aging Fleet Unlocks Capacity
- Rising Capex and Supply-Chain Inflation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Onshore assets dominated 99.88% of cumulative capacity in 2025, reflecting decades of incremental build-out across Texas and the Great Plains, where Class 5-7 wind resources deliver 45-50% capacity factors. However, the Bureau of Ocean Energy Management has auctioned eight lease areas since 2022, setting the stage for a 47.69% CAGR in offshore capacity that will reshape the United States wind energy market. Vineyard Wind 1 began commercial operation in May 2024 with 13 MW turbines sustaining 60% capacity factors, demonstrating offshore competitiveness. The onshore build cycle continues in Texas and Oklahoma, which added 5 GW combined in 2024 because ERCOT's merchant model still clears projects within 18 months.
Jones Act constraints limit offshore build-out to about 2 GW per year through 2026, yet project pipelines total 30 GW. Dominion Energy's 2.6 GW Coastal Virginia venture secured the first U.S.-built installation vessel, but day-rates above USD 500,000 lift capex 12% versus European analogs. Repowering older onshore sites provides a parallel growth lever: NextEra's 1.8 GW Iowa campaign tripled site output without new interconnection filings. Floating offshore concepts for California's 25 GW resource remain in pre-commercial testing as mooring systems presently cost USD 1 million per MW, a hurdle unlikely to fall before 2028.
Complete Report Scope:
- By Location
- Onshore
- Offshore
- By Turbine Capacity
- Up to 3 MW
- 3 to 6 MW
- Above 6 MW
- By Application
- Utility-scale
- Commercial and Industrial
- Community Projects
- By Component (Qualitative Analysis)
- Nacelle/Turbine
- Blade
- Tower
- Generator and Gearbox
- Balance-of-System
List of Companies Covered in this Report:
- NextEra Energy Resources LLC
- Berkshire Hathaway Energy (MidAmerican)
- Invenergy LLC
- Avangrid Renewables LLC
- Duke Energy Sustainable Solutions
- Orsted North America
- Dominion Energy Inc.
- Acciona Energia SA
- EDF Renewables North America
- Enel Green Power North America Inc.
- EDP Renewables North America LLC
- General Electric Vernova
- Siemens Gamesa Renewable Energy
- Vestas-American Wind Technology Inc.
- Nordex USA Inc.
- TPI Composites Inc.
- Pattern Energy Group LP
- Clearway Energy Group
- RES Americas Inc.
- Apex Clean Energy Inc.
- Trident Winds Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 IRA tax credits & PTC extensions
- 4.2.2 Falling LCOE from taller turbines
- 4.2.3 Corporate PPAs momentum
- 4.2.4 Repowering ageing fleet unlocks capacity
- 4.2.5 Green-hydrogen wind demand nexus
- 4.2.6 Domestic-content bonus under IRA
- 4.3 Market Restraints
- 4.3.1 Transmission & interconnection bottlenecks
- 4.3.2 Rising capex & supply-chain inflation
- 4.3.3 Jones-Act vessel shortage (offshore)
- 4.3.4 Wildlife litigation & local opposition
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 PESTLE Analysis
5 Market Size & Growth Forecasts
- 5.1 By Location
- 5.1.1 Onshore
- 5.1.2 Offshore
- 5.2 By Turbine Capacity
- 5.2.1 Up to 3 MW
- 5.2.2 3 to 6 MW
- 5.2.3 Above 6 MW
- 5.3 By Application
- 5.3.1 Utility-scale
- 5.3.2 Commercial and Industrial
- 5.3.3 Community Projects
- 5.4 By Component (Qualitative Analysis)
- 5.4.1 Nacelle/Turbine
- 5.4.2 Blade
- 5.4.3 Tower
- 5.4.4 Generator and Gearbox
- 5.4.5 Balance-of-System
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 NextEra Energy Resources LLC
- 6.4.2 Berkshire Hathaway Energy (MidAmerican)
- 6.4.3 Invenergy LLC
- 6.4.4 Avangrid Renewables LLC
- 6.4.5 Duke Energy Sustainable Solutions
- 6.4.6 Orsted North America
- 6.4.7 Dominion Energy Inc.
- 6.4.8 Acciona Energia SA
- 6.4.9 EDF Renewables North America
- 6.4.10 Enel Green Power North America Inc.
- 6.4.11 EDP Renewables North America LLC
- 6.4.12 General Electric Vernova
- 6.4.13 Siemens Gamesa Renewable Energy
- 6.4.14 Vestas-American Wind Technology Inc.
- 6.4.15 Nordex USA Inc.
- 6.4.16 TPI Composites Inc.
- 6.4.17 Pattern Energy Group LP
- 6.4.18 Clearway Energy Group
- 6.4.19 RES Americas Inc.
- 6.4.20 Apex Clean Energy Inc.
- 6.4.21 Trident Winds Inc.
7 Market Opportunities & Future Outlook
- 7.1 Expansion in the Offshore Sector
- 7.2 Hybrid Wind-Solar-Storage Projects
- 7.3 Green Hydrogen Integration
- 7.4 Repowering Market Potential

