PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121272

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121272
Europe Contract Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Europe contract packaging market size is expected to increase from USD 27.03 billion in 2025 to USD 28.78 billion in 2026 and reach USD 40.85 billion by 2031, growing at a CAGR of 7.26% over 2026-2031.
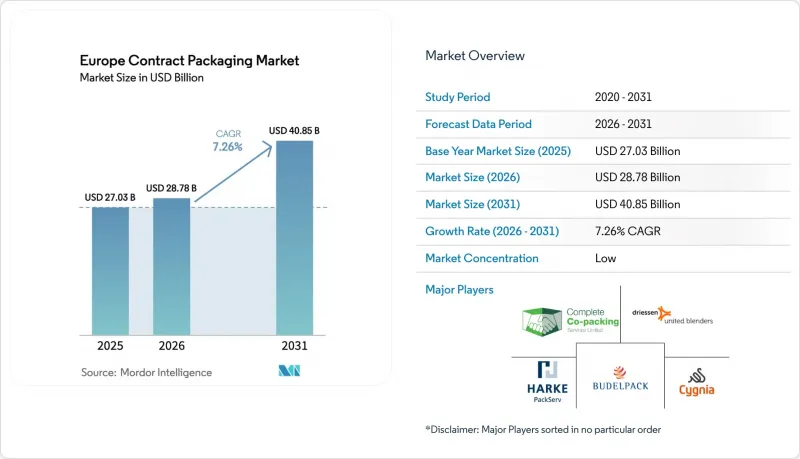
This report is Segmented by Service Type (Primary Packaging, Secondary Packaging, and Tertiary Packaging), Packaging Format (Rigid Packaging, and Flexible Packaging), Technology (Conventional Manual Lines, Semi-Automated Lines, and Fully Automated/Robotics-Enabled Lines), End-User Industry (Food, Pharmaceuticals, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Europe Contract Packaging Market Trends and Insights
Rising E-commerce Fulfilment Volumes
Online retail parcels jumped throughout 2025 as grocery, health supplements, and premium beverages migrated to direct shipment models. Contract packers that offer pick, fill, and ship services witnessed double-digit order growth, prompting them to standardize box sizes, install print-on-demand labelers, and add late-stage customization cells. Medium enterprises opted to outsource instead of building captive lines, citing the need for seasonal flexibility and avoiding capital outlay. Higher parcel velocity has made automated weigh-check-label modules essential for maintaining carrier compliance. Providers located near parcel sortation centers in Germany, the Netherlands, and France are benefiting from lower last-mile fees.
Proliferation of DTC Brands
More than 480 new DTC labels opened regional web shops in 2025, targeting niche markets in health, beauty, and eco-friendly home care. These founders prefer variable-count cartons and influencer kits that must be assembled in small batches, accompanied by kitting instructions and QR-enabled inserts. Contract packers able to combine secondary packaging, fulfillment, and returns handling gained multi-year contracts that include periodic product restaging. Subscription-box curators also accelerated demand for insert printing and data-driven personalization, resulting in lead times of three days or less for short runs. As private-equity inflows sustain this launch cycle, co-packers that embed real-time order-status APIs are capturing repeat volumes.
Stringent EU Packaging Waste Directive Targets
The revised directive requires producers to reduce packaging waste by 15% per capita by 2030 and to achieve 65% recycling rates. Such mandates prompt brands to reduce over-packaging, thereby directly reducing the volume flowing through contract packers. Additionally, forthcoming eco-modulation fees penalize non-recyclable formats, forcing co-packers to requalify equipment for new substrates and thinner gauges with limited stretch tolerance. Compliance monitoring and reporting add administrative overhead, especially for small and mid-size facilities. While the rule accelerates innovation, it simultaneously delays investment as converters await definitive specifications for recycled content.
Other drivers and restraints analyzed in the detailed report include:
- Retailer Shift to Shelf-Ready Packaging Formats
- Growth of Sustainable Mono-Material Substrates
- Rising Labour Costs in Western Europe
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Secondary packaging generated the highest volume of assemblies, capturing 41.23% of the Europe contract packaging market share in 2025. The dominance reflects ongoing retailer and e-commerce requirements for bar-coded cartons, security seals, and promotional over-wraps. In 2026, demand for automated cartoning and shrink bundling systems continues to climb as brand portfolios expand their SKU counts. Secondary workflows remain attractive due to recurring orders, high labor content, and the scope for late-stage pack differentiation. Providers are bolstering line flexibility, retrofitting robotic pick-and-place units that switch formats within 30 minutes to serve multi-client halls.
Tertiary operations, encompassing palletizing and stretch-hooding, are forecast to outpace all other service tiers with an 8.34% CAGR. The upswing aligns with wider adoption of integrated warehouse management and the transition to mixed-SKU pallet configurations favored by omnichannel retailers. Robotics-enabled pallet cells equipped with vision-guided tooling support higher output and ergonomic relief. Contract packers are marketing predictive-maintenance dashboards that lower downtime, appealing to fast-moving consumer goods customers under just-in-time restock pressure. Consequently, tertiary volumes are expected to chip away at in-house logistics, reinforcing the Europe contract packaging market narrative of specialized fulfillment partners.
Rigid formats, including glass bottles, aluminum cans, and high-density polyethylene jugs, led with a 52.32% share of the Europe contract packaging market size in 2025. Beverage filling, personal-care bottling, and pharma blistering rely on rigid systems due to product protection and dosing accuracy. Co-packers owning clean-room and cold-fill infrastructure enjoy high barriers to entry, leading to steady throughput. Moreover, returnable glass loops in Germany expand bottling line utilization. Brand owners remain keen on rigid packs for premiumization as well as real and perceived recyclability in closed loops.
Conversely, flexible substrates are set to be the fastest-growing category, advancing at an 8.84% CAGR during 2026-2031. Re-closable pouches, stand-up spouts, and sachets reduce material usage and shipping weight, appealing to retailers' sustainability scorecards. Contract packers that certify migration-safe films for acidic foods and pharma powders are landing multi-year volumes. Integration of digital pouch printing allows shorter runs tied to geographic and language variations, bolstering agile marketing programs. Thus, flexible share is predicted to narrow the gap with rigid formats, reinforcing diversification across the Europe contract packaging market.
Complete Report Scope:
- By Service Type
- Primary Packaging
- Bottling and Filling
- Pouching
- Canning
- Blister Packaging
- Other Primary Packaging
- Secondary Packaging
- Cartoning
- Labeling
- Shrink Wrapping
- Other Secondary Packaging
- Tertiary Packaging
- Palletizing
- Bundling
- Other Tertiary Packaging
- Primary Packaging
- By Packaging Format
- Rigid Packaging
- Flexible Packaging
- By Technology
- Conventional Manual Lines
- Semi-Automated Lines
- Fully Automated / Robotics-Enabled Lines
- By End-user Industry
- Beverages
- Food
- Pharmaceuticals
- Cosmetics and Personal Care
- Other End-user Industries
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Netherlands
- Rest of Europe
List of Companies Covered in this Report:
- Budelpack Poortvliet BV
- Cygnia Logistics Ltd
- Complete Co-Packing Services Ltd
- Driessen United Blenders BV
- Harke PackServ GmbH
- Kompak Co-Making and Co-Packing
- Marvinpac SA
- NOMI Co-Packing
- Boughey Distribution Ltd
- Total Pack BV
- DHL Supply Chain
- Staci Group
- Sonoco Display and Packaging
- WePack Ltd
- Flexicon Europe Ltd
- MSK Pharmalogistic GmbH
- Groupe LPR (Logistic Packaging Resources)
- Famar SA
- PharmaPac UK Ltd
- Tjoapack Netherlands BV
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising E-commerce Fulfilment Volumes
- 4.2.2 Proliferation of DTC (Direct-to-Consumer) Brands
- 4.2.3 Retailer Shift to Shelf-Ready Packaging Formats
- 4.2.4 Growth of Sustainable Mono-Material Substrates
- 4.2.5 Adoption of Digital Printing for Short-Runs
- 4.2.6 Near-shoring of Supply Chains Post-Brexit
- 4.3 Market Restraints
- 4.3.1 Stringent EU Packaging Waste Directive Targets
- 4.3.2 Rising Labour Costs in Western Europe
- 4.3.3 Competition from In-house Packaging Operations
- 4.3.4 Limited Access to Recycled PCR Material
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Primary Packaging
- 5.1.1.1 Bottling and Filling
- 5.1.1.2 Pouching
- 5.1.1.3 Canning
- 5.1.1.4 Blister Packaging
- 5.1.1.5 Other Primary Packaging
- 5.1.2 Secondary Packaging
- 5.1.2.1 Cartoning
- 5.1.2.2 Labeling
- 5.1.2.3 Shrink Wrapping
- 5.1.2.4 Other Secondary Packaging
- 5.1.3 Tertiary Packaging
- 5.1.3.1 Palletizing
- 5.1.3.2 Bundling
- 5.1.3.3 Other Tertiary Packaging
- 5.1.1 Primary Packaging
- 5.2 By Packaging Format
- 5.2.1 Rigid Packaging
- 5.2.2 Flexible Packaging
- 5.3 By Technology
- 5.3.1 Conventional Manual Lines
- 5.3.2 Semi-Automated Lines
- 5.3.3 Fully Automated / Robotics-Enabled Lines
- 5.4 By End-user Industry
- 5.4.1 Beverages
- 5.4.2 Food
- 5.4.3 Pharmaceuticals
- 5.4.4 Cosmetics and Personal Care
- 5.4.5 Other End-user Industries
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Netherlands
- 5.5.7 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Budelpack Poortvliet BV
- 6.4.2 Cygnia Logistics Ltd
- 6.4.3 Complete Co-Packing Services Ltd
- 6.4.4 Driessen United Blenders BV
- 6.4.5 Harke PackServ GmbH
- 6.4.6 Kompak Co-Making and Co-Packing
- 6.4.7 Marvinpac SA
- 6.4.8 NOMI Co-Packing
- 6.4.9 Boughey Distribution Ltd
- 6.4.10 Total Pack BV
- 6.4.11 DHL Supply Chain
- 6.4.12 Staci Group
- 6.4.13 Sonoco Display and Packaging
- 6.4.14 WePack Ltd
- 6.4.15 Flexicon Europe Ltd
- 6.4.16 MSK Pharmalogistic GmbH
- 6.4.17 Groupe LPR (Logistic Packaging Resources)
- 6.4.18 Famar SA
- 6.4.19 PharmaPac UK Ltd
- 6.4.20 Tjoapack Netherlands BV
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

