PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123760

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123760
District Heating - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the district heating market size was valued at USD 53.46 billion in 2025 and estimated to grow from USD 54.25 billion in 2026 to reach USD 58.35 billion by 2031, at a CAGR of 1.47% during the forecast period (2026-2031).
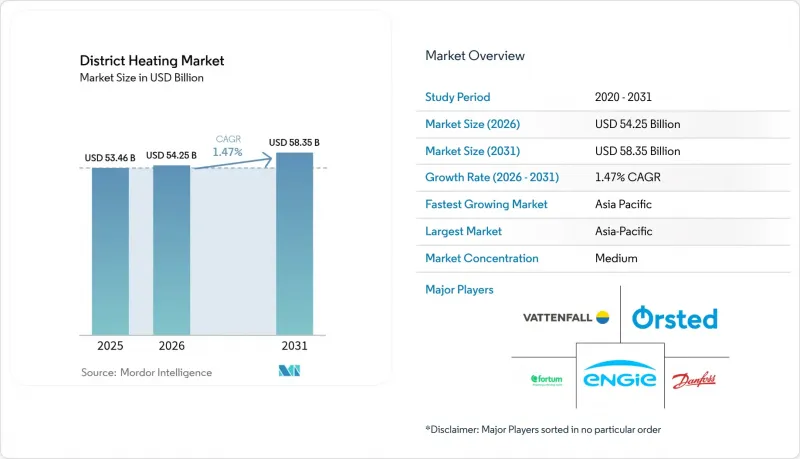
This report is Segmented by Plant Type (Boiler Plant, Combined Heat and Power (CHP), and More), Heat Source (Coal, Natural Gas, and More), Application (Residential, Commercial, and Industrial), Distribution Temperature Tier (High, Low and More) and by Geography. The Report Offers Market Forecasts and Size in Value (USD)
Global District Heating Market Trends and Insights
Mandated Phase-out of Fossil Boilers Across EU Boosting Retrofits
The European Union's accelerated ban on oil and gas boilers is funneling retrofit demand into the district heating market. Member states aim to connect more than 40 million additional households by 2030, reducing stranded-asset risk for legacy gas grids. Retrofit programs are especially appealing in dense cities where individual heat pumps face space constraints. New rules compel large data centers to feed excess heat into municipal grids, enhancing load diversity and revenue security. Utilities in Denmark, Germany and France are therefore prioritizing low-temperature network expansion to satisfy building-owner obligations and to tap EU Innovation Fund grants for carbon-neutral heat.
China's Ultra-low-emission CHP Conversions
China's clean-heating policy is steering the district heating market toward a hybrid portfolio of electric boilers, heat pumps and low-emission CHP facilities. Pilot projects in Hebei and Shandong demonstrate particulate-matter cuts near 90% compared with earlier coal units, while grid-connected heat pumps improve capacity-factor utilization of renewable power. The low-coal scenario outlined by academic research suggests electric technologies could supply 34% of China's district-heat load by 2030, unlocking equipment exports to Southeast Asia. Provincial authorities are therefore bundling rooftop solar and thermal-storage incentives with district-heat licenses to align air-quality targets and peak-shaving goals.
High grid-connection fees in low-density U.S. regions
New district-heating lines in suburban America face connection fees above €800/kW, undermining project feasibility where density is low. Fragmented state regulations and lack of federal incentives amplify financial risk, slowing adoption despite high decarbonization potential. Few municipal utilities possess the balance-sheet strength to underwrite long-tenor loans without revenue guarantees. The Climate Catalyst Program in California has begun to de-risk data-center heat-reuse schemes, but broader policy harmonization is required to transplant those gains to the Midwest and Northeast. Without a clear tariff model, prospective customers hesitate, dampening network build-out beyond campus and military installations.
Other drivers and restraints analyzed in the detailed report include:
- Municipal Waste-to-energy Integration in Nordic & Benelux Cities
- 4th and 5th-generation low-temperature networks using data-center waste heat
- Uncertain gas-price-cap regimes in Eastern Europe affecting CHP economics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Waste-heat recovery stations are forecast to expand at a 4.57% CAGR from 2026-2031, well above the overall district heating market. Project economics benefit from avoided primary-fuel costs and new corporate-power-purchase-agreement models that monetise decarbonization attributes. In contrast, CHP retained 61.35% of the district heating market share in 2025, anchoring the district heating market size for baseload supply and grid-balancing services. Asset operators are now pairing thermal storage with CHP to shift run-times toward peak-price hours and to accommodate surplus renewable generation. Heat-only boiler houses hold niche value for peak-shaving and for small networks where full CHP cycles are uneconomic.
The district heating market sees heightened interest in modular heat-pump clusters and data-center tie-ins, which reduce distribution temperatures and enable flexible, multi-vector configurations. Industrial sites appreciate these systems for simultaneous process cooling and steam-raising, while municipalities gain resilience from supply diversification. Standardised skid designs shorten construction cycles and unlock Build-Own-Operate-Transfer contracts attractive to infrastructure funds. Over the forecast period, integration of stratified buffer tanks is expected to smooth diurnal load swings, reducing operational expenditure and permitting higher variable-renewable-energy penetration.
Renewables are projected to be the fastest-growing component of the district heating market, delivering a 5.42% CAGR and adding geothermal doublets, agro-biomass boilers and solar-thermal fields to existing grids. European cities are bundling geothermal drilling risk into national guarantee funds, cutting financing costs and accelerating project sanction. Solar-thermal growth is propelled by 28 large fields commissioned in 2023 alone, adding 139 MWth to the district heating market size for clean heat. Natural gas, while still holding 44.10% of the district heating market size in 2025, faces carbon-price escalation and methane-leak scrutiny.
Industrial waste heat is emerging as a bridge resource, filling gaps until deeper renewable integration materialises. Economics depend on pipeline distance and temperature lift, but rising carbon prices improve payback. Nuclear-based heat using small modular reactors garners policymaker interest for process-steam applications yet remains contingent on siting approvals. Overall, heat-source diversification lowers geopolitical exposure and aligns with EU taxonomy rules that will increasingly shape capital flows into the district heating industry.
Complete Report Scope:
- By Plant Type
- Boiler
- Combined Heat and Power (CHP)
- Heat-Only Boiler
- Waste-Heat Recovery Plants
- By Heat Source
- Coal
- Natural Gas
- Renewables
- Biomass
- Geothermal
- Solar Thermal
- Industrial Waste-Heat
- Oil and Petroleum Products
- Nuclear (SMR-based heat)
- By Distribution Temperature Tier
- High Temperature (> 100 °C)
- Medium Temperature (80-100 °C)
- Low Temperature (< 80 °C, 4G/5G)
- By Network Type
- Closed-Loop
- Open-Loop
- By Plant Capacity
- less than equals to 50 MWth
- 51-200 MWth
- 201-500 MWth
- greater than equals to 500 MWth
- By Ownership Model
- Public Utility
- Private Utility
- Public-Private Partnership
- By Application
- Residential
- Commercial
- Industrial
- Public and Institutional
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- Sweden
- Denmark
- Finland
- United Kingdom
- France
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America's district heating market is pivoting from campus-based steam networks to mixed-temperature systems that recover industrial and data-center waste heat. Projects such as the Bellingham Waterfront redevelopment in Washington showcase heat networks four times more efficient than legacy gas boilers. Yet the region grapples with high grid-connection fees that dampen suburban uptake, highlighting the need for harmonised incentives and tariff reform to unlock broader potential. California's new statute qualifying data-center heat capture for state finance exemplifies progressive policy carving out new corridors of growth.
Europe continues to command the largest share of the district heating market owing to extensive legacy pipework and ambitious decarbonization mandates. Denmark illustrates best practice, with 63% of its data centers planning surplus-heat offtake agreements. Germany targets 50% renewable and recycled heat in its grids by 2030, stimulating demand for biomass gasifiers, geothermal, and large-scale solar-thermal parks. Ownership diversity-municipal in Denmark, private in the Netherlands-yields heterogeneous investment models but collectively sustains technology leadership and export capability.
Asia-Pacific, anchored by China, offers the strongest volumetric growth prospects for the district heating market. Market-oriented reforms have lifted total-factor productivity among Chinese heating enterprises by up to 7.4% since 2003, setting the stage for cleaner fuel substitution. Japan and South Korea pursue dense urban networks that capitalise on high load factors, while Turkey and New Zealand pilot deep-geothermal feeds. Regional policy now links air-quality targets with renewables uptake, encouraging integrated planning that accelerates network expansion and modernisation.
- Vattenfall AB
- ENGIE SA
- Fortum Oyj
- Orsted A/S
- Danfoss A/S
- Veolia Environnement SA
- Statkraft AS
- NRG Energy Inc.
- Keppel Corporation Ltd.
- SP Group
- Korean District Heating Corp.
- Copenhagen Energy
- Logstor A/S
- Vital Energi Ltd.
- Alfa Laval AB
- Ramboll Group A/S
- Shinryo Corporation
- FVB Energy Inc.
- FortisBC Energy Inc.
- Kelag Waerme GmbH
- Empower Energy Solutions (Dubai)
- Helen Oy
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Mandated phase-out of fossil boilers across EU boosting retrofits (Europe)
- 4.2.2 China's ultra-low-emission CHP conversions (Asia)
- 4.2.3 Municipal waste-to-energy integration in Nordic and Benelux cities
- 4.2.4 4-/5-Generation low-temperature networks using data-center waste heat (N.America and Europe)
- 4.2.5 Geothermal heat tenders in Turkey and Hungary cutting LCOH < €25/MWh
- 4.2.6 Off-site industrial process-heat PPAs in petro-chemical clusters (US and EU)
- 4.3 Market Restraints
- 4.3.1 High grid-connection fees (> €800/kW) in low-density U.S. regions
- 4.3.2 Uncertain gas-price-cap regimes in Eastern Europe affecting CHP economics
- 4.3.3 Skilled-labour shortages delaying low-temperature retrofits (DE and UK)
- 4.3.4 Heat-user lock-in perceptions limiting green-bond financing
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory and Government Initiatives Outlook
- 4.6 Technological Outlook and Key Innovations
- 4.7 Investment Analysis
- 4.8 Impact of COVID-19 on District Heating
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Bargaining Power of Suppliers
- 4.9.2 Bargaining Power of Consumers
- 4.9.3 Threat of New Entrants
- 4.9.4 Threat of Substitute Products
- 4.9.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Plant Type
- 5.1.1 Boiler
- 5.1.2 Combined Heat and Power (CHP)
- 5.1.3 Heat-Only Boiler
- 5.1.4 Waste-Heat Recovery Plants
- 5.2 By Heat Source
- 5.2.1 Coal
- 5.2.2 Natural Gas
- 5.2.3 Renewables
- 5.2.3.1 Biomass
- 5.2.3.2 Geothermal
- 5.2.3.3 Solar Thermal
- 5.2.3.4 Industrial Waste-Heat
- 5.2.4 Oil and Petroleum Products
- 5.2.5 Nuclear (SMR-based heat)
- 5.3 By Distribution Temperature Tier
- 5.3.1 High Temperature (> 100 °C)
- 5.3.2 Medium Temperature (80-100 °C)
- 5.3.3 Low Temperature (< 80 °C, 4G/5G)
- 5.4 By Network Type
- 5.4.1 Closed-Loop
- 5.4.2 Open-Loop
- 5.5 By Plant Capacity
- 5.5.1 less than equals to 50 MWth
- 5.5.2 51-200 MWth
- 5.5.3 201-500 MWth
- 5.5.4 greater than equals to 500 MWth
- 5.6 By Ownership Model
- 5.6.1 Public Utility
- 5.6.2 Private Utility
- 5.6.3 Public-Private Partnership
- 5.7 By Application
- 5.7.1 Residential
- 5.7.2 Commercial
- 5.7.3 Industrial
- 5.7.4 Public and Institutional
- 5.8 By Geography
- 5.8.1 North America
- 5.8.1.1 United States
- 5.8.1.2 Canada
- 5.8.1.3 Mexico
- 5.8.2 South America
- 5.8.2.1 Brazil
- 5.8.2.2 Argentina
- 5.8.2.3 Rest of South America
- 5.8.3 Europe
- 5.8.3.1 Germany
- 5.8.3.2 Sweden
- 5.8.3.3 Denmark
- 5.8.3.4 Finland
- 5.8.3.5 United Kingdom
- 5.8.3.6 France
- 5.8.3.7 Rest of Europe
- 5.8.4 Asia-Pacific
- 5.8.4.1 China
- 5.8.4.2 Japan
- 5.8.4.3 South Korea
- 5.8.4.4 India
- 5.8.4.5 Rest of Asia-Pacific
- 5.8.5 Middle East
- 5.8.5.1 Saudi Arabia
- 5.8.5.2 United Arab Emirates
- 5.8.5.3 Turkey
- 5.8.5.4 Rest of Middle East
- 5.8.6 Africa
- 5.8.6.1 South Africa
- 5.8.6.2 Egypt
- 5.8.6.3 Rest of Africa
- 5.8.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves and Developments
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, Recent Developments)
- 6.4.1 Vattenfall AB
- 6.4.2 ENGIE SA
- 6.4.3 Fortum Oyj
- 6.4.4 Orsted A/S
- 6.4.5 Danfoss A/S
- 6.4.6 Veolia Environnement SA
- 6.4.7 Statkraft AS
- 6.4.8 NRG Energy Inc.
- 6.4.9 Keppel Corporation Ltd.
- 6.4.10 SP Group
- 6.4.11 Korean District Heating Corp.
- 6.4.12 Copenhagen Energy
- 6.4.13 Logstor A/S
- 6.4.14 Vital Energi Ltd.
- 6.4.15 Alfa Laval AB
- 6.4.16 Ramboll Group A/S
- 6.4.17 Shinryo Corporation
- 6.4.18 FVB Energy Inc.
- 6.4.19 FortisBC Energy Inc.
- 6.4.20 Kelag Waerme GmbH
- 6.4.21 Empower Energy Solutions (Dubai)
- 6.4.22 Helen Oy
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

