PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124881

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124881
Europe District Heating - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
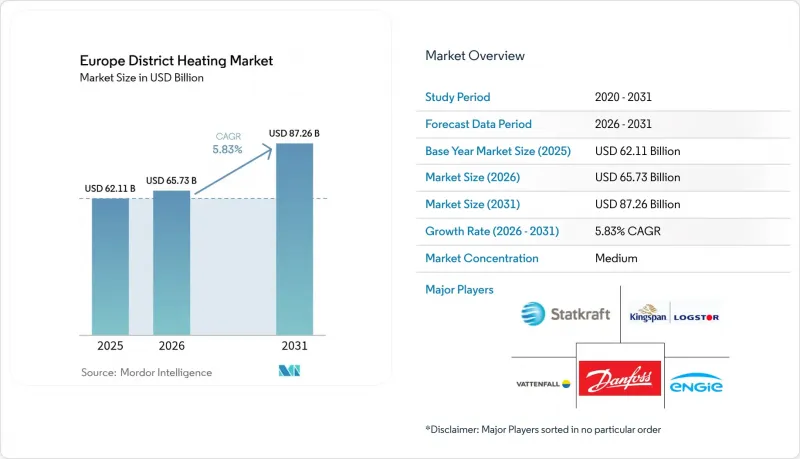
According to Mordor Intelligence, european district heating market size in 2026 is estimated at USD 65.73 billion, growing from 2025 value of USD 62.11 billion with 2031 projections showing USD 87.26 billion, growing at 5.83% CAGR over 2026-2031.
This report is Segmented by Heat Source (Fossil Fuels, Renewable Energy, and More), Plant Type (Combined Heat and Power, Boiler-Based Plants, and Large-Scale Heat Pumps), Distribution Technology (Pre-Insulated Steel Pipes, Flexible Plastic Piping, and More), End User (Residential, Commercial, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Europe District Heating Market Trends and Insights
Rapid Build-out of 4th-Gen Low-Temperature Networks in Scandinavia
Scandinavian utilities are standardizing 4th-generation networks that operate 20-45 °C below legacy systems, reducing distribution losses by up to 30% and enabling the cost-effective use of ambient and waste-heat resources. Projects such as Lund's Cool DH and Sweden's SEK 18 billion EcoDataCenter 2 combine large-scale heat pumps (COP> 4.0) with recycled industrial heat, slashing fuel costs while creating anchor loads for future grid extensions. Nordic design codes now form the basis of EU technical specifications, accelerating technology transfer into Central Europe.
Mandatory Phase-out of Individual Gas Boilers in Germany and Netherlands
Germany's Building Energy Act obliges new heating systems to source 65% renewable energy from 2024, effectively eliminating new fossil boilers and triggering a surge in district heating connections in land-constrained urban cores. The Netherlands follows with a fully electric mandate for new builds by 2025 and hybrid heat-pump requirements for retrofits by 2026, reinforcing network economics in dense municipalities. Federal and local grants of up to EUR 21,000 (about USD 24,700) for renewable heating support payback periods under eight years.
High Retrofit Costs for Legacy 3rd-Gen Networks
Central- and Eastern-European grids require EUR 500-800 per meter to re-pipe and decouple outdated boilers, stretching municipal debt envelopes and causing multi-year postponements of planned conversions.
Other drivers and restraints analyzed in the detailed report include:
- EU Carbon Border Adjustment Mechanism Accelerating Industrial Switching
- Surging Data-Centre Waste-Heat Recovery Contracts in Northern Europe
- Lengthy Concession-Award Cycles and Municipal Tender Delays
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fossil fuels retained 51.45% of the European district heating market share in 2025, primarily due to the continued use of entrenched gas and coal boilers, which remain economical when carbon prices are low. However, renewables post the fastest 10.8% CAGR to 2031, driven by the compatibility of biomass co-firing with existing furnaces, the abundance of geothermal energy in the Pannonian Basin, and growing industrial-waste heat offtake contracts. Nordic grids already surpass 42.6% renewable penetration, setting a precedent for the rest of the bloc. Solar-thermal fields, now costing EUR 20-50/MWh, scale quickly in Spain and France, smoothing summer demand dips through seasonal storage. Hybrid setups combine biomass baseloads with high-temperature heat pumps, enabling fossil-free, dispatchable heat that meets new emission reduction targets.
Geographically, geothermal pilot wells in Hungary and Croatia gain EU modernization grants, while Italy and Germany test deep-drilling rigs for 200 °C aquifers. Data-center waste heat joins the renewable basket, supplying stable 65-80 °C streams into 4GDH circuits. Seasonal intermittency drives the buildup of water-pit storage tanks with a capacity exceeding 100,000 m3 in Denmark, resulting in a 5-7 EUR/MWh reduction in marginal supply costs.
Combined heat and power units retained a 56.75% share of the European district heating market size in 2025, valued for dual energy streams and grid-balancing flexibility. Yet large heat pumps expand at 14.05% CAGR, spurred by cheaper renewable electricity and refrigerant advances that lift COPs above 5. Berlin's 75 MW wastewater heat pump underscores a shift toward centralized electrified heat. Hybrid plants blend CHP turbines for winter peaks with variable-speed heat pumps for shoulder seasons, optimizing network return temperatures below 55 °C.
Nordic OEMs are ramping up production capacity; Sweden's new 500,000-unit factory signals economies of scale that will push capital costs below EUR 500/kW by 2027. CO2-based systems from Danish research institutes target dense urban neighborhoods, where flammability limits the use of synthetic refrigerants. Utilities retrofit existing CHPs with post-combustion carbon capture to protect sunk assets while reducing emission factors.
Complete Report Scope:
- By Heat Source
- Fossil Fuels
- Renewable Energy (Biomass, Geothermal, Solar-Thermal)
- Industrial and Data-Centre Waste Heat
- By Plant Type
- Combined Heat and Power (CHP)
- Boiler-Based Plants
- Large-Scale Heat Pumps
- By Distribution Technology
- Pre-insulated Steel Pipes
- Flexible Plastic Piping
- Substations and Heat Exchangers
- Control and Monitoring Systems
- By End User
- Residential
- Commercial
- Industrial
- Public and Institutional
- By Country
- Germany
- France
- Austria
- Sweden
- United Kingdom
- Italy
- Rest of Europe
List of Companies Covered in this Report:
- Vattenfall AB
- Engie SA
- Danfoss A/S
- Veolia Environnement SA
- Fortum Oyj
- Statkraft AS
- E.ON SE
- Logstor A/S
- Vital Energi Ltd
- Goteborg Energi
- Alfa Laval AB
- Ramboll Group A/S
- Kelvion Holding GmbH
- Savosolar Oyj
- Isoplus Piping Systems
- Uponor Infra Oy
- Thermaflex International
- REHAU AG
- Cory Group
- Cetetherm AB
- NIBE Industrier AB
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Build-out of 4th-Gen Low-Temperature Networks in Scandinavia
- 4.2.2 Mandatory Phase-out of Individual Gas Boilers in Germany and Netherlands
- 4.2.3 EU Carbon Border Adjustment Mechanism Accelerating Industrial Switching
- 4.2.4 Surging Data-Centre Waste-Heat Recovery Contracts in Northern Europe
- 4.2.5 District Cooling Synergies in Southern Europe's Urban Redevelopments
- 4.2.6 Green-Bond Financing Windows Driving Municipal Network Expansions
- 4.3 Market Restraints
- 4.3.1 High Retrofit Costs for Legacy 3rd-Gen Networks
- 4.3.2 Lengthy Concession-Award Cycles and Municipal Tender Delays
- 4.3.3 Skills Shortage in Large-Diameter Pre-insulated Pipe Welding
- 4.3.4 Competing On-Site Heat-Pump Economics in Mild-Climate Zones
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Outlook
- 4.5.1 Government Initiatives and Programs on District Heating/Cooling Transition
- 4.6 Technological Outlook
- 4.6.1 Development of District Heating Technology
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Trends on the Market
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Heat Source
- 5.1.1 Fossil Fuels
- 5.1.2 Renewable Energy (Biomass, Geothermal, Solar-Thermal)
- 5.1.3 Industrial and Data-Centre Waste Heat
- 5.2 By Plant Type
- 5.2.1 Combined Heat and Power (CHP)
- 5.2.2 Boiler-Based Plants
- 5.2.3 Large-Scale Heat Pumps
- 5.3 By Distribution Technology
- 5.3.1 Pre-insulated Steel Pipes
- 5.3.2 Flexible Plastic Piping
- 5.3.3 Substations and Heat Exchangers
- 5.3.4 Control and Monitoring Systems
- 5.4 By End User
- 5.4.1 Residential
- 5.4.2 Commercial
- 5.4.3 Industrial
- 5.4.4 Public and Institutional
- 5.5 By Country
- 5.5.1 Germany
- 5.5.2 France
- 5.5.3 Austria
- 5.5.4 Sweden
- 5.5.5 United Kingdom
- 5.5.6 Italy
- 5.5.7 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles
- 6.4.1 Vattenfall AB
- 6.4.2 Engie SA
- 6.4.3 Danfoss A/S
- 6.4.4 Veolia Environnement SA
- 6.4.5 Fortum Oyj
- 6.4.6 Statkraft AS
- 6.4.7 E.ON SE
- 6.4.8 Logstor A/S
- 6.4.9 Vital Energi Ltd
- 6.4.10 Goteborg Energi
- 6.4.11 Alfa Laval AB
- 6.4.12 Ramboll Group A/S
- 6.4.13 Kelvion Holding GmbH
- 6.4.14 Savosolar Oyj
- 6.4.15 Isoplus Piping Systems
- 6.4.16 Uponor Infra Oy
- 6.4.17 Thermaflex International
- 6.4.18 REHAU AG
- 6.4.19 Cory Group
- 6.4.20 Cetetherm AB
- 6.4.21 NIBE Industrier AB
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

