PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125296

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125296
Asia-Pacific Induction Motor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Asia Pacific induction motor market size was valued at USD 15.99 billion in 2025 and estimated to grow from USD 17.79 billion in 2026 to reach USD 30.56 billion by 2031, at a CAGR of 11.23% during the forecast period (2026-2031).
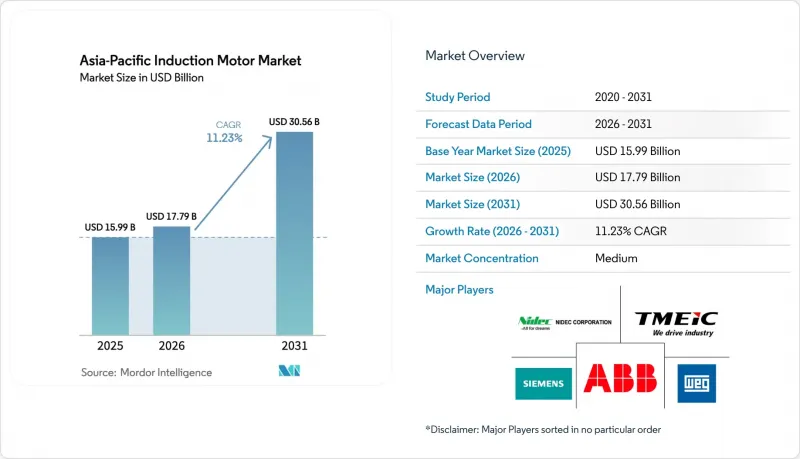
This report is Segmented by Phase (Single Phase Induction Motor, and Three Phase Induction Motor), Power Rating (Below 0. 5 KW, 0. 5 KW - 7. 5 KW, 7. 5 KW - 37 KW, 37 KW - 75 KW, and Above 75 KW), Efficiency Class (IE1, IE2, IE3, IE4), End-User Industry (Oil and Gas, Power Generation, Chemical and Petrochemical, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Asia-Pacific Induction Motor Market Trends and Insights
Increasing Need for Higher Energy Efficiency
Utility demand-response programs, carbon pricing mechanisms, and corporate net-zero pledges elevate energy efficiency to the top of procurement criteria across the Asia Pacific induction motor market. Motor-driven systems consume nearly 45% of the world's power, making efficiency gains pivotal for grid stability and reducing emissions. Advances such as amorphous-metal cores and optimized magnetic circuits push efficiencies beyond IE4 levels. Hitachi's radial-gap prototype achieves 95% efficiency at 20,000 rpm, while occupying one-fifth the volume of conventional motors. Coupled with variable-frequency drives and smart control algorithms, these innovations yield rapid paybacks in energy-intensive sectors including mining, petrochemicals, and data processing. The convergence of economic and environmental incentives secures steady demand for premium-class motors over the medium term.
Government Energy-Efficiency Mandates Across the Asia Pacific
Regulatory standards are pivotal in steering the Asia Pacific induction motor market toward higher efficiency classes. China enforces IE3 as the minimum standard for most industrial applications, Japan's Top Runner program continually raises benchmarks, and Australia mandates specific efficiency thresholds for motors exceeding 0.73 kW. These policies trigger compliance-driven replacement cycles, compelling OEMs to integrate IE3 and IE4 motors into equipment destined for regulated markets. Harmonization discussions within ASEAN are pointing to the broader adoption of similar rules, which is expected to amplify demand for premium motors across Southeast Asia. Manufacturers that align product lines early capture share and reduce retrofit complexity for end users facing binding deadlines.
Availability of Permanent-Magnet Synchronous Motor Alternatives
Permanent-magnet synchronous motors (PMSMs) boast higher power density and superior part-load efficiency, thereby eroding the induction motor's share in precision-speed applications. Chinese automaker GAC's 98.5% efficient e-drive demonstrates PMSM performance advantages and cost convergence as rare-earth prices stabilize. In robotics and servo duties, PMSMs offer microsecond response times, along with smaller footprints, tilting buyer preference away from induction technology. Induction suppliers counter with hybrid designs and control-software enhancements, yet the competitive threat persists, particularly in premium power segments.
Other drivers and restraints analyzed in the detailed report include:
- Accelerating Industrial Automation Investments
- Rapid Growth in Data Center Construction Across Southeast Asia
- High Initial Cost of Premium-Efficiency (IE4) Induction Motors
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Three-phase motors secured a 78.62% market share in the Asia Pacific induction motor market in 2025, underscoring their centrality to industrial operations that value balanced power delivery and robust torque. The Asia Pacific induction motor market size for three-phase units is expected to expand steadily as automation intensifies in manufacturing hubs. Single-phase motors, which hold the remaining 21.38%, are rapidly scaling across distributed manufacturing and residential automation, benefiting from their straightforward installation and compatibility with standard utility feeds.
Industrial robotics, precision machining, and conveyor systems continue to anchor three-phase demand, particularly in China, Japan, and South Korea. Conversely, the growth of small workshops, residential HVAC, and edge-computing installations in Southeast Asia propels single-phase uptake at a double-digit CAGR. Suppliers tailor marketing strategies by phase, promoting durability and control sophistication for three-phase buyers while emphasizing price and plug-and-play convenience for single-phase prospects.
The 0.5 kW - 7.5 kW bracket commanded 33.25% of the Asia Pacific induction motor market size in 2025, reflecting its deployment across auxiliary pumps, compressors, and general-purpose machinery. Sub-0.5 kW units, though smaller in value, are projected to register an 11.52% CAGR as compact IoT devices and miniaturized HVAC systems proliferate.
High-power segments above 75 kW cater to large-scale mining, petrochemical, and power generation duties, yet modest capacity additions and a preference for efficiency upgrades over new builds cap their growth pace. In parallel, advances in magnetic materials and cooling techniques elevate power density, enabling lower-rating motors to perform tasks once reserved for larger frames. This evolution reinforces the twin-track growth narrative of the Asia Pacific induction motor market.
Complete Report Scope:
- By Phase
- Single Phase Induction Motor
- Three Phase Induction Motor
- By Power Rating
- Below 0.5 kW
- 0.5 kW - 7.5 kW
- 7.5 kW - 37 kW
- 37 kW - 75 kW
- Above 75 kW
- By Efficiency Class
- IE1 Standard Efficiency
- IE2 High Efficiency
- IE3 Premium Efficiency
- IE4 Super Premium Efficiency
- By End-User Industry
- Oil and Gas
- Chemical and Petrochemical
- Power Generation
- Water and Wastewater
- Metal and Mining
- Food and Beverage
- Discrete Manufacturing
- Heating, Ventilation and Air-Conditioning (HVAC)
- Other End-User Industries
- By Country
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia Pacific
List of Companies Covered in this Report:
- ABB Ltd.
- Siemens AG
- Nidec Corporation
- Toshiba Mitsubishi-Electric Industrial Systems Corporation (TMEIC)
- WEG S.A.
- Regal Rexnord Corporation
- Fuji Electric Co., Ltd.
- Kirloskar Electric Company Limited
- SEALOCEAN Motor Co., Ltd.
- TECO Electric and Machinery Co., Ltd.
- Hyundai Electric and Energy Systems Co., Ltd.
- CG Power and Industrial Solutions Limited
- Brook Crompton Asia Pacific Pte. Ltd.
- Leroy-Somer (Nidec Leroy-Somer Holding)
- Toshiba Corporation
- Mitsubishi Electric Corporation
- Schneider Electric SE
- Lafert Group S.p.A.
- Bharat Bijlee Limited
- Marathon Electric India Pvt. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Need for Higher Energy Efficiency
- 4.2.2 Rising Demand for Power Savings in Residential and Industrial Sectors
- 4.2.3 Government Energy-Efficiency Mandates Across Asia Pacific
- 4.2.4 Accelerating Industrial Automation Investments
- 4.2.5 Rapid Growth in Data Center Construction Across Southeast Asia
- 4.2.6 Plug-and-Play IE4 Motor Retrofits in Brownfield Facilities
- 4.3 Market Restraints
- 4.3.1 Availability of Permanent-Magnet Synchronous Motor Alternatives
- 4.3.2 High Initial Cost of Premium-Efficiency (IE4) Induction Motors
- 4.3.3 Grid Instability in Emerging Economies Limiting Large-Motor Deployment
- 4.3.4 Inverter-Driven Harmonics Causing Early Motor Failures
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers/Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Phase
- 5.1.1 Single Phase Induction Motor
- 5.1.2 Three Phase Induction Motor
- 5.2 By Power Rating
- 5.2.1 Below 0.5 kW
- 5.2.2 0.5 kW - 7.5 kW
- 5.2.3 7.5 kW - 37 kW
- 5.2.4 37 kW - 75 kW
- 5.2.5 Above 75 kW
- 5.3 By Efficiency Class
- 5.3.1 IE1 Standard Efficiency
- 5.3.2 IE2 High Efficiency
- 5.3.3 IE3 Premium Efficiency
- 5.3.4 IE4 Super Premium Efficiency
- 5.4 By End-User Industry
- 5.4.1 Oil and Gas
- 5.4.2 Chemical and Petrochemical
- 5.4.3 Power Generation
- 5.4.4 Water and Wastewater
- 5.4.5 Metal and Mining
- 5.4.6 Food and Beverage
- 5.4.7 Discrete Manufacturing
- 5.4.8 Heating, Ventilation and Air-Conditioning (HVAC)
- 5.4.9 Other End-User Industries
- 5.5 By Country
- 5.5.1 China
- 5.5.2 India
- 5.5.3 Japan
- 5.5.4 South Korea
- 5.5.5 Australia and New Zealand
- 5.5.6 Rest of Asia Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Siemens AG
- 6.4.3 Nidec Corporation
- 6.4.4 Toshiba Mitsubishi-Electric Industrial Systems Corporation (TMEIC)
- 6.4.5 WEG S.A.
- 6.4.6 Regal Rexnord Corporation
- 6.4.7 Fuji Electric Co., Ltd.
- 6.4.8 Kirloskar Electric Company Limited
- 6.4.9 SEALOCEAN Motor Co., Ltd.
- 6.4.10 TECO Electric and Machinery Co., Ltd.
- 6.4.11 Hyundai Electric and Energy Systems Co., Ltd.
- 6.4.12 CG Power and Industrial Solutions Limited
- 6.4.13 Brook Crompton Asia Pacific Pte. Ltd.
- 6.4.14 Leroy-Somer (Nidec Leroy-Somer Holding)
- 6.4.15 Toshiba Corporation
- 6.4.16 Mitsubishi Electric Corporation
- 6.4.17 Schneider Electric SE
- 6.4.18 Lafert Group S.p.A.
- 6.4.19 Bharat Bijlee Limited
- 6.4.20 Marathon Electric India Pvt. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

