PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2157028

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2157028
United Kingdom Secure Logistics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the United Kingdom secure logistics market size was valued at USD 2.26 billion in 2025 and estimated to grow from USD 2.33 billion in 2026 to reach USD 3.24 billion by 2031, at a CAGR of 6.84% during the forecast period (2026-2031).
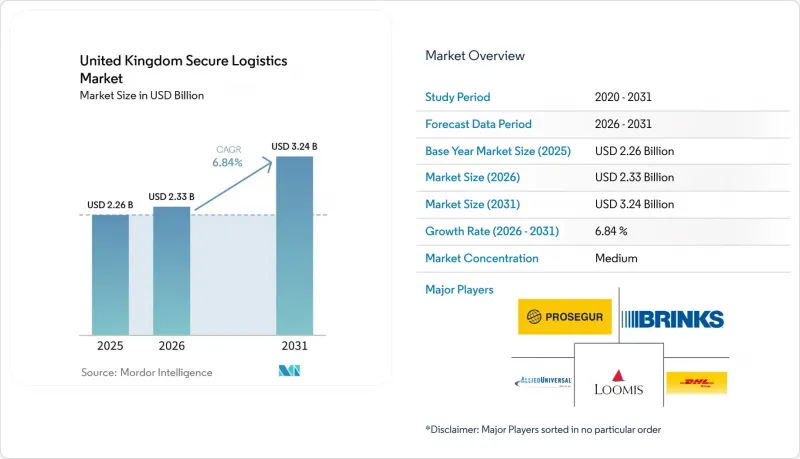
The United Kingdom secure logistics market continues to depend on cash handling, high-value shipments, and the protection of sensitive supply chains. This report is Segmented by Service Type (Transportation, Warehousing and Storage, Value-Added Services), by Application (Cash Management, Diamonds, Jewelry and Precious Metal, Manufacturing, Others), by Type (Static, Mobile), and by End User (Financial Institutions, Retailers, Government, Others). The Market Forecasts are Provided in Terms of Value (USD).
United Kingdom Secure Logistics Market Trends and Insights
Cash-Heavy Retail and Banking Footprint Remained Material
Cash still serves an important role for many consumers and retail locations across the United Kingdom. Nearly 15% of adults preferred cash, and 1.2 million people used it for almost all daily spending in July 2025. ATM replenishment, vault processing, and note circulation, therefore, remained central to the United Kingdom secure logistics market. Bank branch closures concentrated activity through LINK ATMs, Post Office outlets, and banking hubs. Those sites required frequent replenishment and larger cash deliveries. Tesco IMS processed 300 million cash withdrawals annually through its ATM network, representing 18% of annual United Kingdom cash withdrawals.
High-Value Pharmaceutical and Life Sciences Movements Required Chain-of-Custody Security
Pharmaceutical distribution required documented handovers, temperature control, and secure handling throughout the journey. These requirements made chain-of-custody controls important for high-value and controlled medicines. Specialized operators could support customers who needed validated storage and monitored transport. This requirement encouraged investment in dedicated pharmaceutical infrastructure within the United Kingdom secure logistics market. DHL announced its commitment of EUR 2 billion (USD 2.2 billion) for healthcare and life sciences logistics during 2025-2030. Movianto UK began its 5-year NHS England contract in August 2026, providing national vaccine logistics to more than 11,000 frontline healthcare locations in England.
Cash Substitution in Everyday Transactions
Cash payments fell to 3.9 billion in 2025, representing 8% of all United Kingdom payments. Research reported 4.3 billion cash payments during 2024 and forecasted a 4% share by 2035. This shift reduced low-value and high-frequency replenishment activity, especially in locations with strong debit card use. Residual cash demand remained important among older people, small businesses, informal economy participants, and cash-dependent consumers. These groups continued to require retail-facing collection, ATM, and deposit services. The FCA planned a formal access-to-cash review in the fourth quarter of 2026 and planned to publish findings during the second quarter of 2027.
Other drivers and restraints analyzed in the detailed report include:
- Premium Jewelry, Luxury, and Collectibles Distribution Supported Specialized Demand
- High-Value and Time-Sensitive E-Commerce Raised Delivery Requirements
- Insurance, Compliance, and Guard Operating Costs Constrained Smaller Operators
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Transportation held 64.50% of the United Kingdom secure logistics market share in 2025. Armored road fleets supported ATM replenishment, cash collection, and high-value parcel movements across urban and suburban routes. Road operations remained the primary service because they connected retail locations, banking sites, and secure processing centers. Rail and air services served selected bullion and pharmaceutical lanes near financial centers and airports. Transportation also supported inter-branch transfers and recurring retail pickup schedules. The United Kingdom secure logistics market depended on these operating networks because general freight providers did not offer the same security controls.
Value-added services are forecast to grow at a 9.50% CAGR through 2031. Smart-safe monitoring, cash forecasting, route planning, and reconciliation services increased customer reliance on providers. These services turned individual transport assignments into longer-running operating relationships. Loomis expanded this model through SafePoint smart-safe devices that transferred deposit risk at the point of insertion. Warehousing and storage remained important for bullion, pharmaceuticals, and collectibles. The United Kingdom secure logistics industry increasingly competed on integrated operating support as well as vehicle capacity.
Cash management accounted for 65.20% of the United Kingdom secure logistics market size in 2025. ATM service, wholesale vault processing, and branch cash handling supported this position. Access-to-cash obligations maintained demand for specialist cash services across banking networks. G4S Cash Centres (United Kingdom) Limited and Vaultex United Kingdom Limited appeared on the Bank of England's recognized operator list. Diamonds, manufacturing components, and other sensitive goods added specialized applications. Each application required clear custody records and appropriate protection during transport.
Jewelry and precious metals are forecast to grow at a 9.20% CAGR through 2031. The segment relied on secure collection, vaulting, international movements, and monitored delivery. London's bullion and gemstone activity made specialized capacity important for customers handling high declared values. Providers also served trade events, auction houses, and luxury retailers that required tightly managed movements. Digital tools gave customers better visibility into secure shipments and stored inventory. The United Kingdom secure logistics market gained from this requirement for physical protection and digital visibility.
Complete Report Scope:
- By Service Type
- Transportation
- Road
- Rail
- Air
- Sea and Inland Waterways
- Warehousing and Storage (including Secure Storage and Vault Services)
- Value-added Services
- Transportation
- By Application
- Cash Management
- Diamonds
- Jewelry and Precious Metal?
- Manufacturing?
- Others
- By Type
- Static
- Mobile
- By End User
- Financial Institutions
- Retailers
- Government
- Others
List of Companies Covered in this Report:
- The Brink's Company
- Loomis AB
- Allied Universal (Including G4S)
- DHL Group
- FedEx
- United Parcel Service of America, Inc. (UPS)
- Rhenus Logistics
- Malca-Amit Group
- Maltacourt Limited
- KSP Security Group Ltd
- Secure Transportation Ltd
- Angleside Security Limited
- Pivotal (Pivotal Sec Plus)
- Logistical Support Services Limited
- Prosegur Group
- Relay Technical Transport Ltd
- B.D.I. Securities (UK) Ltd
- Nationwide Courier Service Ltd
- Deadline Despatch Limited
- Comprehensive Transport Services Limited
- Vaultex UK Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cash-Heavy Retail and Banking Footprint Remains Material
- 4.2.2 High-Value Pharma and Life Sciences Movements Require Chain-of-Custody Security
- 4.2.3 Premiumization of Jewelry, Luxury, and Collectibles Distribution
- 4.2.4 E-Commerce Growth in High-Value and Time-Sensitive Goods
- 4.2.5 Theft Risk and Cargo Crime Pressure
- 4.2.6 Compliance-Driven Security Requirements
- 4.3 Market Restraints
- 4.3.1 Accelerating Cash Substitution in Everyday Transactions
- 4.3.2 High Insurance, Compliance, and Armed-Guard Operating Cost Base
- 4.3.3 Labor Availability Pressure for Licensed Security and Drivers
- 4.3.4 High Capex Requirements for Secure Fleets and Facilities
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
- 4.8 Impact of Geopolitical Events on the Market
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Service Type
- 5.1.1 Transportation
- 5.1.1.1 Road
- 5.1.1.2 Rail
- 5.1.1.3 Air
- 5.1.1.4 Sea and Inland Waterways
- 5.1.2 Warehousing and Storage (including Secure Storage and Vault Services)
- 5.1.3 Value-added Services
- 5.1.1 Transportation
- 5.2 By Application
- 5.2.1 Cash Management
- 5.2.2 Diamonds
- 5.2.3 Jewelry and Precious Metal?
- 5.2.4 Manufacturing?
- 5.2.5 Others
- 5.3 By Type
- 5.3.1 Static
- 5.3.2 Mobile
- 5.4 By End User
- 5.4.1 Financial Institutions
- 5.4.2 Retailers
- 5.4.3 Government
- 5.4.4 Others
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Geographic/Network Coverage, Products and Services, Recent Developments)
- 6.4.1 The Brink's Company
- 6.4.2 Loomis AB
- 6.4.3 Allied Universal (Including G4S)
- 6.4.4 DHL Group
- 6.4.5 FedEx
- 6.4.6 United Parcel Service of America, Inc. (UPS)
- 6.4.7 Rhenus Logistics
- 6.4.8 Malca-Amit Group
- 6.4.9 Maltacourt Limited
- 6.4.10 KSP Security Group Ltd
- 6.4.11 Secure Transportation Ltd
- 6.4.12 Angleside Security Limited
- 6.4.13 Pivotal (Pivotal Sec Plus)
- 6.4.14 Logistical Support Services Limited
- 6.4.15 Prosegur Group
- 6.4.16 Relay Technical Transport Ltd
- 6.4.17 B.D.I. Securities (UK) Ltd
- 6.4.18 Nationwide Courier Service Ltd
- 6.4.19 Deadline Despatch Limited
- 6.4.20 Comprehensive Transport Services Limited
- 6.4.21 Vaultex UK Limited
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

