PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185157

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185157
Asia-Pacific Pre-Engineered Buildings Construction - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
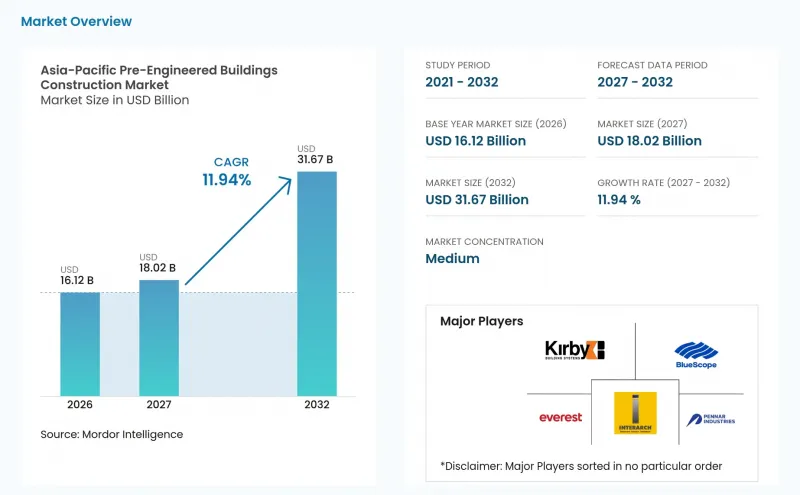
According to Mordor Intelligence, the Asia-Pacific pre-engineered buildings construction market size is expected to increase from USD 16.12 billion in 2026 to USD 18.02 billion in 2027 and reach USD 31.67 billion by 2032, growing at a CAGR of 11.94% over 2027-2032.
Asia-Pacific Pre-Engineered Buildings Construction Market Trends and Insights
China-Plus-One Manufacturing Relocation and Electronics-Capacity Expansion
The structural reorientation of global electronics and consumer manufacturing supply chains away from sole dependence on China is the most immediate demand accelerant for the Asia-Pacific pre-engineered buildings market. Vietnam attracted more than USD 25 billion of realized foreign direct investment (FDI) in 2025, the majority in manufacturing. Companies, including Apple suppliers Foxconn, Goertek, and Luxshare Precision, extended Vietnam manufacturing footprints in Bac Ninh, per Business Times 2025 reporting, creating clustered demand for standardized steel factory structures. Less visible is that Malaysia and India are absorbing semiconductor and electronics assembly investment that requires cleanroom-compatible pre-engineered buildings (PEB) with higher value than basic factory sheds, compounding order book quality, not just volume. Per Reuters in September 2026, the China-plus-one dynamic continues to channel investment into India, Indonesia, and Vietnam despite tariff recalibration, sustaining PEB demand across multiple Asia-Pacific markets simultaneously.
Cross-Border E-Commerce, Port-Led Logistics, and Urban Fulfillment Infrastructure
Port-adjacent logistics infrastructure is scaling across Asia-Pacific, driven by the Regional Comprehensive Economic Partnership (RCEP) Agreement implementation, cross-border e-commerce volume growth, and automated fulfillment center specifications that demand pre-engineered steel for column-free spans and high eave clearance. A.P. Moller - Maersk opened a 1.1 million square foot fully automated distribution center in Singapore in March 2026, serving Asia-Pacific B2B and B2C e-commerce fulfillment at an institutional scale. Frasers Property Vietnam broke ground in 2025 on SPX Express's 170,000 square meter two-story cross-dock logistics facility, targeting 7 million parcels daily, deploying multi-story pre-engineered building systems to maximize leasable area on a constrained footprint. The LO-GOI Yen Phong LEED Gold two-story industrial complex, completed in Bac Ninh, Vietnam, in 2025, further illustrates how two-story fulfillment formats are pulling multi-story pre-engineered building adoption forward faster than single-country dynamics suggest. For pre-engineered building vendors, this represents a structural shift toward higher-value, engineering-intensive designs where design-build capability, not just fabrication volume, determines contract awards.
Imported Steel, Coking-Coal, and Freight-Cost Volatility
Steel price volatility is the most disruptive near-term constraint on Asia-Pacific pre-engineered buildings (PEB) project economics, with hot-rolled coil (HRC) and plate pricing in 2026 responding to iron ore supply shifts, trade policy regimes, and ocean freight dynamics driven by port congestion, per PEB Steel's 2026 cost guidance. Structural steel plate prices stabilized in mid-2026 following a volatile Q2, but quote validity windows of only 7-30 days force procurement decisions under uncertainty. Fleming Construction Group reported in mid-2026 that nonresidential construction costs rose approximately 2.4% in May 2026, accumulating to nearly 10% annually, compressing developer margins across the region. Oversized structural steel components for Asia-Pacific cross-border projects carry specialized freight costs, adding 5-8% to delivered project cost, even when mill prices are flat, a dynamic disproportionately affecting smaller Tier-2 corridor developers lacking escalation contract protections.
Other drivers and restraints analyzed in the detailed report include:
- Mass Urban Housing, Worker Accommodation, and Rapid-Build Construction
- Semiconductor, Battery, and Hyperscale Data-Center Facility Development
- Fragmented Provincial Approval, Fire Certification, and Code-Enforcement Practices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Single-story buildings held 70% of the regional total in 2026, making them the leading structural format in the Asia-Pacific pre-engineered buildings construction market. They are widely used for industrial sheds, logistics buildings, processing facilities, and distribution centers. Their design is familiar to contractors and is easier to integrate with loading yards, forklifts, and ground-level material handling. Single-story formats also suit sites with available land in industrial parks and port-linked corridors. The structure can accommodate long, clear spans for storage, assembly, and production lines. This helps developers preserve flexible floor layouts as tenant requirements change.
Multi-story buildings are forecast to grow at a 12.2% CAGR through 2032 as industrial land becomes less available in dense urban areas. The LO-GOI Yen Phong complex in Bac Ninh, completed in 2025, was presented by Coteccons as northern Vietnam's first LEED Gold two-story industrial and logistics complex. It covers more than 139,000 square meters and has 12.5-meter floor heights, illustrating the scale that a multi-level logistics format can reach. These projects require more detailed structural design, vertical circulation planning, and fire coordination than standard one-level facilities. The Asia-Pacific pre-engineered buildings construction industry can gain from this shift when suppliers build stronger multi-story engineering and erection capabilities.
Complete Report Scope:
- By Structure
- Single-Story
- Multi-Story
- By Product Type
- Modular Buildings
- Panelized and Componentized Systems
- Other Prefabricated Building Types
- By Application
- Residential
- Commercial
- Industrial
- Institutional
- Others
- By Country
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Rest of Asia-Pacific
List of Companies Covered in this Report:
- Kirby Building Systems
- BlueScope Steel Limited
- Everest Industries Limited
- Interarch Building Products Limited
- Pennar Industries Limited
- EPACK Prefab Technologies Limited
- Jindal Buildsys Limited
- PEB Steel Buildings Co., Ltd.
- Zamil Steel Holding Company
- Tiger Steel Engineering LLC
- Larsen & Toubro Limited
- ATAD Steel Structure Corporation
- Butler Manufacturing Company
- Nucor Building Systems
- Kirby International
- Multicolor Steels Private Limited
- SML Group
- Era Infra Engineering Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 China-Plus-One Manufacturing Relocation and Electronics-Capacity Expansion
- 4.2.2 Cross-Border E-Commerce, Port-Led Logistics, and Urban Fulfillment Infrastructure
- 4.2.3 Mass Urban Housing, Worker Accommodation, and Rapid-Build Construction
- 4.2.4 Semiconductor, Battery, and Hyperscale Data-Center Facility Development
- 4.2.5 National Infrastructure Corridors, Industrial Parks, and Smart-City Programs
- 4.3 Market Restraints
- 4.3.1 Imported Steel, Coking-Coal, and Freight-Cost Volatility
- 4.3.2 Fragmented Provincial Approval, Fire Certification, and Code-Enforcement Practices
- 4.3.3 Limited Certified Erector Capacity in Tier-2 and Tier-3 Industrial Corridors
- 4.3.4 Typhoon, Monsoon, Earthquake, and Tropical-Corrosion Design Requirements
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Cost Structure Analysis
- 4.8 Replacement Market Dynamics
- 4.9 Industry Attractiveness - Porter's Five Forces Analysis
- 4.9.1 Threat of New Entrants
- 4.9.2 Bargaining Power of Suppliers
- 4.9.3 Bargaining Power of Buyers
- 4.9.4 Threat of Substitutes
- 4.9.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Structure
- 5.1.1 Single-Story
- 5.1.2 Multi-Story
- 5.2 By Product Type
- 5.2.1 Modular Buildings
- 5.2.2 Panelized and Componentized Systems
- 5.2.3 Other Prefabricated Building Types
- 5.3 By Application
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.3 Industrial
- 5.3.4 Institutional
- 5.3.5 Others
- 5.4 By Country
- 5.4.1 China
- 5.4.2 India
- 5.4.3 Japan
- 5.4.4 South Korea
- 5.4.5 Australia
- 5.4.6 Indonesia
- 5.4.7 Rest of Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Products & Services, and Recent Developments)
- 6.3.1 Kirby Building Systems
- 6.3.2 BlueScope Steel Limited
- 6.3.3 Everest Industries Limited
- 6.3.4 Interarch Building Products Limited
- 6.3.5 Pennar Industries Limited
- 6.3.6 EPACK Prefab Technologies Limited
- 6.3.7 Jindal Buildsys Limited
- 6.3.8 PEB Steel Buildings Co., Ltd.
- 6.3.9 Zamil Steel Holding Company
- 6.3.10 Tiger Steel Engineering LLC
- 6.3.11 Larsen & Toubro Limited
- 6.3.12 ATAD Steel Structure Corporation
- 6.3.13 Butler Manufacturing Company
- 6.3.14 Nucor Building Systems
- 6.3.15 Kirby International
- 6.3.16 Multicolor Steels Private Limited
- 6.3.17 SML Group
- 6.3.18 Era Infra Engineering Limited
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

