PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187369

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187369
India Cold Chain Logistics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the India cold chain logistics market size is expected to increase from USD 24.85 billion in 2026 to USD 26.32 billion in 2027 and reach USD 35.46 billion by 2032, growing at a CAGR of 6.14% over 2027-2032.
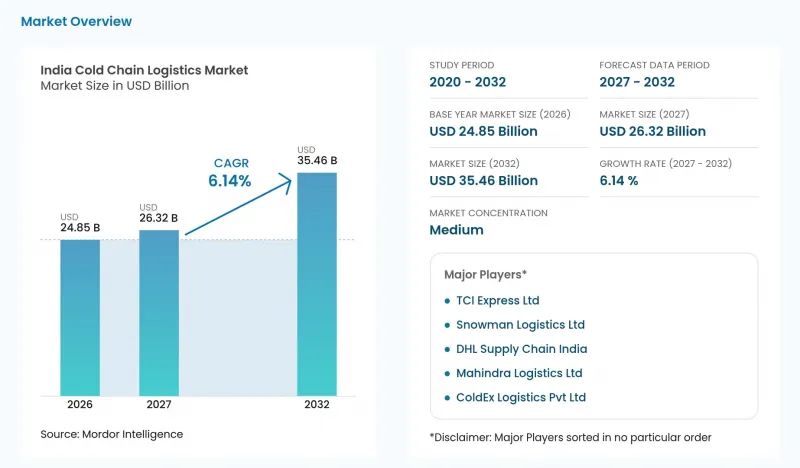
This report is segmented by Service Type (Refrigerated Storage, Refrigerated Transportation, and more), Temperature Type (Frozen, Chilled, and more), Application (Dairy & Frozen Desserts, Fruits & Vegetables, and more), and Geography (West India, North India, and more). The market forecasts are provided in terms of value (USD), based on availability.
India Cold Chain Logistics Market Trends and Insights
Expansion of Organized Retail & Frozen FMCG Distribution
Retail expansion supports refrigerated distribution when growing product flows reach a larger network of outlets equipped to hold frozen goods. NielsenIQ reported that India's modern-trade FMCG sales volume rose 17.5% year over year in April-June 2026. Krishival Foods expanded its retail deep-freezer network for Melt N Mellow ice cream from 3,732 units at the start of FY2026 to 15,490 by March 31, 2026. Its distribution footprint included distributors across Maharashtra, Karnataka, Goa, Telangana and Andhra Pradesh. Each additional retail freezer creates a destination to replenish, extending refrigerated delivery work for ice cream distributors across the enlarged selling network.
Government Support via PMKSY's Integrated Cold Chain and Value Addition Infrastructure Scheme
Government support is most useful when it finances linked stages that an isolated refrigerated warehouse cannot provide. As of June 30, 2026, the Ministry of Food Processing Industries reported 409 approved projects and 311 completed or operational projects under its Integrated Cold Chain and Value Addition Infrastructure scheme. The scheme links farm-level preparation with storage, packing, freezing and refrigerated distribution for horticultural and non-horticultural produce, fish and marine products except shrimp, dairy, meat and poultry. That design allows eligible project implementers to address connections between product handling and onward movement rather than treating storage as the entire service. Completed facilities create an opening for complementary transport and handling, while service capacity tied to the approval pipeline must follow actual project implementation.
High Upfront Capital Expenditure for Cold Chain Assets
Cold-chain expansion requires an investment case that can attract finance beyond the support available from grants. Grant Thornton Bharat's October 2026 assessment said grants alone could not meet the estimated capital requirement for India's missing cold-chain distribution infrastructure. It said asset bankability would depend on multi-commodity facilities, complementary seasonal demand, contracted utilization and anchor offtake from processors, retailers or exporters. Where a proposed facility cannot secure the finance that grants leave uncovered, construction may have to wait, postponing additional distribution capacity.
Other drivers and restraints analyzed in the detailed report include:
- Rising Pharmaceutical & Vaccine Cold Supply Chain Demand
- Growth of E-Commerce Grocery & Frozen Food Delivery
- Limited Cold Storage Penetration in Tier-3 and Rural Areas
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Refrigerated storage accounted for a 41.16% share of the India cold chain logistics market size in 2026. India had 8,831 cold storages with combined capacity of 40.29 million metric tons as of January 31, 2026. The national capacity figure measures physical storage, while the segment share measures service revenue. Storage providers can expand recurring revenue by securing contracted use of this installed base, giving customer throughput commercial importance alongside further facility construction.
Value-added services are forecast to be the fastest-growing segment, with a CAGR of 6.6% over 2027-2032. During FY 2025-26, Snowman Logistics Ltd, a Gateway Distriparks Limited subsidiary, offered location-specific value-added services tailored to clients across its network. Location-specific customization gives providers a route to earn from handling work shaped by an individual customer's product flow. The operating implication is that a network can support different service packages at different locations while retaining a common customer relationship. The resulting expansion path is deeper service provision within an existing footprint, so growth need not depend entirely on adding refrigerated warehouse space.
Complete Report Scope:
- By Service Type
- Refrigerated Storage
- Public Warehousing
- Private Warehousing
- Refrigerated Transportation
- Road
- Rail
- Sea
- Air
- Value-Added Services
- Refrigerated Storage
- By Temperature Type
- Chilled (0 - 5 °C)
- Frozen (-18 - 0 °C)
- Ambient
- Deep-Frozen / Ultra-Low (less than -20 °C)
- By Application
- Fruits & Vegetables
- Meat & Poultry
- Fish & Seafood
- Dairy & Frozen Desserts
- Bakery & Confectionery
- Ready-to-Eat Meals
- Pharmaceuticals & Biologics
- Vaccines & Clinical Trial Materials
- Chemicals & Specialty Materials
- Other Perishables
- By Geography
- North India
- Delhi-NCR
- Punjab
- Haryana
- Others
- South India
- Karnataka
- Tamil Nadu
- Telangana
- West India
- Maharashtra
- Gujarat
- East India
- West Bengal
- Odisha
- Central India
- Madhya Pradesh
- Chhattisgarh
- North India
List of Companies Covered in this Report:
- Snowman Logistics Ltd
- ColdEx Logistics Pvt Ltd
- TCI Express Ltd
- DHL Supply Chain India
- Mahindra Logistics Ltd
- Gubba Cold Storage Ltd
- Cold Star Logistics Pvt Ltd
- CONCOR Cold Chain Logistics
- Crystal Logistic Cool Chain Ltd
- R. K. Foodland Pvt Ltd
- Indraprastha Cold Storage
- Arihant Cold Storage
- Godamwale
- Siddhi Cold Chain
- Coldrush Logistics
- Coldman Warehousing & Distribution
- Indicold Private Limited
- GK Cold Chain Solutions
- Transworld
- CEVA Logistics (Stellar Value Chain Solutions Pvt Ltd)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Organized Retail & Frozen FMCG Distribution
- 4.2.2 Government Support via PMKSY's Integrated Cold Chain and Value Addition Infrastructure Scheme
- 4.2.3 Rising Pharmaceutical & Vaccine Cold Supply Chain Demand
- 4.2.4 Growth of E-Commerce Grocery & Frozen Food Delivery
- 4.2.5 Adoption of IoT & Real-Time Temperature Monitoring
- 4.2.6 Increasing Perishable Exports to Middle East & Southeast Asia
- 4.3 Market Restraints
- 4.3.1 High Upfront Capital Expenditure for Cold Chain Assets
- 4.3.2 Limited Cold Storage Penetration in Tier-3 and Rural Areas
- 4.3.3 Seasonal Demand Fluctuations Leading to Under-Utilization
- 4.3.4 Spoilage Risks from Temperature Excursions During Transit
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Refrigerated Storage
- 5.1.1.1 Public Warehousing
- 5.1.1.2 Private Warehousing
- 5.1.2 Refrigerated Transportation
- 5.1.2.1 Road
- 5.1.2.2 Rail
- 5.1.2.3 Sea
- 5.1.2.4 Air
- 5.1.3 Value-Added Services
- 5.1.1 Refrigerated Storage
- 5.2 By Temperature Type
- 5.2.1 Chilled (0 - 5 °C)
- 5.2.2 Frozen (-18 - 0 °C)
- 5.2.3 Ambient
- 5.2.4 Deep-Frozen / Ultra-Low (less than -20 °C)
- 5.3 By Application
- 5.3.1 Fruits & Vegetables
- 5.3.2 Meat & Poultry
- 5.3.3 Fish & Seafood
- 5.3.4 Dairy & Frozen Desserts
- 5.3.5 Bakery & Confectionery
- 5.3.6 Ready-to-Eat Meals
- 5.3.7 Pharmaceuticals & Biologics
- 5.3.8 Vaccines & Clinical Trial Materials
- 5.3.9 Chemicals & Specialty Materials
- 5.3.10 Other Perishables
- 5.4 By Geography
- 5.4.1 North India
- 5.4.1.1 Delhi-NCR
- 5.4.1.2 Punjab
- 5.4.1.3 Haryana
- 5.4.1.4 Others
- 5.4.2 South India
- 5.4.2.1 Karnataka
- 5.4.2.2 Tamil Nadu
- 5.4.2.3 Telangana
- 5.4.3 West India
- 5.4.3.1 Maharashtra
- 5.4.3.2 Gujarat
- 5.4.4 East India
- 5.4.4.1 West Bengal
- 5.4.4.2 Odisha
- 5.4.5 Central India
- 5.4.5.1 Madhya Pradesh
- 5.4.5.2 Chhattisgarh
- 5.4.1 North India
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Snowman Logistics Ltd
- 6.4.2 ColdEx Logistics Pvt Ltd
- 6.4.3 TCI Express Ltd
- 6.4.4 DHL Supply Chain India
- 6.4.5 Mahindra Logistics Ltd
- 6.4.6 Gubba Cold Storage Ltd
- 6.4.7 Cold Star Logistics Pvt Ltd
- 6.4.8 CONCOR Cold Chain Logistics
- 6.4.9 Crystal Logistic Cool Chain Ltd
- 6.4.10 R. K. Foodland Pvt Ltd
- 6.4.11 Indraprastha Cold Storage
- 6.4.12 Arihant Cold Storage
- 6.4.13 Godamwale
- 6.4.14 Siddhi Cold Chain
- 6.4.15 Coldrush Logistics
- 6.4.16 Coldman Warehousing & Distribution
- 6.4.17 Indicold Private Limited
- 6.4.18 GK Cold Chain Solutions
- 6.4.19 Transworld
- 6.4.20 CEVA Logistics (Stellar Value Chain Solutions Pvt Ltd)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

