PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187380

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187380
Electronics Manufacturing Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the electronics manufacturing services market size is estimated at USD 663.3 billion in 2026 and is projected to be USD 706.5 billion in 2027, reaching USD 983.5 billion by 2032, growing at a CAGR of 6.84% from 2027 to 2032.
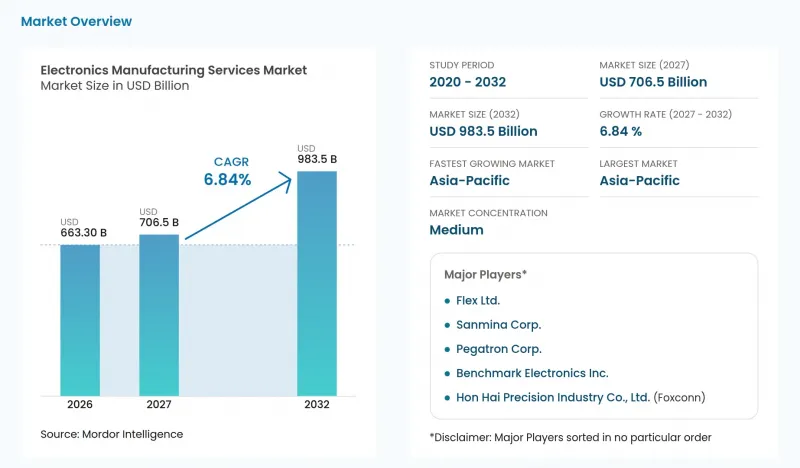
This report is segmented by Service (Electronic Manufacturing Services and more), Business Model (Contract Manufacturing and more), Manufacturing Process (Surface Mount Technology and more), End-user (Consumer Electronics and more), and Geography (Asia-Pacific and more). The market forecasts are provided in terms of value (USD), based on availability.
Global Electronics Manufacturing Services Market Trends and Insights
OEMs Outsourcing to Focus on Core Competencies
OEM demand for specialist assembly creates recurring opportunities as customers and production programs change. Kimball Electronics said OEMs continue to subcontract assembly to companies with a core competency in the area. It identified the trend as a growth factor for its electronics manufacturing and contract development and manufacturing industries. It also said new customer relationships and programs frequently begin as expiring programs are replaced. New customer assignments must replace expiring programs before they can enlarge a supplier's recurring assembly base, making program renewal central to converting outsourcing activity into sustained revenue.
Accelerated Near-/Re-shoring of Supply Chains to Mexico, Eastern Europe and ASEAN
Regional manufacturing becomes more useful to OEMs when additional space also enables a broader production engagement. On February 10, 2025, Federal Electronics reported expanding its Hermosillo, Sonora, Mexico facility from 30,000 square feet to more than 80,000 square feet. The EMS provider said it expanded the site to support growing customer demand and further increase vertical integration in the region. The Hermosillo expansion adds vertical integration at one site, so an OEM can concentrate more of its Mexican assembly with one supplier.
Rising Semiconductor and Passive Component Cost Volatility
Component availability can constrain an EMS provider's delivery commitment even when customers are ready to place production work. Kimball Electronics said EMS firms experienced shortages, allocations and shipping delays, particularly for semiconductors, in recent fiscal years, and further disruptions could raise component costs and interrupt operations. In July 2026, Plexus CFO David Abuhl said its supply chain was tightening, with tight spots in some components. Abuhl said Plexus was coordinating component forecasts with customers and acting to get ahead of selected components. A production commitment can remain unfilled when selected components are unavailable, leaving the EMS provider exposed to delivery delays and additional component costs.
Other drivers and restraints analyzed in the detailed report include:
- Surge in EV Power-Electronics Requiring Advanced PCB Assembly Capabilities
- Proliferation of IIoT Edge Devices Driving HDI and Advanced Packaging EMS Demand
- IP Protection Concerns Limiting Outsourcing in EU Aerospace and Defense
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Electronic manufacturing services accounted for a 71.98% share of the electronics manufacturing services market size in 2026, making it the largest segment. Flex, a manufacturing partner also providing supply-chain solutions, products, technology, and lifecycle services, reported company-wide fiscal 2026 net sales of USD 27.9 billion, up 8% from fiscal 2025. OEMs can approach a manufacturing business at this scale for production work within an organization offering several related capabilities. Manufacturing can anchor a customer relationship that continues into product support, connecting the core production contract with the additional lifecycle services offered by the provider.
Test and development implementation is the fastest-growing segment, with a projected CAGR of 7.3% from 2027 to 2032. Creation Technologies held the ribbon-cutting for its 40% expansion of the Denver Product Realization Center on May 12, 2025, bringing the facility's footprint to 45,000 square feet. The expanded space supports engineering services, test development, and manufacturing, with a focus on quick-turn prototypes and small-batch production. Co-locating these tasks can connect the development of a test approach with the manufacturing work it must support. Because test development and small-batch production share one Denver site, a customer can move a quick-turn prototype into production without changing facilities.
Contract manufacturing (CM) represented a 62.32% electronics manufacturing services market share in 2026, making it the largest segment. Flex announced an expanded Cerebras Systems manufacturing partnership in July 2026, with new Milpitas, California, lines expected to increase CS-3 production capacity by approximately 7x through 2026. The announced expansion combined production lines, floor space, advanced test infrastructure, and skilled manufacturing talent. Flex's expansion concentrates added lines, test infrastructure, and manufacturing talent on the CS-3, tying the contractor's new capacity to this customer's AI system.
Hybrid, turnkey, and other business models form the fastest-growing segment, with a projected CAGR of 7.4% from 2027 to 2032. In fiscal 2025, Jabil said it procured components and other materials for its turnkey manufacturing services. This puts input procurement and production execution within the provider's commercial responsibility for the engagement. For an OEM, assigning both tasks to its manufacturing counterparty offers a way to organize the materials and production work together. Procurement can broaden Jabil's delivery responsibility without adding the full component value to revenue when customer-directed components receive net accounting because it does not obtain control before transfer.
Complete Report Scope:
- By Service
- Electronic Manufacturing Services
- PCB Assembly
- Electromechanical Assembly/Box Build
- Prototyping
- Other Electronic Manufacturing Services
- Engineering Services
- Test and Development Implementation
- Logistics Services
- Other Services
- Electronic Manufacturing Services
- By Business Model
- Contract Manufacturing (CM)
- Original Design Manufacturing (ODM)
- Hybrid / Turnkey / Other Business Models
- By Manufacturing Process
- Surface Mount Technology (SMT)
- Through-Hole Technology (THT)
- Advanced Packaging / Hybrid Processes
- By End-user
- Mobile Devices (Smartphones and Tablets)
- Consumer Electronics
- Computer (PCs/Desktop/Laptops)
- Industrial
- Automotive
- Communication
- Lighting
- Medical
- Other End-users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- South-east Asia
- Rest of Asia-Pacific
- South America
- Middle East and Africa
- North America
Geography Analysis
Asia-Pacific accounted for 56.67% of the electronics manufacturing services market size in 2026 and is the fastest-growing region, with a projected CAGR of 7.2% from 2027 to 2032. India's electronics goods production value increased 15.8% in FY 2025-26 from FY 2024-25, according to the Press Information Bureau. Jabil's Ranjangaon, Pune, facility was inaugurated on June 17, 2026, with capabilities for AI data-center systems, 5G, high-end networking, industrial power-system electronics, and consumer electronics. Taiwan's supplier base includes Kentec's Taoyuan EMS facility, which began operations in 2025 with R&D, smart manufacturing, testing, and logistics as a Kenmec Group hub. India's output growth and Jabil's Pune plant show expanding manufacturing capacity in the region, while Kentec's Taoyuan hub connects R&D and testing with production at one supplier.
North America and Europe present different program opportunities because planned infrastructure manufacturing and existing automotive exposure imply different capacity decisions. In June 2025, Jabil announced plans for a Rowan County, North Carolina, facility for cloud and AI data-center customers, with approximately USD 500 million in investment and 1,181 expected jobs. The Global Electronics Association's 2025 survey covered 397 companies representing nearly 31% of European EMS production. Surveyed European EMS companies reported a 2.9% revenue decline, with the steepest drops in automotive-focused countries and greater resilience in the Baltics, Poland, the Balkans, and the Nordics. Jabil's planned Rowan County site ties North American capacity to AI data-center customers, while Europe's steepest 2025 revenue declines came in automotive-focused countries such as Austria, France, and Germany.
South America offers established local production operations through which electronics manufacturers can serve specific product programs. In September 2025, Jundiai's city government reported that Foxconn's 2 local plants made notebooks and electronic boards and were the sole producer of Apple devices in Brazil. Within the Middle East and Africa, Cicor completed its acquisition of Valtronic's Berrechid, Morocco site on November 14, 2025, bringing medical and diagnostic device manufacturing into its Electronic Manufacturing Services Division. Foxconn's Jundiai plants anchor notebook and electronic-board assembly in Brazil, while Cicor's Berrechid purchase gave its EMS division medical and diagnostic device production capacity in Morocco.
- Hon Hai Precision Industry Co., Ltd. (Foxconn)
- Pegatron Corp.
- Flex Ltd.
- Jabil Inc.
- Luxshare Precision Industry Co., Ltd.
- Wistron Corp.
- Sanmina Corp.
- Celestica Inc.
- Benchmark Electronics Inc.
- Plexus Corp.
- Compal Electronics Inc.
- Inventec Corp.
- Universal Scientific Industrial Co., Ltd. (USI)
- BYD Electronic (International) Co., Ltd.
- Shenzhen Kaifa Technology Co., Ltd.
- Asteelflash Group
- Kimball Electronics Inc.
- Sumitronics Corp.
- Nortech Systems Inc.
- Creation Technologies Ltd.
- Integrated Micro-Electronics Inc.
- Zollner Elektronik AG
- New Kinpo Group (Cal-Comp)
- SIIX Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 OEMs Outsourcing to Focus on Core Competencies
- 4.2.2 Accelerated Near-/Re-shoring of Supply Chains to Mexico, Eastern Europe and ASEAN
- 4.2.3 Surge in EV Power-Electronics Requiring Advanced PCB Assembly Capabilities
- 4.2.4 Proliferation of IIoT Edge Devices Driving HDI and Advanced Packaging EMS Demand
- 4.2.5 Government Production-Linked Incentives in India and Tax Incentives in Vietnam for Domestic EMS Facilities
- 4.2.6 AI-Driven Digital MES Improving First-Pass Yield and Reducing Rework Costs
- 4.3 Market Restraints
- 4.3.1 Rising Semiconductor and Passive Component Cost Volatility
- 4.3.2 IP Protection Concerns Limiting Outsourcing in EU Aerospace and Defense
- 4.3.3 Competition from ODMs and OEM In-house Lines in Smartphones
- 4.3.4 Environmental Compliance (RoHS, REACH) Raising Capex for Legacy Facilities
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service
- 5.1.1 Electronic Manufacturing Services
- 5.1.1.1 PCB Assembly
- 5.1.1.2 Electromechanical Assembly/Box Build
- 5.1.1.3 Prototyping
- 5.1.1.4 Other Electronic Manufacturing Services
- 5.1.2 Engineering Services
- 5.1.3 Test and Development Implementation
- 5.1.4 Logistics Services
- 5.1.5 Other Services
- 5.1.1 Electronic Manufacturing Services
- 5.2 By Business Model
- 5.2.1 Contract Manufacturing (CM)
- 5.2.2 Original Design Manufacturing (ODM)
- 5.2.3 Hybrid / Turnkey / Other Business Models
- 5.3 By Manufacturing Process
- 5.3.1 Surface Mount Technology (SMT)
- 5.3.2 Through-Hole Technology (THT)
- 5.3.3 Advanced Packaging / Hybrid Processes
- 5.4 By End-user
- 5.4.1 Mobile Devices (Smartphones and Tablets)
- 5.4.2 Consumer Electronics
- 5.4.3 Computer (PCs/Desktop/Laptops)
- 5.4.4 Industrial
- 5.4.5 Automotive
- 5.4.6 Communication
- 5.4.7 Lighting
- 5.4.8 Medical
- 5.4.9 Other End-users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 South Korea
- 5.5.3.4 India
- 5.5.3.5 South-east Asia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.5 Middle East and Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Hon Hai Precision Industry Co., Ltd. (Foxconn)
- 6.4.2 Pegatron Corp.
- 6.4.3 Flex Ltd.
- 6.4.4 Jabil Inc.
- 6.4.5 Luxshare Precision Industry Co., Ltd.
- 6.4.6 Wistron Corp.
- 6.4.7 Sanmina Corp.
- 6.4.8 Celestica Inc.
- 6.4.9 Benchmark Electronics Inc.
- 6.4.10 Plexus Corp.
- 6.4.11 Compal Electronics Inc.
- 6.4.12 Inventec Corp.
- 6.4.13 Universal Scientific Industrial Co., Ltd. (USI)
- 6.4.14 BYD Electronic (International) Co., Ltd.
- 6.4.15 Shenzhen Kaifa Technology Co., Ltd.
- 6.4.16 Asteelflash Group
- 6.4.17 Kimball Electronics Inc.
- 6.4.18 Sumitronics Corp.
- 6.4.19 Nortech Systems Inc.
- 6.4.20 Creation Technologies Ltd.
- 6.4.21 Integrated Micro-Electronics Inc.
- 6.4.22 Zollner Elektronik AG
- 6.4.23 New Kinpo Group (Cal-Comp)
- 6.4.24 SIIX Corp.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

