PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114041

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114041
Combine Harvester - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the combine harvester market size in 2026 is estimated at USD 12.74 billion, growing from 2025 value of USD 12.10 billion with 2031 projections showing USD 16.48 billion, growing at 5.28% CAGR over 2026-2031.
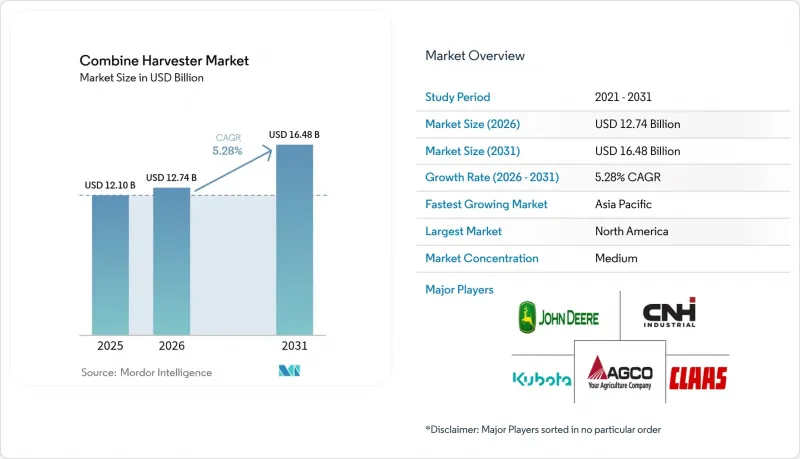
This report is Segmented by Type (Self-Propelled, Tractor-Pulled Combine, and PTO-Powered Combine), by Power Output (Less Than 150 HP, 151 To 300 HP, 301 To 450 HP, and Above 450 HP), and by Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Combine Harvester Market Trends and Insights
Rising Farm Mechanization in Emerging Economies
Government grants and custom-hiring hubs continue to widen equipment access. India's Sub-Mission on Agricultural Mechanization reimburses 40-50% of purchase costs and has deployed more than 40,900 rental centers, lifting mechanization from 40% toward China's 60% benchmark . China's policy goal of 75% mechanization by 2025 attracts multinational suppliers into joint ventures that sidestep import tariffs . Similar subsidy schemes in Brazil and multiple African nations illustrate a structural push that enlarges the combine harvester market.
Persistent Rural Labor Shortage and Wage Inflation
Unemployment rates below 3% in many grain-producing regions have driven farm wages to record highs, narrowing the payback window for autonomous threshing platforms. Large United States growers now cite workforce scarcity as the primary justification for migrating to high-horsepower combines configured for one-operator, multi-shift deployment. Western Europe mirrors this tension, with dairy and arable producers trimming acreage whenever harvest labor cannot be secured in time. This labor scarcity is particularly acute during harvest seasons when timing is critical, driving demand for high-capacity combines that can maximize operational windows with minimal human intervention.
High Upfront Capital Requirement
New flagship frequently lists between USD 400,000 and USD 500,000. Elevated interest rates push annual carrying costs per unit, lengthening break-even periods even for well-capitalized farms. Although leasing and operating-rent contracts soften the blow, smaller growers still postpone purchases, slowing near-term combine harvester market growth. AGCO's strategic focus on OEM financing solutions and John Deere's expansion of financing capabilities in Brazil demonstrate manufacturers' recognition that equipment accessibility depends increasingly on innovative payment structures rather than traditional purchase models.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of Precision-Ag Mechanization Suites
- Integration of AI-Enabled Predictive Maintenance
- Limited Aftermarket Service Networks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The self-propelled segment generated a 71.35% market share in the combine harvester market in 2025, underscoring its primacy in high-acreage operations. Tractor-pulled variants alone are projected to lift the segment's CAGR to 7.35% through 2031 as dual-flow threshing boosts grain retention. PTO-powered combine remain viable among cost-sensitive growers, but ongoing autonomy retrofits are beginning to blur the lines between legacy categories. The Tractor-pulled combine endures in cost-sensitive or fragmented landholdings, especially where capital pools are modest. Manufacturers refine hybrid drivelines that reduce fuel consumption by up to 10%, increasing the appeal for operators who must juggle diesel, AdBlue, and maintenance costs.
Fleet owners prefer self-propelled platforms due to their tight turning radius, integrated telematics, and compatibility with 12- to 18-row headers. OEMs now release over-the-air firmware that tunes concave clearance and rotor speed to crop moisture, squeezing extra throughput from existing horsepower bands. As adherence to future compaction rules tightens, articulated undercarriages and wide-track options are gaining traction within this leading segment of the combine harvester market. The segment's innovation pipeline centers on the expansion of the combined harvesters market size through autonomous modules that enable a single driver to supervise multiple units across adjacent fields.
Complete Report Scope:
- By Type
- Self-propelled
- Tractor-pulled combine
- PTO-powered combine
- By Power Output (HP)
- Less than 150 HP
- 151 to 300 HP
- 301 to 450 HP
- Above 450 HP
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Spain
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America retained 31.85% revenue in 2025, reflecting deep mechanization and entrenched replacement cycles. Capital spending nonetheless softened as growers braced for a predicted dip in large-equipment deliveries during 2025. Federal aid earmarked for climate-smart agriculture may cushion orders in the latter half of the year, especially for combines outfitted with residue-balancing kits that qualify for soil-health grants. Canada's agricultural sector benefits from strong grain export demand and government support for the adoption of precision agriculture, while Mexico's growing agricultural mechanization presents opportunities for expansion for North American manufacturers.
Asia-Pacific leads growth at an 7.85% CAGR through 2031. India's mechanization gap has narrowed swiftly. Subsidy-backed custom-hiring centers now finance threshing sessions for smallholders who cannot yet buy machines outright. China's 75% mechanization target propels demand for domestically assembled high-end combines that avoid import tariffs while retaining foreign sensor suites. Japan and Australia represent mature markets with a focus on precision agriculture and automation technologies, while Southeast Asian countries present emerging opportunities as agricultural productivity demands increase.
Europe's market cools amid input-cost inflation and stricter environmental mandates. The EU Machinery Regulation 2023/1230 sets new guardrails for autonomous safety validation, raising R&D budgets for compliance. In contrast, Brazil and Argentina ride export-led cash flows that fund upgrades to 350 HP-plus combines equipped with telematics pods that simplify fleet optimization. South America benefits from a strong agricultural export performance, with Brazil's record sugarcane processing of 713 million tons in 2023 supporting equipment demand, while Argentina's agricultural biotechnology leadership creates opportunities for precision agriculture integration.
- Deere & Company
- CNH Industrial N.V.
- AGCO Corporation
- Claas KGaA mbH
- Kubota Corporation
- SDF Group
- Jiangsu World Agricultural Machinery (World Group)
- Yanmar Holdings Co., Ltd.
- Mahindra and Mahindra Ltd. (Mahindra Group)
- Iseki and Co., Ltd.
- Versatile (Buhler Industries)
- Rostselmash
- Tractors and Farm Equipment Ltd. (Amalgamations Group)
- LOVOL Heavy Industry (Weichai Group)
- Zoomlion Heavy Industry Science and Technology
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising farm mechanization in emerging economies
- 4.2.2 Persistent rural labor shortage and wage inflation
- 4.2.3 Adoption of precision ag mechanization suites
- 4.2.4 Integration of AI-enabled predictive maintenance
- 4.2.5 Carbon-credit monetization for low-loss harvesting
- 4.2.6 OEM financing platforms targeting smallholders
- 4.3 Market Restraints
- 4.3.1 High upfront capital requirement
- 4.3.2 Limited aftermarket service networks
- 4.3.3 Dependence on volatile commodity crop pricing
- 4.3.4 Rapid soil-compaction regulations
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Self-propelled
- 5.1.2 Tractor-pulled combine
- 5.1.3 PTO-powered combine
- 5.2 By Power Output (HP)
- 5.2.1 Less than 150 HP
- 5.2.2 151 to 300 HP
- 5.2.3 301 to 450 HP
- 5.2.4 Above 450 HP
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.1.4 Rest of North America
- 5.3.2 South America
- 5.3.2.1 Brazil
- 5.3.2.2 Argentina
- 5.3.2.3 Rest of South America
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 France
- 5.3.3.3 United Kingdom
- 5.3.3.4 Spain
- 5.3.3.5 Italy
- 5.3.3.6 Russia
- 5.3.3.7 Rest of Europe
- 5.3.4 Asia-Pacific
- 5.3.4.1 China
- 5.3.4.2 India
- 5.3.4.3 Japan
- 5.3.4.4 Australia
- 5.3.4.5 Rest of Asia-Pacific
- 5.3.5 Middle East
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 Turkey
- 5.3.5.3 Rest of Middle East
- 5.3.6 Africa
- 5.3.6.1 South Africa
- 5.3.6.2 Egypt
- 5.3.6.3 Rest of Africa
- 5.3.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Deere & Company
- 6.4.2 CNH Industrial N.V.
- 6.4.3 AGCO Corporation
- 6.4.4 Claas KGaA mbH
- 6.4.5 Kubota Corporation
- 6.4.6 SDF Group
- 6.4.7 Jiangsu World Agricultural Machinery (World Group)
- 6.4.8 Yanmar Holdings Co., Ltd.
- 6.4.9 Mahindra and Mahindra Ltd. (Mahindra Group)
- 6.4.10 Iseki and Co., Ltd.
- 6.4.11 Versatile (Buhler Industries)
- 6.4.12 Rostselmash
- 6.4.13 Tractors and Farm Equipment Ltd. (Amalgamations Group)
- 6.4.14 LOVOL Heavy Industry (Weichai Group)
- 6.4.15 Zoomlion Heavy Industry Science and Technology
7 Market Opportunities and Future Outlook

