PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122787

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122787
India Combine Harvester - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the India combine harvester market size was valued at USD 275.4 million in 2025 and estimated to grow from USD 290.94 million in 2026 to reach USD 382.76 million by 2031, at a CAGR of 5.64% during the forecast period (2026-2031).
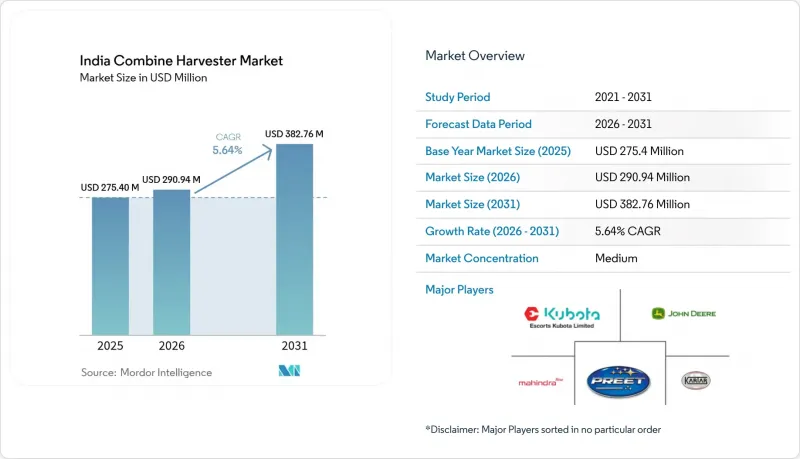
This report is Segmented by Type (Self-Propelled Combine Harvester, Track Combine Harvester, and Tractor-Powered Combine Harvester), Power Rating (Below 150 HP, 150 To 300 HP, and Above 300 HP), Crop Type (Wheat, Rice, Corn, and Other Crops), and Drive Mechanism (Wheel Drive and Track Drive). The Market Forecasts are Provided in Terms of Value (USD).
India Combine Harvester Market Trends and Insights
Rising area under grain crops
Area cover under foodgrains reached 1,321.04 lakh hectares during 2023-2024 from 1,301.69 lakh hectares during 2021-2022. Larger fields and tighter harvest windows motivate growers to adopt combine harvesters that can clear crops within optimal moisture thresholds, thereby minimizing post-harvest losses. Central schemes such as the National Food Security Mission promote high-yield seed varieties, indirectly boosting machine demand by raising per-acre output targets. State governments are simultaneously incentivizing mechanized residue management to combat stubble burning, making combines equipped with straw-handling attachments particularly attractive. As acreage under maize, pulses, and oilseeds widens, manufacturers are introducing multi-crop headers to serve mixed-farming zones. The resulting diversity in crop profiles reinforces sustained, geographically dispersed growth for the India combine harvester market.
Government subsidies for mechanization
Under the Sub-Mission on Agricultural Mechanization (SMAM), the federal and state governments reimburse 40-50% of the equipment purchase price. The Digital Agriculture Mission earmarks INR 2,817 crore (USD 339.4 million) to streamline subsidy delivery via an electronic farm identity stack, cutting approval time and leakage. The Kisan Credit Card program offers low-interest loans up to INR 500,000 (USD 6,024) for machinery purchases, easing capital hurdles for smallholders. Several states layer additional incentives, Karnataka co-funds public-private CHCs, while Punjab subsidizes Happy Seeder-ready combines to curb paddy-straw burning. Combined, these instruments reduce payback periods on new harvesters from five seasons to three, decisively energizing the India combine harvester market.
High upfront cost of machines
A mid-range self-propelled harvester retails for INR 2.2 million (USD 26,506), an investment beyond the reach of most smallholders. Even with a 50% capital subsidy, the remaining payment often surpasses annual farm income, forcing reliance on rental models. Finance houses perceive higher default risk for equipment loans because collateral recovery is complex in geographically dispersed villages. Although the Kisan Credit Card offers subsidized rates, only 61% of eligible farmers held active cards in 2024, limiting immediate cash-flow relief. Limited uptake of crop insurance further compounds lenders' risk perception. Consequently, ownership concentrates among larger farmers and CHC operators, tempering unit-sales momentum for the India combine harvester market.
Other drivers and restraints analyzed in the detailed report include:
- Precision-ag retrofit kits for aging fleets
- Growing harvester-as-a-service models
- Fragmented and small land holdings
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Self-propelled units generated 55.68% of 2025 revenue, underscoring their appeal among medium-to-large farms for all-crop versatility and standalone mobility. Buyers value integrated engines, larger grain tanks, and operator comfort during extended harvest windows, making these machines the benchmark for productivity. Tractor-powered combine harvesters remain prevalent in lower-mechanization districts, leveraging existing 50-70 HP tractor fleets to reduce capital outlay. Track combines, though niche, solve traction issues in waterlogged paddy areas and appear in government procurement lists for climate-resilient mechanization, especially in coastal Andhra Pradesh.
Looking forward, self-propelled sales are positioned to expand at a 7.04% CAGR, benefiting from Stage V emission mandates that favor new-technology adoption. OEMs integrate GNSS auto-steer, 4G telematics, and straw chopper attachments, elevating price points and average revenue per unit. Field demonstrations by Mahindra & Mahindra Ltd. and Case IH's Axial-Flow series show 3-4% grain-loss reduction, justifying higher acquisition costs. This performance edge sustains their lead in the India combine harvester market.
Combines rated 150-300 HP accounted for 47.12% of 2025 sales, capturing the sweet spot between throughput and affordability. They handle multi-crop headers and traverse 4-6 hectare plots without extensive turnaround time, aligning well with India's farm-size spectrum. Below-150 HP machines still interest small CHCs but face limitations in grain-tank capacity and header width, slowing field progress. Above-300 HP models, despite commanding premium prices, are registering the fastest 7.32% CAGR because large-acreage farmers and corporate growers pursue machine hours aggregation.
Stage IV TREM (Transport Related Engine Emission Norms) compliance as of January 2023 nudged OEMs to redesign engines, increasing 175 HP-plus production runs. Custom-hiring entrepreneurs in Punjab and Madhya Pradesh gravitate toward these high-output machines to maximize rental income during brief harvest peaks. Consequently, power-rating choices directly steer fleet mix and revenue profiles in the India combine harvester market.
Complete Report Scope:
- By Type
- Self-propelled Combine Harvester
- Track Combine Harvester
- Tractor-powered Combine Harvester
- By Power Rating
- Below 150 HP
- 150 to 300 HP
- Above 300 HP
- By Crop Type
- Wheat
- Rice
- Corn
- Other Crops
- By Drive Mechanism
- Wheel Drive
- Track Drive
List of Companies Covered in this Report:
- Mahindra & Mahindra Ltd.
- Deere & Company
- PREET Group
- Tractors and Farm Equipment Limited
- Kartar Agro Industries Private Limited
- Dasmesh Group
- International Tractors Limited (Sonalika)
- Indo Farm Equipment Limited
- Yanmar Holdings Co., Ltd.
- CNH Industrial N.V.
- Escorts Kubota Limited
- Tirth Agro Technology Private Limited
- KS Agrotech PVT.LTD
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising area under grain crops
- 4.2.2 Escalating farm labor costs
- 4.2.3 Government subsidies for mechanization
- 4.2.4 Rapid growth of custom-hiring centers
- 4.2.5 Precision-ag retrofit kits for aging fleets
- 4.2.6 Growing availability of harvester-as-a-service models
- 4.3 Market Restraints
- 4.3.1 High upfront cost of machines
- 4.3.2 Fragmented and small land holdings
- 4.3.3 Expensive after-sales maintenance
- 4.3.4 Slow rural credit disbursement to small farmers
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Self-propelled Combine Harvester
- 5.1.2 Track Combine Harvester
- 5.1.3 Tractor-powered Combine Harvester
- 5.2 By Power Rating
- 5.2.1 Below 150 HP
- 5.2.2 150 to 300 HP
- 5.2.3 Above 300 HP
- 5.3 By Crop Type
- 5.3.1 Wheat
- 5.3.2 Rice
- 5.3.3 Corn
- 5.3.4 Other Crops
- 5.4 By Drive Mechanism
- 5.4.1 Wheel Drive
- 5.4.2 Track Drive
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Mahindra & Mahindra Ltd.
- 6.4.2 Deere & Company
- 6.4.3 PREET Group
- 6.4.4 Tractors and Farm Equipment Limited
- 6.4.5 Kartar Agro Industries Private Limited
- 6.4.6 Dasmesh Group
- 6.4.7 International Tractors Limited (Sonalika)
- 6.4.8 Indo Farm Equipment Limited
- 6.4.9 Yanmar Holdings Co., Ltd.
- 6.4.10 CNH Industrial N.V.
- 6.4.11 Escorts Kubota Limited
- 6.4.12 Tirth Agro Technology Private Limited
- 6.4.13 KS Agrotech PVT.LTD
7 Market Opportunities and Future Outlook

