PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117542

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117542
Europe Architectural Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Europe architectural services market is projected to grow from USD 84.33 billion in 2025 to USD 89.40 billion in 2026, reaching USD 114.76 billion by 2031, registering a CAGR of 5.12% during 2026-2031.
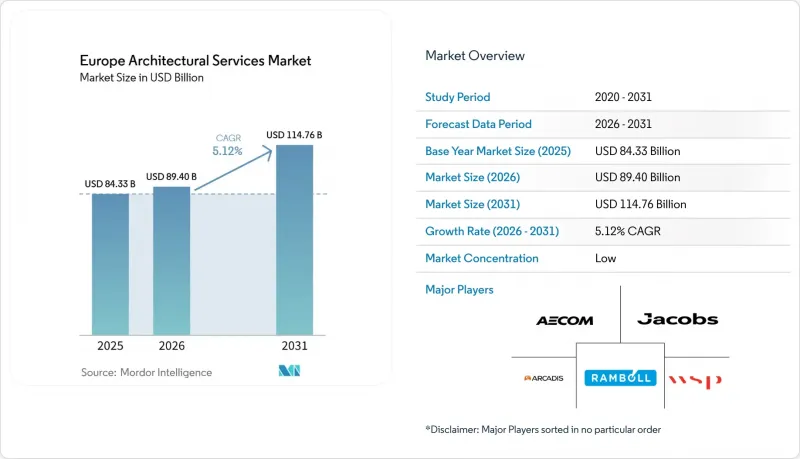
This report is Segmented by Service Type (Architectural Design Services, Architectural Documentation & Delivery Services, and More), Project Type (New Construction, Renovation), End-Use (Residential, Commercial, Infrastructure-Linked Buildings), Investment Source (Public, Private), and Geography (Germany, United Kingdom, France, and More). The Market Forecasts are Provided in Terms of Value (USD).
Europe Architectural Services Market Trends and Insights
Energy-Efficiency Retrofit Wave Across Aging Building Stock
The Europe architecture services market is seeing sustained retrofit demand because the recast EPBD requires member states to embed stricter minimum energy performance standards into national law by May 2026. The directive also requires the 16% worst-performing non-residential buildings to improve by 2030, which moves more building owners from discretionary renovation to compliance-led design. From January 2028, energy performance certificates for new large buildings must disclose life-cycle global warming potential, which pulls architects earlier into data gathering, carbon modeling, and specification work. This change strengthens the position of practices that have already built whole-life carbon capability, because they can offer both design and compliance support in the same commission. The Europe architecture services market is therefore drawing a larger share of demand from refurbishment, which is consistent with the Architects' Council of Europe finding that refurbishment already represented 49% of architects' workload in 2024.
Data Center, Life-Sciences, and Advanced Manufacturing Investment
The Europe architecture services market is drawing higher-value work from data centers, life sciences buildings, and advanced production campuses that need tighter engineering coordination and deeper permitting support than conventional office or retail jobs. In France, the planned digital infrastructure campus in Ile-de-France announced by Ardian and Verne shows how AI and cloud infrastructure are becoming direct sources of specialist design demand in the region. In the UK, HOK completed Merlin Place in Cambridge in June 2026 as a life sciences building with wet lab, dry lab, and computational functions, while also targeting BREEAM Excellent and whole-life net-zero carbon. These assignments are not easy entry points because they require coordination across the envelope, service integration, environmental review, phased construction, and specialist user needs. The Europe architecture services market is therefore seeing a wider fee gap between firms with specialist delivery credentials and firms that remain focused on standard commercial work.
High Labor and Professional Service Cost Base
The Europe architecture services market also remains constrained by a cost base that is rising faster than many firms can offset through productivity gains. Average architect pre-tax earnings reached EUR 43,500 in 2024, confirming that staffing costs are already high across the profession. The broader construction ecosystem could require 3.6 million additional workers by 2030, while FIEC stated that the European Union may need 2 million extra workers by the same year, suggesting a labor market that remains tight through the forecast period. Small and mid-sized firms are more exposed because they have less room to absorb wage pressure while clients remain fee-sensitive after recent inflation. The Europe architecture services market also faces a capacity issue as 20% of architects were aged 60 and above in 2024, which points to a gradual retirement-driven supply squeeze unless replacement improves.
Other drivers and restraints analyzed in the detailed report include:
- Public-Sector Decarbonization and Circularity Mandates
- Transit-Oriented Urban Regeneration and Mixed-Use Redevelopment
- Fragmented Planning and Building Compliance Regimes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Architectural Design Services accounted for 31% of the service-type mix in 2025, which gave them the largest position in the Europe architecture services market share for that year. This leadership reflects the way clients still appoint architecture firms first for concept design, early approvals, and project definition before more specialized delivery work widens around the brief. The segment also remains central to retrofit-led work, because energy upgrades, repositioning, and reuse projects still start with architectural redesign rather than with documentation alone. Documentation, delivery, and interior architecture remain important adjacent categories, especially where office refurbishment and mixed-use repositioning require detailed coordination across tenants, services, and phased occupation.
Urban Design and Master Planning Services are forecast to expand at a 6.9% CAGR through 2031, which makes them the fastest-growing service line in the Europe architecture services market. This pace aligns with the growing pipeline of urban regeneration, transit-linked redevelopment, and industrial land conversion projects that span several phases and involve multiple stakeholder groups. Digital readiness is becoming more important here, because the ACE study reported that 27% of practices used BIM in 2024 and 51% were using 3D modeling tools. Firms that built interoperable workflows are in a stronger position when clients ask for structured information management and wider consultant coordination.
Renovation represented 61% of the project-type mix in 2025, which means this segment accounted for the largest share of the Europe architecture services market size in that year. The segment reflects the economics of a region where older building stock, regulatory tightening, and occupancy upgrades are pushing owners toward refurbishment rather than replacement. That structure is also consistent with the ACE finding that refurbishment already formed 49% of architects' workload in 2024. Renovation work also tends to stay specification-heavy, because energy upgrades, carbon disclosure, access improvements, and tenant repositioning often need more coordination than cosmetic refreshes.
New Construction is forecast to grow at a 5.9% CAGR through 2031, which shows that the gap with renovation is narrowing in selected investment categories. The growth is coming less from broad office expansion and more from data centers, healthcare, life sciences, defense-related facilities, and major transport-linked developments. The ACE study also showed that private housing accounted for 54% of average practice turnover in 2024, which means many firms still depend on a project-based approach that moves with residential credit and household renovation appetite. Perkins&Will's approved GBP 125 million Oxford retrofit into a life sciences and planetary health hub in 2025 also shows how adaptive reuse now approaches new-build levels of technical design complexity.
Complete Report Scope:
- By Service Type
- Architectural Design Services
- Architectural Documentation and Delivery Services
- Interior Architecture and Space Planning Services
- Urban Design and Master Planning Services
- Others
- By Project Type
- New Construction
- Renovation
- By End-Use
- Residential
- Commercial
- Office
- Retail
- Institutional
- Industrial and Logistics
- Others
- Infrastructure-linked Buildings
- By Investment Source
- Public
- By Country
- Germany
- United Kingdom
- France
- Spain
- Italy
- Netherlands
- Sweden
- Denmark
- Norway
- Rest of Europe
List of Companies Covered in this Report:
- AECOM
- Jacobs Solutions Inc.
- Arcadis NV
- Ramboll Group A/S
- WSP Global Inc.
- Mott MacDonald Group Limited
- Foster + Partners LLP
- Gensler
- HOK
- Perkins and Will
- BDP Holdings Limited
- Sweco AB
- C.F. Moller Architects
- Norr Architects
- Chapman Taylor LLP
- Herzog and de Meuron
- AtkinsRealis Group Inc.
- Zaha Hadid Architects Limited
- Arup Group Limited
- Henn GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Energy-Efficiency Retrofit Wave Across Aging Building Stock
- 4.2.2 Data Center, Life-Sciences, and Advanced Manufacturing Investment
- 4.2.3 Public-Sector Decarbonization and Circularity Mandates
- 4.2.4 Transit-Oriented Urban Regeneration and Mixed-Use Redevelopment
- 4.2.5 Digital Design Adoption and Cross-Border Project Delivery
- 4.2.6 Hospitality and Cultural Asset Repositioning
- 4.3 Market Restraints
- 4.3.1 High Labor and Professional Service Cost Base
- 4.3.2 Fragmented Planning and Building Compliance Regimes
- 4.3.3 Slower Commercial Office Recovery in Selected Cities
- 4.3.4 Tight Public Procurement and Sustainability Verification Burden
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Industry Attractiveness - Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Pricing Analysis
- 4.9 Key Upcoming and Ongoing Projects
5 Market Size & Growth Forecasts (Value, in USD)
- 5.1 By Service Type
- 5.1.1 Architectural Design Services
- 5.1.2 Architectural Documentation and Delivery Services
- 5.1.3 Interior Architecture and Space Planning Services
- 5.1.4 Urban Design and Master Planning Services
- 5.1.5 Others
- 5.2 By Project Type
- 5.2.1 New Construction
- 5.2.2 Renovation
- 5.3 By End-Use
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.2.1 Office
- 5.3.2.2 Retail
- 5.3.2.3 Institutional
- 5.3.2.4 Industrial and Logistics
- 5.3.2.5 Others
- 5.3.3 Infrastructure-linked Buildings
- 5.4 By Investment Source
- 5.4.1 Public
- 5.5 By Country
- 5.5.1 Germany
- 5.5.2 United Kingdom
- 5.5.3 France
- 5.5.4 Spain
- 5.5.5 Italy
- 5.5.6 Netherlands
- 5.5.7 Sweden
- 5.5.8 Denmark
- 5.5.9 Norway
- 5.5.10 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 AECOM
- 6.4.2 Jacobs Solutions Inc.
- 6.4.3 Arcadis NV
- 6.4.4 Ramboll Group A/S
- 6.4.5 WSP Global Inc.
- 6.4.6 Mott MacDonald Group Limited
- 6.4.7 Foster + Partners LLP
- 6.4.8 Gensler
- 6.4.9 HOK
- 6.4.10 Perkins and Will
- 6.4.11 BDP Holdings Limited
- 6.4.12 Sweco AB
- 6.4.13 C.F. Moller Architects
- 6.4.14 Norr Architects
- 6.4.15 Chapman Taylor LLP
- 6.4.16 Herzog and de Meuron
- 6.4.17 AtkinsRealis Group Inc.
- 6.4.18 Zaha Hadid Architects Limited
- 6.4.19 Arup Group Limited
- 6.4.20 Henn GmbH
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment
- 7.2 Emerging Opportunities in Retrofit, Net-Zero, and Circular Design
- 7.3 Healthcare and Life-Sciences Campus Advisory Opportunities

