PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123147

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123147
Heavy Duty Trucks - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the heavy-duty trucks market size is expected to grow from USD 220.84 billion in 2025 to USD 232.57 billion in 2026 and is forecast to reach USD 301.23 billion by 2031 at a 5.31% CAGR over 2026-2031.
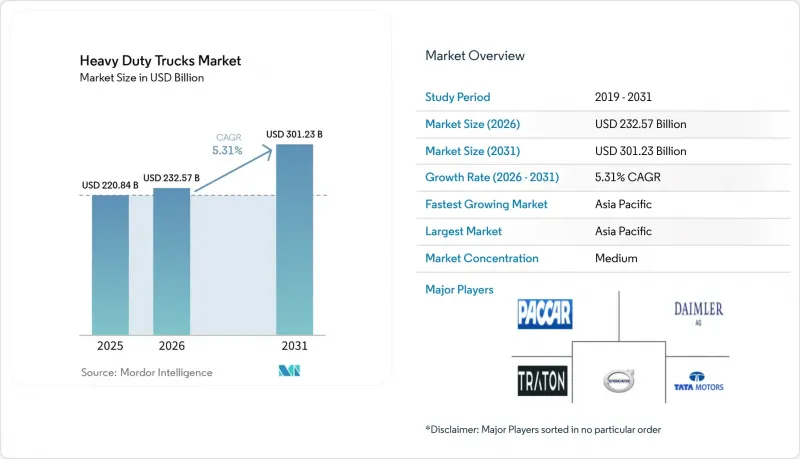
This report is Segmented by Tonnage Type (10 To 15 T and More Than 15 T), Class (Class 7 and Class 8), Propulsion Type (Diesel, Battery-Electric, and More), Application (Construction and Mining, and More), Truck Body Type (Tractor-Trailer, and More), Sales Channel (OEM, and More), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Heavy Duty Trucks Market Trends and Insights
Expanding E-commerce Freight Volumes
E-commerce freight expansion drives heavy-duty truck demand through last-mile delivery optimization and regional distribution network densification. The surge in online retail creates demand for medium-duty electric trucks in urban environments, where zero-emission mandates increasingly restrict diesel operations. Parcel and less-than-truckload shipments are reshaping fleet composition as online retail penetration deepens. The American Trucking Associations projects U.S. freight tonnage will rise from 11.27 billion tons in 2024 to 13.99 billion tons by 2035, placing sustained pressure on regional haul assets. Zero-emission zones in California, New York, and several European cities push operators toward Class 7 and lighter Class 8 tractors, duty cycles that align with the current battery range of 200-300 kilometers. Amazon's pledge to field 100,000 electric delivery vehicles by 2030 illustrates early-adopter willingness to absorb capital premiums for compliance and brand positioning. Operators also benefit from premium freight rates on time-sensitive cargo, partially offsetting higher vehicle prices. The shift toward higher-value goods further incentivizes investments in telematics and predictive maintenance that maximize uptime.
Strict Global Emission Mandates Driving Fleet Renewal
Regulatory frameworks across major markets create unprecedented pressure for fleet electrification, with the EPA's Phase 3 standards requiring 50% of vocational vehicles to be zero-emission by 2032. Regulators are compressing replacement cycles by tightening NOx and CO2 limits. The U.S. EPA Clean Trucks Plan stipulates that zero-emission models must reach 40% of new Class 8 tractor sales by model year 2032, with interim steps beginning in 2027. Euro VII standards entering force in 2027 impose real-world testing and onboard diagnostics that add 10-15% to diesel engine costs, narrowing the price gap with battery-electric alternatives. Fleets delaying electrification risk stranded assets as resale values for older diesels fall in restricted zones, a trend amplified by California's Advanced Clean Trucks rule. China's rapid adoption of zero-emission heavy-duty vehicles, with over 80% of global electric truck sales, demonstrates how policy can accelerate market transformation.
High Upfront Cost of Zero-emission Heavy Trucks
Battery-electric Class 8 tractors still cost two to three times more than diesel equivalents, with 2025 list prices of USD 350,000-400,000 versus USD 150,000-180,000 for conventional units. Subsidies such as California's HVIP vouchers, which can reach USD 240,000 per truck, ease but do not eliminate the premium. In price-sensitive economies, cash-flow constraints prevent smaller fleets from absorbing even subsidized differentials. Financiers also demand higher interest spreads to compensate for uncertain residual values and battery degradation beyond year 7.
Other drivers and restraints analyzed in the detailed report include:
- Infrastructure Stimulus Packages
- Hydrogen Corridor Pilot Programs in Asia Pacific
- Volatile Diesel Price Environment Impacting Purchase Cycles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The heavy-duty trucks market size for vehicles above 15 tons stayed dominant with a 61.40% revenue share in 2025, reflecting the still-critical role of long-haul and construction logistics. The segment continues to grow, supported by infrastructure spending but tempered by higher battery mass penalties. Conversely, the 10-15 ton bracket is advancing at a 9.50% CAGR; cities granting delivery privileges to lighter gross vehicle weights foster this outperformance. Europe's proposed 1-ton allowance for battery-electric rigids aims to preserve payload parity and is catalyzing OEM portfolio additions.
Operators report that the "Goldilocks" mid-weight class balances range, payload, and chassis cost. Daimler's eActros 300 achieved a 220-kilometer real-world range in Swiss pilots, covering a full double-shift with overnight charging. Battery prices nearing USD 110 per kilowatt-hour in 2026 are making mid-weight electrification financially attractive within three-year payback windows. Policy signals in California and Paris that prohibit diesels over 12 tons inside city limits after 2030 further anchor demand. As a result, the 10-15 ton segment is set to raise its share of the heavy-duty trucks market to roughly 30% by 2031.
Class 8 maintained a commanding 70.8% presence in 2025, driven by interstate haulage and heavy construction. With an 8.30% CAGR forecast, Class 7 gains from duty cycles of 150-200 miles that match current battery ranges without en-route charging. CARB requires 40% zero-emission sales for Class 7 tractors by 2032, accelerating OEM roadmaps.
Mack's MD Electric offers a 150-kilowatt-hour pack and 140-mile range, succeeding in beverage and food-service fleets where predictable routes enable scheduled charging. Class 8 electrification remains experimental but promising; megawatt chargers rolling out on U.S. I-5 and German Autobahns enable 45-minute turnarounds. The heavy-duty trucks market share for Class 8 is projected to slip below 68% by 2031 as medium-duty adoption accelerates.
Complete Report Scope:
- By Tonnage Type
- 10 to 15 T
- More Than 15 T
- By Class
- Class 7
- Class 8
- By Propulsion Type
- Diesel
- Battery-Electric
- Fuel-Cell Electric (FCEV)
- Alternative Fuels (CNG, LNG, Biodiesel)
- By Application
- Construction and Mining
- Freight and Logistics
- Municipal and Utilities
- Others
- By Truck Body Type
- Tractor-Trailer
- Rigid Dump
- Tanker
- Others
- By Sales Channel
- OEM/First Purchase
- Lease and Rental
- After-market Retrofit
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific led with a 47.21% revenue share in 2025 and is projected to grow at a 9.30% CAGR to 2031, buoyed by China's manufacturing scale and regional hydrogen corridors. Sinotruk, FAW, and Dongfeng captured over 60% of regional volumes as the National VI standard and municipal incentives in Beijing and Shanghai accelerated urban electrification. India's Tata Motors launched the Prima EV in 2024, addressing metropolitan freight and select mining customers, while state subsidies in Delhi and Maharashtra target 8,000 zero-emission trucks by 2028. Japan's Fukushima Hydrogen Highway underpins fuel-cell pilots, and Australia's Fortescue Metals Group invests in hydrogen haulage to cut Scope 1 emissions.
North America held a 28% share, animated by the U.S. EPA Clean Trucks Plan and federal charging grants. California's Advanced Clean Trucks rule and incentives reaching USD 240,000 per vehicle sustain the nation's largest zero-emission fleet pipeline. Canada's up-to-CAD 200,000 rebates drive uptake along the Windsor-Quebec corridor, while Mexico's cross-border carriers electrify to maintain California access. Europe contributed 18% in 2025, with Euro VII standards and Germany's Autobahn megawatt chargers catalyzing adoption. The United Kingdom mandates 10% zero-emission truck sales by 2030, scaling to 100% by 2040. France and Italy support LNG as a bridge fuel, whereas Scandinavia pushes battery-electric solutions across all classes.
The Middle East and Africa collectively accounted for 7%, with Dubai and Riyadh piloting Chinese battery-electric rigs for urban deliveries. Extreme temperatures necessitate advanced thermal management, slowing broader adoption. Latin America's mining belts in Chile and Peru represent early hydrogen fuel-cell demand, but broader market growth is constrained by financing costs and infrastructure gaps.
- Daimler Truck Holding AG
- Traton SE
- Volvo Group
- PACCAR Inc.
- Dongfeng Motor Corporation
- Tata Motors Ltd.
- FAW Group Corp.
- CNHTC (Sinotruk)
- Ashok Leyland Ltd
- Isuzu Motors Ltd.
- Hino Motors Ltd.
- Navistar International
- Iveco Group N.V.
- Hyundai Motor Co.
- Nikola Corporation
- JAC Motors
- Kamaz PJSC
- Foton Motor Co. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expanding E-Commerce Freight Volumes
- 4.2.2 Strict Global Emission Mandates Driving Fleet Renewal
- 4.2.3 Infrastructure Stimulus Packages
- 4.2.4 Hydrogen Corridor Pilot Programs in Asia Pacific
- 4.2.5 OTA-Enabled TCO Optimization for Fleet Managers
- 4.2.6 Mining Sector Electrification Commitments in South America
- 4.3 Market Restraints
- 4.3.1 High Upfront Cost of Zero-Emission Heavy Trucks
- 4.3.2 Volatile Diesel Price Environment Impacting Purchase Cycles
- 4.3.3 Semiconductor Shortages Delaying ADAS/EV Production
- 4.3.4 Stricter EU Axle-Weight Rules Limiting Payload Economics
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Tonnage Type
- 5.1.1 10 to 15 T
- 5.1.2 More Than 15 T
- 5.2 By Class
- 5.2.1 Class 7
- 5.2.2 Class 8
- 5.3 By Propulsion Type
- 5.3.1 Diesel
- 5.3.2 Battery-Electric
- 5.3.3 Fuel-Cell Electric (FCEV)
- 5.3.4 Alternative Fuels (CNG, LNG, Biodiesel)
- 5.4 By Application
- 5.4.1 Construction and Mining
- 5.4.2 Freight and Logistics
- 5.4.3 Municipal and Utilities
- 5.4.4 Others
- 5.5 By Truck Body Type
- 5.5.1 Tractor-Trailer
- 5.5.2 Rigid Dump
- 5.5.3 Tanker
- 5.5.4 Others
- 5.6 By Sales Channel
- 5.6.1 OEM/First Purchase
- 5.6.2 Lease and Rental
- 5.6.3 After-market Retrofit
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Rest of North America
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Italy
- 5.7.3.5 Russia
- 5.7.3.6 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 India
- 5.7.4.3 Japan
- 5.7.4.4 South Korea
- 5.7.4.5 Australia and New Zealand
- 5.7.4.6 Rest of Asia-Pacific
- 5.7.5 Middle East and Africa
- 5.7.5.1 Saudi Arabia
- 5.7.5.2 United Arab Emirates
- 5.7.5.3 Egypt
- 5.7.5.4 Turkey
- 5.7.5.5 South Africa
- 5.7.5.6 Rest of Middle East and Africa
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Daimler Truck Holding AG
- 6.4.2 Traton SE
- 6.4.3 Volvo Group
- 6.4.4 PACCAR Inc.
- 6.4.5 Dongfeng Motor Corporation
- 6.4.6 Tata Motors Ltd.
- 6.4.7 FAW Group Corp.
- 6.4.8 CNHTC (Sinotruk)
- 6.4.9 Ashok Leyland Ltd
- 6.4.10 Isuzu Motors Ltd.
- 6.4.11 Hino Motors Ltd.
- 6.4.12 Navistar International
- 6.4.13 Iveco Group N.V.
- 6.4.14 Hyundai Motor Co.
- 6.4.15 Nikola Corporation
- 6.4.16 JAC Motors
- 6.4.17 Kamaz PJSC
- 6.4.18 Foton Motor Co. Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

