PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124467

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124467
Singapore Self-Storage - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, Singapore self-Storage market size in 2026 is estimated at 3.29 million sq ft, growing from 2025 value of 3.11 million sq ft with 2031 projections showing 4.37 million sq ft, growing at 5.85% CAGR over 2026-2031.
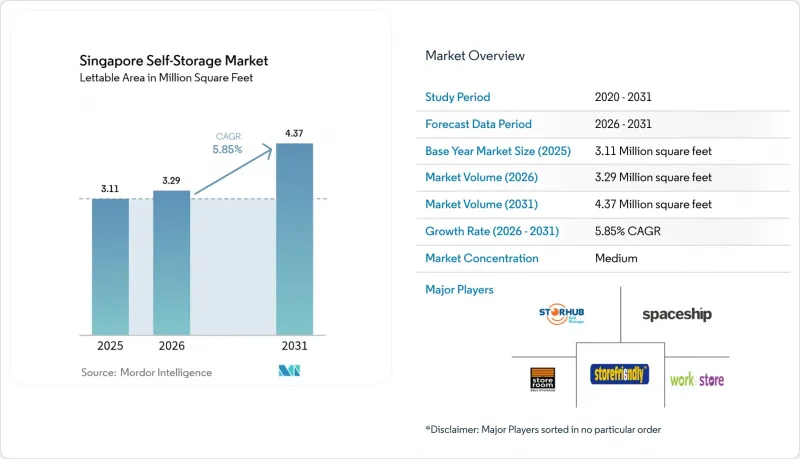
This report is Segmented by End-User (Personal and Business), Storage Size (Small and Medium Units Less Than 40 Sq Ft, Large Units Above 40 Sq Ft, and More), Storage Type (Climate-Controlled and Non-Climate-Controlled), and Ownership Pattern (Owned Facilities and Leased Facilities). The Market Forecasts are Provided in Terms of Volume (Units).
Singapore Self-Storage Market Trends and Insights
High Population Density and Affluent Demographics Boost Discretionary Storage Demand
Singapore packs around 8,000 residents into each square kilometer, a figure unmatched in Asia outside of micro-states. Residents rank living-space constraints among their top stressors, and 50% admit shelving household items externally when feasible. Rising household incomes support recurring rental fees, while a non-resident population that climbed 5% in 2024 values the flexibility to store possessions between relocations. Vertical city planning, exemplified by 50-storey public-housing blocks, concentrates living yet safeguards livability, indirectly pushing belongings into the Singapore self-storage market. Government programs such as GreenGov.SG further normalize "access over ownership," nurturing structural demand for paid storage.
Shrinking Residential Floor Area from Urban Redevelopment Projects
Higher plot-ratio allowances in prime districts shrink flat sizes even as total housing stock rises. The 2019 Master Plan rezoning of Tanjong Rhu for 5,000 new homes exemplifies how redevelopment favors compact units. The 1H 2025 Government Land Sales program will introduce 8,505 private units, largely within integrated mixed-use projects. As older estates undergo en bloc redevelopment, households downgrade in space and compensate by renting self-storage. This trend guarantees a long-run feedstock of consumers for the Singapore self-storage market.
High Land Costs Inflating Unit Rental Rates
Industrial land in core districts commands SGD 20-23 per sq m monthly, a baseline many operators exceed to secure sites JTC. While affluent users absorb higher fees, price-sensitive households may delay adoption or downgrade unit sizes. To maintain occupancy, leading brands offer promotional bundles, StorHub enables two months free rent alongside 30% discounts. Sustained rental inflation therefore tempers the Singapore self-storage market's longer-term CAGR even as nominal revenue grows.
Other drivers and restraints analyzed in the detailed report include:
- SME and E-commerce Micro-Fulfilment Growth Needing Flexible Inventory Space
- Institutional Investors' Entry Improving Funding Access and Build-Out Pace
- Limited Supply of Industrial-Zoned Land for New Facilities
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The business segment contributes a 7.05% CAGR to the Singapore self-storage market while personal storage still commands 61.12% share in 2025. Companies favor climate-controlled units and 24/7 access, accepting premium tariffs that elevate revenue per square foot. E-commerce micro-sellers exploit facilities as mini-fulfillment nodes to shorten delivery lead times. Meanwhile, the personal cohort remains a stable volume anchor, driven by apartment downsizing and expatriate churn. Together they sustain broad occupancy, though enterprise clients set the pricing tone through higher service expectations. The Singapore self-storage market size allocated to business users is projected to approach 1.7 million sq ft by 2031, supported by RTS-enabled binational trade flows.
Small and medium units still account for 48.10% of the Singapore self-storage market size, reflecting individual consumers' need to stash household overflow. Yet units exceeding 40 sq ft post a 6.62% CAGR as merchants consolidate inventory nearer to end-customers. SingPost's capacity upgrade lifts parcel volumes, encouraging sellers to stage stock downtown rather than at distant warehouses. Operators respond by reconfiguring upper floors into contiguous blocks that can be subdivided on demand. Large-unit penetration thus signals the market's shift from pure personal-effects storage to hybrid inventory solutions aligned with omnichannel retail growth.
Complete Report Scope:
- By End-User
- Personal
- Business
- By Storage Size
- Small and Medium Units (less than 40 sq ft)
- Large Units (above 40 sq ft)
- Others (Lockers/Double-Stacked)
- By Storage Type
- Climate-Controlled
- Non-Climate-Controlled
- By Ownership Pattern
- Owned Facilities
- Leased Facilities
List of Companies Covered in this Report:
- StorHub Self Storage Pte Ltd
- Extra Space Self Storage Singapore Pte Ltd
- General Storage Company Pte Ltd ("Lock+Store")
- Store Friendly Management (Singapore) Pte Ltd
- Work Plus Store Pte Ltd ("Work+Store")
- Spaceship Singapore (Astore Pte Ltd)
- Store Room Pte Limited
- Beam Storage Pte Ltd
- Far East Organization Pte Ltd ("Store-Y")
- Mandarin Self Storage Pte Ltd
- Urban Space Self Storage Pte Ltd
- Singapore G Pte Ltd ("U-Store@SG")
- Cube Self Storage Pte Ltd
- Extra Space Asia Holdings Pte Ltd (Regional arm)
- MyStore Self Storage Pte Ltd
- Boxpark Storage Pte Ltd
- SelfStore Pte Ltd
- JustStoreIt! Pte Ltd
- StoreHub Group Pte Ltd
- Store-N-Go Pte Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 High population density and affluent demographics boost discretionary storage demand
- 4.2.2 Shrinking residential floor area from urban redevelopment projects
- 4.2.3 SME and e-commerce micro-fulfilment growth needing flexible inventory space
- 4.2.4 Institutional investors' entry improving funding access and build-out pace
- 4.2.5 Rise of cross-border digital nomads using Singapore as an intermittent base
- 4.2.6 Mandatory Green-Mark retrofit storage compliance spiking temporary demand
- 4.3 Market Restraints
- 4.3.1 High land costs inflating unit rental rates
- 4.3.2 Limited supply of industrial-zoned land for new facilities
- 4.3.3 Stringent Fire-Safety Code-2025 raising cap-ex for multilevel facilities
- 4.3.4 Concierge storage start-ups cannibalising traditional unit occupancy
- 4.4 Impact of Macroeconomic Factors
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Investment Analysis
- 4.10 PESTEL Analysis
- 4.11 Key Considerations of Consumers while selecting a Self-Storage Facility
5 MARKET DYNAMICS IN SINGAPORE
- 5.1 Analysis of Occupancy Rates
- 5.2 Average Rental Trends
- 5.2.1 Pre-Covid and Post-Covid Market Implications
- 5.3 Profitability Analysis
- 5.3.1 Pre-Covid and Post-Covid Market Implications
- 5.4 Average Facility Size
6 MARKET SIZE AND GROWTH FORECASTS (UNITS)
- 6.1 By End-User
- 6.1.1 Personal
- 6.1.2 Business
- 6.2 By Storage Size
- 6.2.1 Small and Medium Units (less than 40 sq ft)
- 6.2.2 Large Units (above 40 sq ft)
- 6.2.3 Others (Lockers/Double-Stacked)
- 6.3 By Storage Type
- 6.3.1 Climate-Controlled
- 6.3.2 Non-Climate-Controlled
- 6.4 By Ownership Pattern
- 6.4.1 Owned Facilities
- 6.4.2 Leased Facilities
7 COMPETITIVE LANDSCAPE
- 7.1 Market Concentration
- 7.2 Strategic Moves
- 7.3 Market Share Analysis
- 7.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, Recent Developments)
- 7.4.1 StorHub Self Storage Pte Ltd
- 7.4.2 Extra Space Self Storage Singapore Pte Ltd
- 7.4.3 General Storage Company Pte Ltd ("Lock+Store")
- 7.4.4 Store Friendly Management (Singapore) Pte Ltd
- 7.4.5 Work Plus Store Pte Ltd ("Work+Store")
- 7.4.6 Spaceship Singapore (Astore Pte Ltd)
- 7.4.7 Store Room Pte Limited
- 7.4.8 Beam Storage Pte Ltd
- 7.4.9 Far East Organization Pte Ltd ("Store-Y")
- 7.4.10 Mandarin Self Storage Pte Ltd
- 7.4.11 Urban Space Self Storage Pte Ltd
- 7.4.12 Singapore G Pte Ltd ("U-Store@SG")
- 7.4.13 Cube Self Storage Pte Ltd
- 7.4.14 Extra Space Asia Holdings Pte Ltd (Regional arm)
- 7.4.15 MyStore Self Storage Pte Ltd
- 7.4.16 Boxpark Storage Pte Ltd
- 7.4.17 SelfStore Pte Ltd
- 7.4.18 JustStoreIt! Pte Ltd
- 7.4.19 StoreHub Group Pte Ltd
- 7.4.20 Store-N-Go Pte Ltd
8 MARKET SHARE OF KEY SELF-STORAGE OPERATORS
9 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 9.1 White-space and Unmet-Need Assessment

