PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125629

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125629
Germany Self Storage - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Germany self storage market size is expected to increase from 26.2 million square feet in 2025 to 27.81 million square feet in 2026 and reach 36.53 million square feet by 2031, growing at a CAGR of 5.61% over 2026-2031.
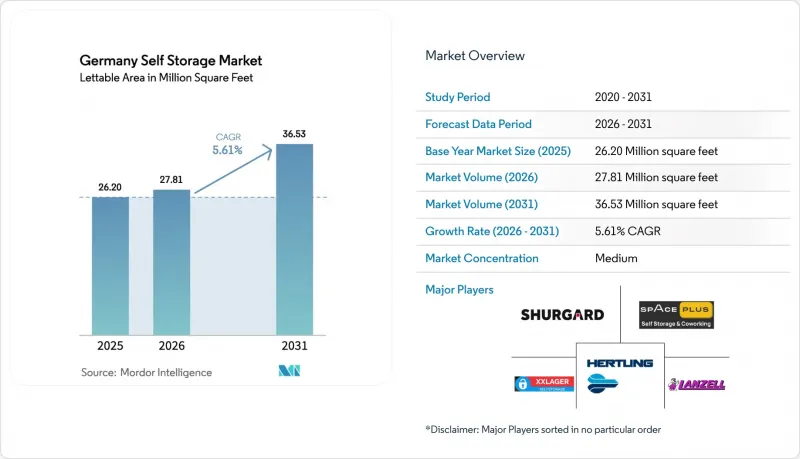
This report is Segmented by End-User (Personal, and Business), Storage Size (Small and Medium Units (Less Than 40 Sq Ft), Large Units (Above 40 Sq Ft), and More), Storage Type (Climate-Controlled, and Non-Climate-Controlled), Ownership Pattern (Owned, and Leased). The Market Forecasts are Provided in Terms of Volume (Million Sq Ft).
Germany Self Storage Market Trends and Insights
Urbanization and Shrinking Average Dwelling Size
Germany's sustained urban migration is compressing per-capita living area, triggering a structural hand-off of surplus belongings to external facilities. Single-person households reached 41.9% of total dwellings in 2024, while average new-build apartment sizes fell by roughly 3 square meters during 2020-2024. Berlin and Munich command rent premiums above EUR 20 (USD 21.4) per square meter, nudging tenants to treat self-storage as an affordable annex. Operators are bundling concierge retrieval, digital inventories, and insurance to lock customers into multi-year contracts. Longer dwell durations lift occupancy stability and let owners pass through inflation-linked escalators, a pattern that underpins the resilience of the Germany self-storage market. With room sizes set to tighten further under municipal densification plans, demand visibility on this driver remains high through at least 2030.
Growth in E-Commerce and SME Inventory Requirements
E-commerce penetration hit 15.1% of German retail sales in 2024 and parcel throughput topped 4.3 billion consignments. Small merchants that lack dedicated warehouses are leasing storage bays near autobahn interchanges to stage fast-moving SKUs for next-day dispatch. Rhine-Ruhr operators outfitting units with pallet racking and loading docks command double-digit rent premiums and near-full occupancy, reinforcing the short-cycle growth of the Germany self-storage market. Business tenants' willingness to pay for operational features helps balance seasonal volatility in personal demand and provides upside for revenue-management systems that price space by hourly access rather than static square footage.
Restrictive Zoning and Lengthy Planning Approvals
Germany's Baugesetzbuch framework excludes self-storage from many mixed-use zones, pushing developers to outlying industrial parcels. In Bavaria, approvals for greenfield facilities stretch 18-24 months due to mandatory impact assessments and community hearings. Heritage overlays in Berlin and Hamburg bar facade changes, stalling adaptive-reuse opportunities. Carrying costs during protracted entitlements erode returns and favor deep-pocketed investors that can warehouse land, hampering the organic scaling pace of the Germany self-storage market. Smaller entrants instead gravitate toward leased conversions where zoning hurdles are lower, but those sites often lack prime visibility and must rely on digital marketing to capture demand.
Other drivers and restraints analyzed in the detailed report include:
- Investor Appetite and Institutional Capital Driving Rapid Facility Expansion
- Accelerating Residential Mobility Among Students and Professionals
- Escalating Urban Land and Construction Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Personal tenants occupied 73.92% of capacity in 2025, underscoring how the Germany self-storage market evolved as a household space-extension solution. Urban renters store seasonal sports gear, archived memorabilia, and heirloom furniture, often treating external units as semi-permanent home annexes. Operators have responded with curated insurance, item-level barcoding, and 24/7 smartphone-based entry, ensuring that personal demand remains a stable revenue pillar despite modest growth. Business users, although currently smaller, are scaling at a 6.37% CAGR, reflecting e-commerce sellers, trades contractors, and professional-services firms archiving client files. Shurgard notes that corporate renters deliver 28% of German revenue while occupying 22% of square footage, highlighting stronger yield potential.
Over the forecast horizon, personal demand growth moderates but remains structurally supported by urban densification and demographic churn. Facility operators segment buildings by floor, dedicating ground-level and drive-up bays to SMEs shipping palletized inventory daily, while upper floors cater to households that access units only a few times per year. This spatial stratification maximizes revenue per square foot and balances peak usage loads, a tactic increasingly critical as the Germany self-storage industry integrates dynamic pricing engines. Business occupants reinforce weekday traffic and raise ancillary-service uptake, such as receipt-handling and parcel dispatch, thereby diversifying income streams beyond pure rent.
Units below 40 square feet held 47.34% of total inventory in 2025, mirroring tight urban living but also benefiting from high turnover that enables granular repricing. Large bays above 40 square feet enjoy a faster 5.84% CAGR because SMEs need pallet-racked space close to urban delivery corridors. Sensorberg-enabled smart locks now allow unmanned control of oversized units, streamlining access for van drivers and reducing security overhead. Operators retrofit older layouts, removing internal walls to stitch together contiguous zones that appeal to commercial renters with variable inventory volumes.
Larger bays deliver superior absolute monthly rent even though square-foot rates moderate slightly, lifting facility-level NOI where enterprise adoption is rising. Conversely, micro-lockers and double-stacked configurations are flourishing as courier drop-boxes in dense neighborhoods, underlying the versatility of sizing strategies within the Germany self-storage market. Owners leverage modular partitions to pivot between size mixes according to quarterly demand signals captured via IoT occupancy sensors, creating a nimble asset base that can capture both personal downsizing waves and business inventory bursts.
Complete Report Scope:
- By End-User
- Personal
- Business
- By Storage Size
- Small and Medium Units (Less than 40 sq ft)
- Large Units (Above 40 sq ft)
- Others (Lockers/Double-Stacked)
- By Storage Type
- Climate-Controlled
- Non-Climate-Controlled
- By Ownership Pattern
- Owned
- Leased
List of Companies Covered in this Report:
- Shurgard Self-Storage SA
- SelfStorage Dein Lagerraum GmbH (MyPlace Self-Storage)
- Space Plus Store GmbH
- Rousselet Groupe SA (HOMEBOX)
- Pickens Selfstorage GmbH
- Lagerbox Holding GmbH and Co. KG
- 1BOX Deutschland GmbH
- Storebox Holding GmbH
- ZeitLager GmbH
- XXLAGER Selfstorage GmbH
- BOXIE24 Deutschland GmbH
- Store Room Self-Storage
- SecurCare Self Storage
- KingBox Self-Storage GmbH
- CityBox24 GmbH
- CubeStorage Deutschland GmbH
- Jojo-Lagerhaus GmbH
- Easy-Selfstorage GmbH
- Container Self-Storage AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Urbanisation and Shrinking Average Dwelling Size
- 4.2.2 Growth in E-Commerce and SME Inventory Requirements
- 4.2.3 Accelerating Residential Mobility Among Students and Professionals
- 4.2.4 Investor Appetite and Institutional Capital Driving Rapid Facility Expansion
- 4.2.5 Corporate Archiving Mandates Boosting Off-Site Document Storage
- 4.2.6 Smart-Lock and App-Based 24/7 Access Enabling Unmanned Micro-Stores in Tier-2 Cities
- 4.3 Market Restraints
- 4.3.1 Restrictive Zoning and Lengthy Planning Approvals
- 4.3.2 Escalating Urban Land and Construction Costs
- 4.3.3 Intensifying Competition from On-Demand Mobile Storage Start-Ups
- 4.3.4 Stricter ESG Retrofit Requirements Inflating CapEx Budgets
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Impact of Macroeconomic Factors
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Investment Analysis
- 4.9 PESTEL Analysis
- 4.10 Key Considerations of Consumers while Selecting a Self-Storage Facility
- 4.11 Market Dynamics in Germany
- 4.11.1 Analysis of Occupancy Rates
- 4.11.2 Average Rental Trends
- 4.11.3 Profitability Analysis
- 4.11.4 Average Facility Size
5 MARKET SIZE AND GROWTH FORECASTS (UNIT)
- 5.1 By End-User
- 5.1.1 Personal
- 5.1.2 Business
- 5.2 By Storage Size
- 5.2.1 Small and Medium Units (Less than 40 sq ft)
- 5.2.2 Large Units (Above 40 sq ft)
- 5.2.3 Others (Lockers/Double-Stacked)
- 5.3 By Storage Type
- 5.3.1 Climate-Controlled
- 5.3.2 Non-Climate-Controlled
- 5.4 By Ownership Pattern
- 5.4.1 Owned
- 5.4.2 Leased
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Shurgard Self-Storage SA
- 6.4.2 SelfStorage Dein Lagerraum GmbH (MyPlace Self-Storage)
- 6.4.3 Space Plus Store GmbH
- 6.4.4 Rousselet Groupe SA (HOMEBOX)
- 6.4.5 Pickens Selfstorage GmbH
- 6.4.6 Lagerbox Holding GmbH and Co. KG
- 6.4.7 1BOX Deutschland GmbH
- 6.4.8 Storebox Holding GmbH
- 6.4.9 ZeitLager GmbH
- 6.4.10 XXLAGER Selfstorage GmbH
- 6.4.11 BOXIE24 Deutschland GmbH
- 6.4.12 Store Room Self-Storage
- 6.4.13 SecurCare Self Storage
- 6.4.14 KingBox Self-Storage GmbH
- 6.4.15 CityBox24 GmbH
- 6.4.16 CubeStorage Deutschland GmbH
- 6.4.17 Jojo-Lagerhaus GmbH
- 6.4.18 Easy-Selfstorage GmbH
- 6.4.19 Container Self-Storage AG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

